ServiceNow Misses The Whisper As An 18.5% Q4 CRPO Guide Overshadows Its AI Bookings Surge
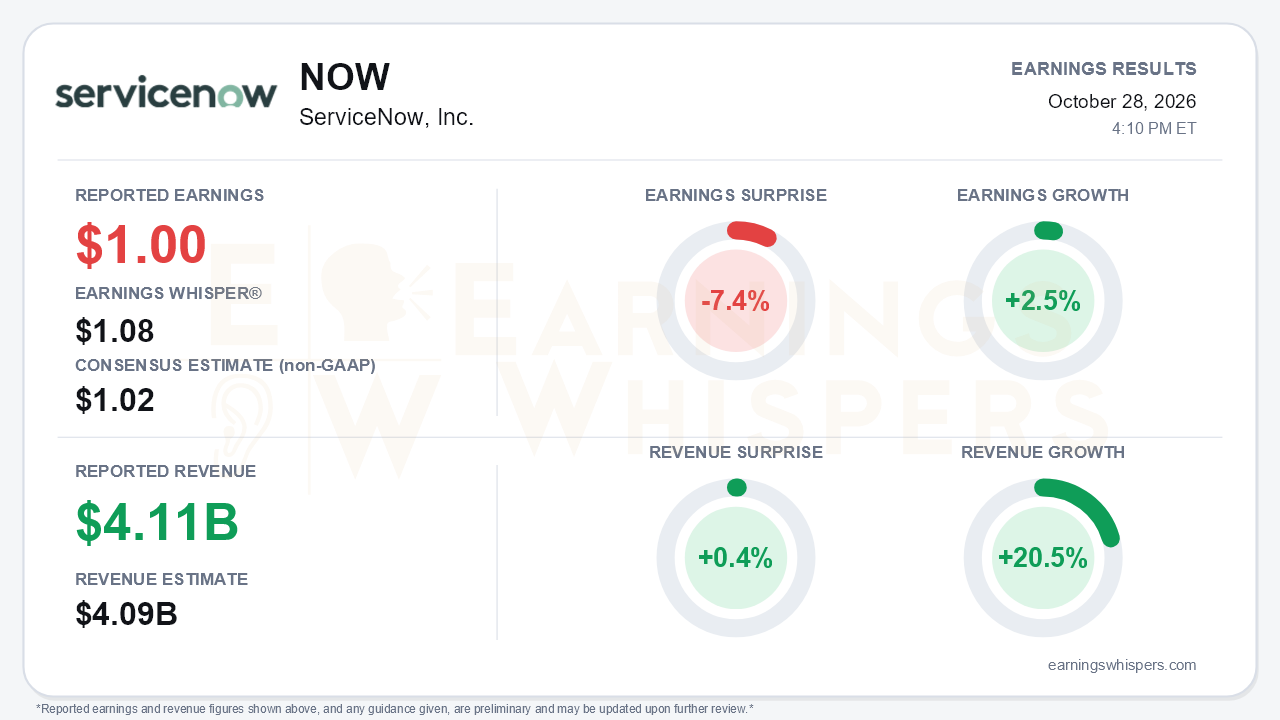
ServiceNow reported third-quarter non-GAAP earnings of $1.00 per share on revenue of $4.106 billion. That was short of the $1.02 consensus and well below the $1.08 Earnings Whisper number, a 7.4% shortfall against expectations. Revenue edged past the $4.09 billion consensus by 0.4% and grew 20.5% year over year, but earnings rose only 2.5% from a year ago. The company described the quarter as a beat of the high end of its own guidance on every topline and profitability metric, and by that yardstick it was. The central tension is that investors had priced in more than guidance implied, and the most important forward number in the release, fourth-quarter cRPO growth of 18.5% in constant currency, points to slower growth while the AI story is supposedly accelerating.
The weak earnings conversion deserves scrutiny. Non-GAAP operating margin was 32.5%, 150 basis points above guidance but below the 33.5% posted a year earlier. Non-GAAP subscription gross margin fell to 80% from 83%. Professional services swung to a non-GAAP gross loss of $23 million from a $12 million profit, partly because management chose to bundle deployment services into deals. Below the operating line, the roughly $9.2 billion spent on acquisitions this year is showing up in the numbers. Goodwill climbed to about $10 billion from $3.6 billion, and debt rose to roughly $7.5 billion. Interest expense jumped to $81 million from $6 million, while interest income fell. GAAP EPS dropped to $0.27 from $0.48, weighed down by a sharp rise in purchased-intangible amortization and severance. Free cash flow of $822 million was up from $592 million, but part of that improvement came from cutting capex to $91 million from $235 million.
The call preserved a credible demand story.
- AI net new ACV grew 65% year over year, and $1 million-plus AI deals grew 4.5-fold.
- Agentic consumption in production is up more than 13x year to date.
- CRM AI net new ACV tripled.
- Deals over $5 million in net new ACV rose more than 135%, and customers above $5 million in ACV reached 680, up from 658 in Q2.
- The renewal rate held at 98%.
- The AI ACV target was raised for a second time, to $1.7 billion from $1.5 billion in May and $1 billion at the start of the year.
Yet subscription growth slowed to 20.5% in constant currency from 23% in Q2. Management attributed part of that to on-prem revenue pulled forward into the prior quarter.
The Q4 cRPO outlook is where bears have legitimate ammunition. Guidance of 18.5% compares with 21% delivered in Q3 and 21.5% in Q2. Management cited several mechanical factors:
- early renewals pulled into Q3, which accounted for about half of the Q3 cRPO beat;
- a roughly 25-basis-point on-prem mix headwind;
- about 50 basis points of backlog excluded from cRPO;
- a subscription revenue drag of roughly 50 basis points in Q4 from services bundling.
Those explanations are plausible, but they mean part of the Q3 strength was borrowed from Q4. Only about half of the Q3 beat flowed into the full-year subscription guide, which rose just $15 million to $15.785 billion. That is the third straight raise, but a modest one. The full-year free cash flow margin target rose to 36% from 35% because of lower capex. Asked when AI traction becomes top-line acceleration, management pointed to 2027. Its tone remained highly promotional but was more defensive on mechanics.
The catalyst list is long. It includes the expanded OpenAI partnership, the Control Tower Alliance with Anthropic, AWS, NVIDIA and others, AI Passport, the Flow mid-market service desk, the Sweep tuck-in acquisition, the Aramco Digital agreement, and AI specialists expected to become generally available in Q4. These broaden the platform narrative. None of them changes the near-term cRPO math.
The market setup made the shortfall harder to absorb. Shares opened at $100 after the July report and had climbed 54.8% to $154.78 heading into this release. That left the stock just 3% below its inter-earnings high of $159.50, set October 23, about 69% above its post-July low, and roughly 34% above its 200-day moving average. The Earnings Whispers trend readings were broadly positive going in. Investor sentiment improved from -0.30 to -0.18 but remained negative, so skepticism had eased without disappearing. Shares reportedly fell meaningfully after hours on the Q4 guide, which is consistent with a stock that had run ahead of a report that reaffirmed demand but not acceleration.
The bottom line is that ServiceNow delivered strong bookings and AI metrics, but the earnings miss against the whisper, the compressed margins from acquisitions and bundling, and an 18.5% Q4 cRPO guide undercut the inflection narrative management promoted. After a 55% run, investors now have to wait until 2027 for evidence that AI momentum translates into faster revenue growth.
Read our earnings preview for ServiceNow, Inc.: https://www.earningswhispers.com/article/NOW/20968
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 57 min | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 3 hours |
Dow Jones Futures: Microsoft Rises Late, But Google, ServiceNow And Fortinet Dive On Earnings
NOW NOW -18.13% AH
Investor's Business Daily
|
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours |
ServiceNow Earnings Miss Amid Acquisitions, Revenue Beats
NOW NOW -18.13% AH
Investor's Business Daily
|
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours |
