EBay Beats As GMV Accelerates, But Thinning Monetization And A 5-7% Organic Revenue Guide Cloud The Story
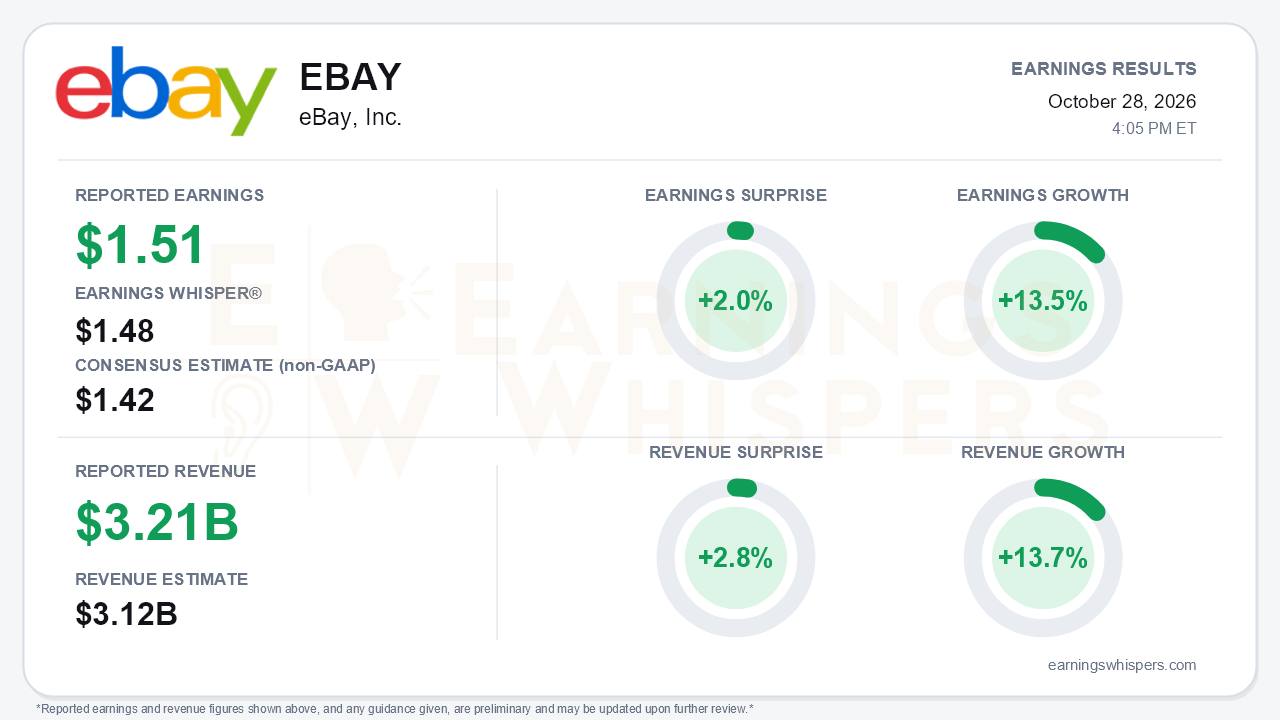
eBay delivered another clean beat on the numbers that headline writers track. Non-GAAP EPS of $1.51 topped the $1.42 consensus and the $1.48 Earnings Whisper number by 2.0%, and revenue of $3.206 billion beat the $3.12 billion consensus by 2.8%. Earnings grew 13.5% year over year and revenue grew 13.7%. Gross merchandise volume was the standout. It reached $23.2 billion, up 16% FX-neutral and 13% organically, against a guide that implied only 7-9% organic growth. Yet this quarter's real story sits beneath the beat. eBay is moving considerably more volume through its marketplaces while keeping less of each dollar, and that is the central tension.
The quality of the beat deserves scrutiny. Revenue grew more slowly than GMV, and the call showed that take rate fell 20 basis points year over year. That compares with roughly flat in Q2 and a 60-basis-point gain in Q4 2025. Management attributed the decline to eBay Live, C2C, contra-revenue shipping at Depop and a gross-to-net shift in the U.K. Gross margin has slid from 74.6% in Q1 to 74.1% in Q2 and 73.1% in Q3. Non-GAAP operating margin dipped to 26.3% from 27.0%, as sales and marketing spending jumped 23% to $747 million. GAAP EPS from continuing operations fell to $1.11 from $1.27. That decline largely reflects an unusual tax benefit in the prior-year quarter, when the effective tax rate was negative 4.3%, along with $28 million in transaction costs. Free cash flow of $749 million trailed both the $803 million from a year ago and the $898 million generated in Q1.
The deceleration is easiest to see in the sequence. Organic revenue growth has gone from 17% in Q1 to 14% in Q2, 11% in Q3, and now a 5-7% guide for Q4. On the company's own basis, non-GAAP EPS growth has slowed from 21% to 17% to 12%; Earnings Whispers' normalized figure for Q3 is 13.5%. The Q4 guide implies only 5-9% EPS growth. Advertising growth cooled to 16% from 23% in Q2 and 27% in Q1 as attribution changes were lapped. Underlying buyer growth also remains thin. The headline active-buyer count jumped to 147 million, but excluding Depop and Tise it was up only about 1%. International GMV grew just 4%, with Germany weak. U.S. collectibles are also decelerating against tougher trading-card comparisons, and management's 2027 planning assumes the category moderates.
The call nonetheless preserved a credible growth story. Strategic priorities grew roughly 20% and now represent 72% of GMV, while focus categories rose 24% and U.S. organic GMV climbed 22%. Depop is in hypergrowth. Its U.S. GMV more than doubled pro forma, and active buyers reached 11 million, up from about 9 million in Q2, with Depop expected to add about 4 points to Q4 GMV growth. eBay Live is running at a multibillion-dollar annualized rate with triple-digit growth, and TCGplayer passed $1 billion in trailing GMV. Management offered a preliminary 2027 view calling for healthy growth across GMV, revenue, operating income and EPS. It also announced a roughly 9% workforce reduction to fund growth initiatives, with $130-150 million of restructuring expense expected in Q4. Management's tone was its most confident yet, describing conviction that has "never been stronger." Bears still have legitimate ammunition: Depop is fighting Vinted with heavy marketing and shipping subsidies, net interest income will be a 2027 headwind after the $1.4 billion cash deal, and the layoffs carry execution risk.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive but weakened ahead of the report, slipping from 0.498 to 0.415. Shares closed at $117.83 the day before the release, up 5.2% since the open following the August report and 13.8% above the 200-day moving average. They had rebounded 18% from a September low of $99.85 to a 52-week high of $124.59 on October 15 before easing about 5% from that peak. The Earnings Whispers trend signals are uniformly positive, consistent with a stock that has been rewarded for its run of beats. Even so, cooling sentiment suggests investors were already weighing the margin and monetization questions this report sharpened.
The bottom line is that eBay's demand engine is clearly accelerating, driven by Depop, Live and focus categories, and guidance came in above estimates. That growth is increasingly being bought with lower take rates, compressed gross margins and heavier marketing. A 5-7% organic revenue guide and mid-single-digit EPS growth for Q4 mark a meaningful downshift from earlier in the year. The coming quarters need to show that today's GMV gains translate into revenue and margin, rather than simply volume.
Read our earnings preview for eBay, Inc.: https://www.earningswhispers.com/article/EBAY/20924
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 |
