IREN Must Show Its $4 Billion AI Cloud Backlog Turning Into Revenue
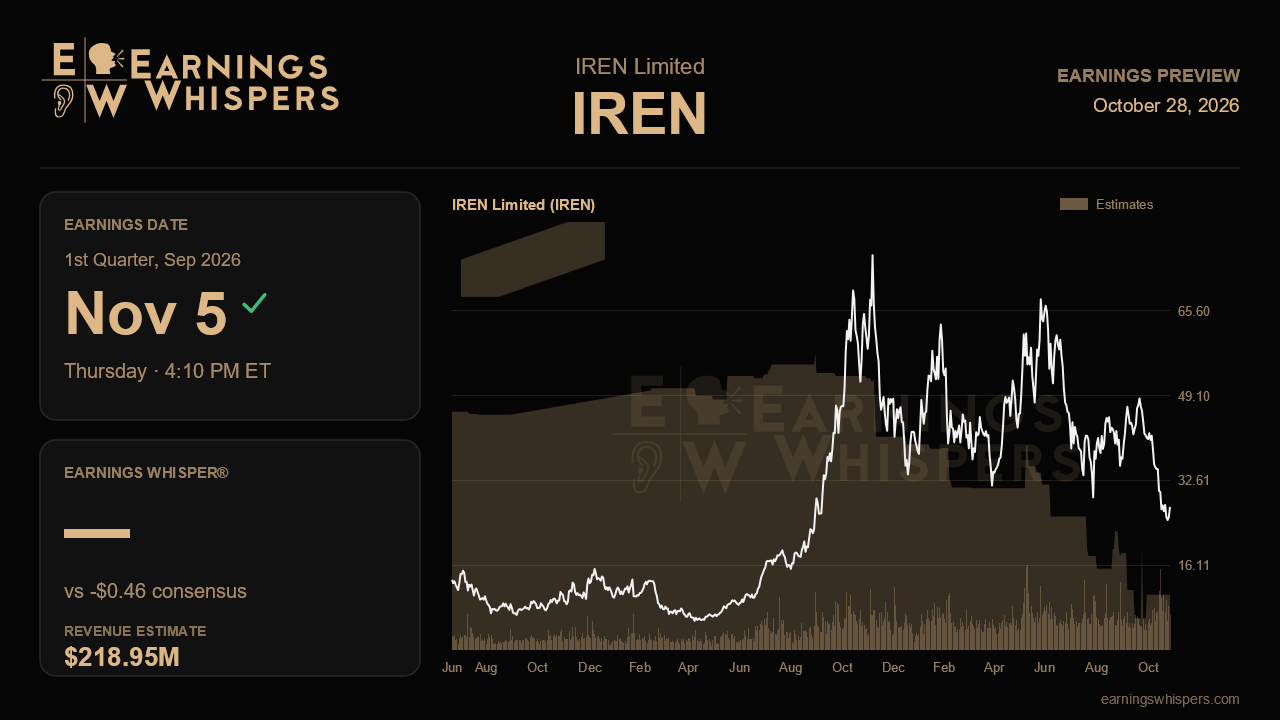
IREN heads into its September-quarter report with a striking mismatch between its story and its stock. On its last call, management described a business whose problem had shifted from finding customers and capital to building fast enough, with contracted annual recurring revenue climbing to $4.0 billion for 2026 capacity. Since then the shares have fallen 27.1% while the S&P 500 was essentially flat. This report is the first real chance to show that the backlog is starting to become reported revenue, and that the financing machine behind a $25 billion to $30 billion capital plan is still running.
The Street expects a GAAP loss of $0.46 per share on revenue of about $219.0 million. Against the year-ago quarter, that is a contraction: revenue down 8.9% from $240.3 million and a deeper loss than the prior-year $0.34. The sequential picture matters more. Revenue in the June quarter was just $137.2 million, the fourth straight decline as bitcoin miners were switched off ahead of GPU installs. Consensus therefore assumes a jump of roughly 60% in a single quarter. That fits management's comment that about $1 billion of ARR is already operating, which implies a quarterly run rate near $250 million once fully in service. A print well short of $219 million would suggest slower customer acceptance or billing ramps than the ARR headline implies.
The loss estimate needs more caution. Management flagged a $40 million to $50 million sequential rise in cash SG&A as it staffs up ahead of revenue. Mining wraps up by December 2026, so more non-cash impairments are possible. The prior quarter's $1.31 loss was inflated by more than $450 million of mining write-downs and about $102 million of fair-value markdowns. Further charges could swamp the operating picture in GAAP EPS, so revenue and the build-out timeline are better guides than the bottom line.
The operating checklist comes straight from last quarter's call. Horizon 1 was delivered to Microsoft, and Horizons 2 through 4 are targeted for the December quarter. Any slippage there would hit the narrative directly, because much of the $4.0 billion ARR comes online late in the year and lands mainly in the March quarter. Pricing is the second test. Management said three-year contract pricing had risen about 125% since November, with recent deals above $20 million per megawatt and talks near $25 million. Fresh contracts at or above those levels would confirm that the pricing power is real and not a one-off. Investors should also look for progress with the new frontier AI lab and the broader customer roster, including Cohere, Perplexity and Figure AI, along with any early managed-services revenue tied to the Mirantis hypervisor certification.
Financing is the biggest swing factor, and probably the main reason the stock has slumped. IREN raised $6.5 billion of GPU financing in three months, including $2.8 billion of non-investment-grade debt at single-digit rates. Customer prepayments now cover 45% to 55% of GPU capex on recent deals. Still, management said it needs about $8 billion more in GPU financing, and data center financing was only in preliminary talks. Closing even part of that, ideally secured against the still-unencumbered data center portfolio, would answer the market's main doubt.
Sentiment is mildly bearish and barely changed from last quarter. The stock trades at $27.44, far below its 200-day moving average of $44.75 and near the bottom of its post-earnings range of $23.72 to $49.37. That suggests the market has already priced in a good deal of execution and funding risk. The question this report must answer is whether IREN can turn signed contracts into delivered capacity on schedule while funding it on acceptable terms. If revenue lands near forecast, the Horizon timeline holds and new financing is announced, the strong narrative from last quarter stays intact despite the stock's slide.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
