Ford Beats Big And Lifts 2026 Floor Again, But A Flat 2027 Outlook Caps The Momentum
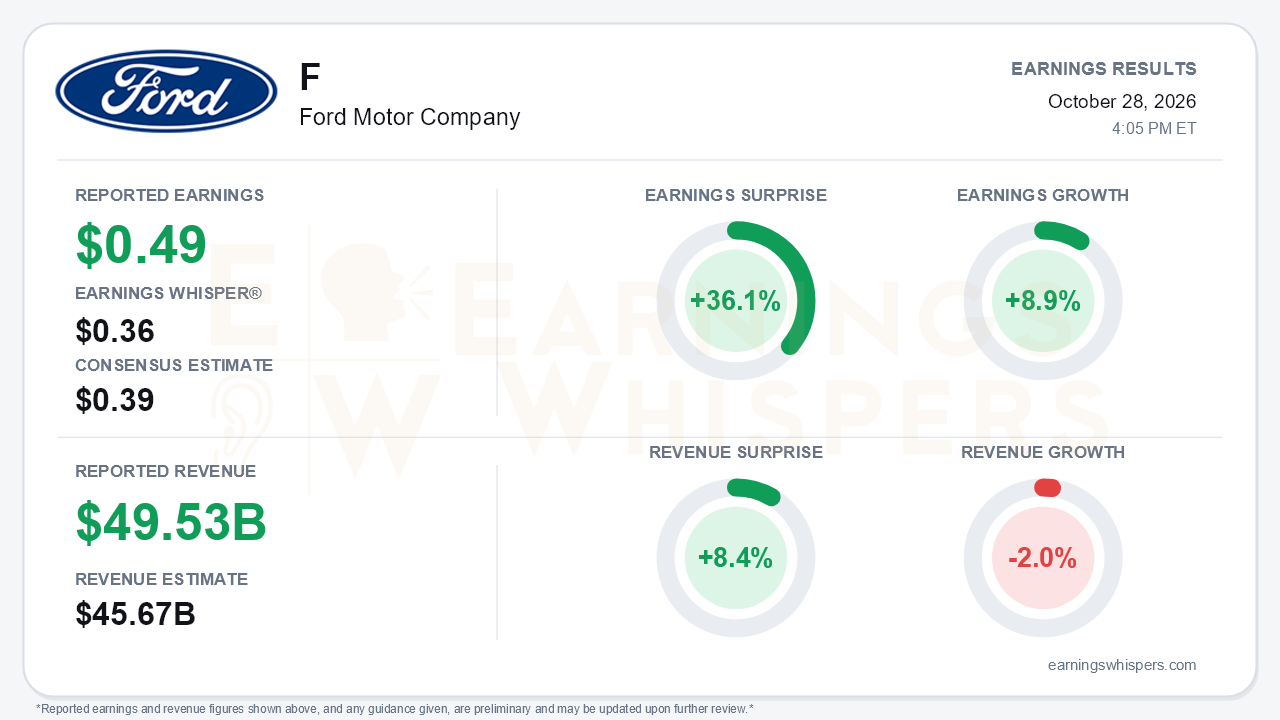
Ford delivered a decisive third-quarter beat, reporting earnings of $0.49 per share against a $0.39 consensus and a more cautious $0.36 Earnings Whisper. That is a 36.1% surprise. Revenue of $49.53 billion topped the $45.67 billion consensus by 8.4%, even though sales fell 2.0% from a year ago. Earnings grew 8.9% year over year, and Ford lifted its full-year 2026 adjusted EBIT range to $10.5-11 billion. That marks the third consecutive increase in a forecast that began the year at $8-10 billion. The central tension is that management simultaneously guided 2027 profit only roughly in line with 2026. A year of upward revisions now runs into a plateau.
The quality of the beat deserves scrutiny. Adjusted EBIT of $2.7 billion rose just 3% year over year, up from $2.5 billion in the second quarter. That is a far more modest improvement than the EPS surprise implies. Both core operating segments went backward. Ford Pro EBIT fell 16% to $1.7 billion and Ford Blue fell 10% to $1.4 billion, so the year-over-year gain did not come from the trucks-and-vans engine that anchors the investment case. Cash generation was the cleaner strength. Free cash flow jumped to $4.7 billion from $2.1 billion in Q2 and negative $1.9 billion in Q1, lifting cash to $25.3 billion. Even so, full-year free cash flow guidance stayed at $6-7 billion, with capex unchanged at $9.5-10.5 billion. Ford also maintained its 15-cent quarterly dividend.
The guidance details show a business being carried by pricing and Ford Credit while costs keep climbing. Management doubled its U.S. industry pricing assumption to +100 basis points, from +50 bp in Q2 and flat in Q1. It also moved its U.S. SAAR assumption to the top of the prior range at 16.5 million. Ford Credit EBT guidance rose to about $2.8 billion from above $2.5 billion, and Blue settled at about $5.5 billion, the top of its prior range. Pulling the other way, the commodity headwind rose again to roughly $2.5 billion. That compares with about $1 billion at the start of the year and just above $2 billion in Q1 and Q2. Ford Pro guidance slipped to about $7 billion, the low end of the prior $7-7.5 billion range, which management tied to commodities and Oakville launch costs. A late-quarter supplier disruption and Middle East volume pressure on Blue added further friction.
The call did preserve a credible longer-dated growth story. Ford Energy has more than 80% of 2028 capacity under executed contracts or late-stage negotiations, with full commitment expected by Q1 2027. The Fathom, the first vehicle on the new UEV platform, is priced from $28,350, with pre-orders in Q1 2027 and launch in Q4 2027. The Oakville Super Duty ramp is running ahead of plan and adds roughly 100,000 units of capacity for 2027 Pro growth. Software services and parts posted record revenue at about 10% of the quarter's total, and Ford climbed to the No. 1 certified pre-owned brand in the U.S. The bears have legitimate ammunition, though, and most of it is about timing:
- Model e expenses will rise in 2027 before a step-change in the first half of 2028, making the path to 2029 break-even non-linear.
- The 2027 plan must absorb roughly $2 billion of additional commodity, memory and logistics headwinds.
- F-150 changeover downtime and Ford Credit macro pressure are also expected next year.
- Management named UEV supply-base readiness as the main remaining launch risk.
The market had already been pricing in that fatigue. Shares trade at $11.95, down 23.2% since the open following the July report and 10.6% below the 200-day moving average of $13.36. Investor sentiment remained positive but weakened meaningfully, falling from 0.31 to 0.15. Earnings Whispers trend readings are mixed: earnings momentum is positive, while price and AVWAP trends remain negative. That split fits a stock whose near-term estimates keep rising while investors discount the 2027 setup.
The bottom line is that Ford's third quarter was better than feared on the surface and genuinely strong on cash. The underlying picture is less clean. EBIT growth was slim, both core segments declined, and the guidance raise leaned on pricing and Ford Credit rather than operating leverage. The flat 2027 outlook and heavier Model e spending defer the next leg of improvement into 2028. Investors must now weigh a beaten-down stock and a credible product pipeline against a profit trajectory that has stopped climbing.
Read our earnings preview for Ford Motor Company: https://www.earningswhispers.com/article/F/20931
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 40 min | |
| 40 min | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| Oct-28 |
Ford CEO Sees Upsell Opportunity With $30,000 EV Truck's Hands-Free Driving Tech
F
The Wall Street Journal
|
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 |
