T-Mobile Beats Handily And Lifts Profit Guidance, But Slowing Revenue And Rising Churn Keep Pressure On The Stock
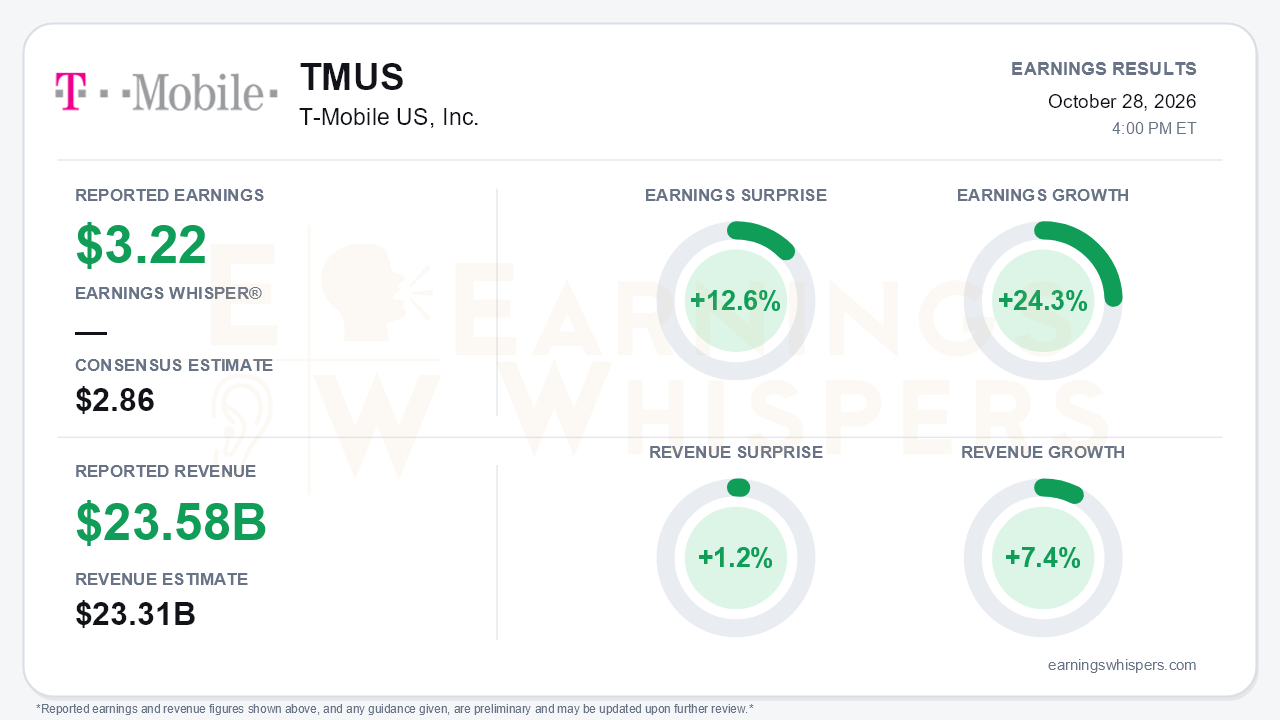
T-Mobile US delivered a clear third-quarter beat. Earnings of $3.22 per share topped the $2.86 consensus by 12.6%, and revenue of $23.584 billion exceeded the $23.31 billion estimate by 1.2%. Earnings grew 24.3% year over year on Earnings Whispers' normalized basis, and revenue rose 7.4%. Management also raised its full-year Core Adjusted EBITDA, free cash flow and postpaid ARPA outlooks. The central tension is that the profit story is strengthening while the top line is losing momentum. T-Mobile cut its service revenue target, reported growth rates are falling as acquisition benefits roll off, and churn moved higher. A stock already down sharply since the last report suggests investors are focused on that second part.
The quality of the beat deserves some scrutiny. GAAP diluted EPS rose 34% against a year-ago figure of $2.41, a quarter that included a $278 million impairment charge. Earnings Whispers' normalized 24.3% growth figure is the better gauge of underlying progress. Several other factors helped earnings and cash flow:
- **Buybacks:** T-Mobile spent $2.4 billion on repurchases in the quarter and $10.3 billion year to date, which reduces the share count.
- **Tax rate:** full-year effective tax rate guidance fell to 24%-25%.
- **Capital spending:** capex dropped 14% year over year to $2.3 billion.
The capex decline is a major reason Adjusted Free Cash Flow rose 5% to $5.1 billion even as operating cash flow slipped 2% to $7.3 billion. Core Adjusted EBITDA grew 11% to $9.6 billion, but it rose less than 1% sequentially. Special items also remained substantial: $129 million of UScellular merger costs and $50 million of store-closure costs were excluded from adjusted results this quarter.
The operating trends beneath the headline are mixed. ARPA is the strongest metric. Postpaid ARPA reached $155.73, up 4% year over year and up from $152.91 in the second quarter. Management raised full-year ARPA growth guidance to roughly 3.5% from 2.5%-3%. Account growth was solid but less vibrant:
- **Net account additions:** 274,000, beating the roughly 250,000 management had guided, but below the 396,000 added a year earlier.
- **Account churn:** rose to 1.09% from 0.99% in the second quarter and 0.97% a year ago.
- **Phone churn:** management did not disclose postpaid phone churn, which was 0.85% last quarter. It acknowledged that rate-plan modernization lifted churn in the third quarter, with residual effects expected in the fourth.
That combination shows T-Mobile pushing price and mix harder while accepting more customer friction.
Revenue deceleration is the bears' strongest argument. As acquisitions lap, the growth rates for the first, second and third quarters have fallen steadily:
- **Postpaid service revenue:** 15%, 13% and 9%.
- **Total service revenue:** 11%, 9% and 6%.
The full-year service revenue guide was trimmed to about $76.8 billion from roughly $77 billion, a target held since February. Management attributed the cut to faster Boost and TracFone wholesale roll-off and continued prepaid declines. Wholesale had been described as roughly flat on the prior call. Management also flagged unusual fourth-quarter variability from a staggered iPhone launch, device price increases and inventory constraints that shift costs into the quarter. The guidance implies slower EBITDA and account growth than the third-quarter run rate.
The catalyst list is longer than usual:
- **Edge computing:** an AWS partnership called Kinetic Edge.
- **Government:** the top spot on a Department of Justice wireless contract.
- **New plans:** the T-Mix plan portfolio, which lets customers choose and change benefits, aimed at rising industry device subsidies.
- **Network technology:** an AI-RAN call on the live network.
- **Broadband and digital:** accelerating fiber additions with about 20% 12-month penetration, and T-Life reaching 32 million monthly active users.
The risks are more immediate. Competitors are targeting one- and two-line accounts. CFO Peter Osvaldik is handing off to Jessica Yule. Management also signaled that more 2027-28 capital will go to spectrum auctions, which implies buybacks will moderate after supporting per-share results this year.
The market has been unforgiving. Shares fell 15.7% from the $175.75 open after the July report to $148.08. The stock sits about 21% below its 200-day moving average of $187.40. Investor sentiment moved from roughly neutral at -0.04 to a more clearly negative -0.20, a meaningful deterioration ahead of this report. The Earnings Whispers trend readings are split. Sequential growth and momentum are positive, while price and AVWAP trends remain negative, reflecting the gap between improving profitability and weak stock performance.
The bottom line is that T-Mobile delivered a strong quarter for profits and cash flow, with higher ARPA and three consecutive free cash flow guidance raises. However, the service revenue cut, higher churn and fading acquisition-driven growth give bears legitimate ammunition. The coming spending shift toward spectrum is another concern. Margin expansion and cash flow are working, but the stock's decline and souring sentiment show investors want evidence that organic revenue growth can hold up as acquisition benefits fade and buyback support moderates.
Read our earnings preview for T-Mobile US, Inc.: https://www.earningswhispers.com/article/TMUS/20993
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 40 min | |
| 56 min | |
| 2 hours | |
| 3 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 |
T-Mobile Stock Down 14.5% Amid SpaceX Fears, but Telecom Expert Says Selloff Is Overdone
TMUS
Benzinga Prediction Markets
|
| Oct-26 |
