American Water Misses Q3 Consensus, But Top-Half 2026 Guide And 8% 2027 Outlook Keep The Rate-Base Story Intact
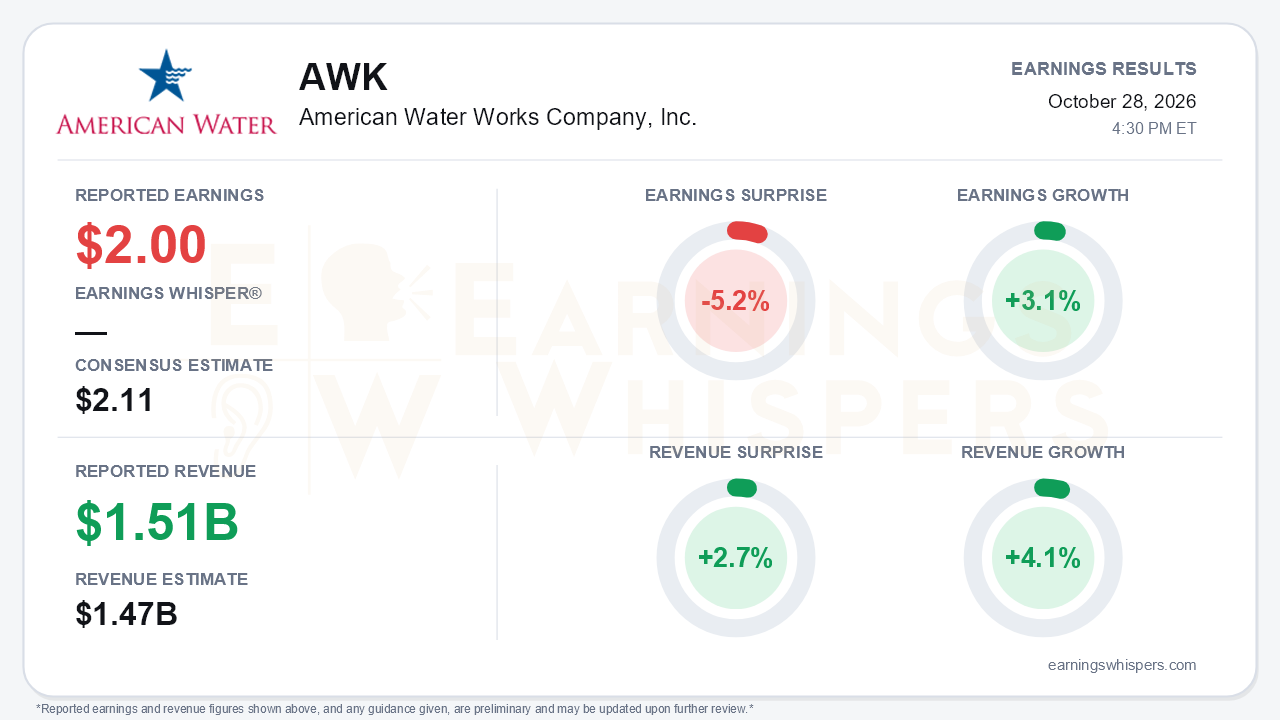
American Water Works (NYSE: AWK) reported third-quarter adjusted earnings of $2.00 per share, 5.2% below the $2.11 consensus, even as revenue of $1.51 billion beat expectations by 2.7%. Earnings grew 3.1% year over year and revenue rose 4.1%. On a GAAP basis, EPS was flat at $1.94. The headline is a miss, but management narrowed 2026 adjusted EPS guidance to the top half of its prior range, at $6.07 to $6.12, and introduced standalone 2027 guidance of $6.53 to $6.63, implying 8% growth at the midpoint. That is the central tension. The quarter fell short of Street modeling, while the forward framework improved modestly.
The quality of the miss deserves scrutiny, because most of it was not operational. Revenue growth came as designed: new rates from completed rate cases and infrastructure surcharges, plus acquisition revenue, more than offset an $18 million weather hit to revenue. Regulated Businesses net income rose to $407 million from $383 million. The drag sat below operating income. Interest income collapsed to $3 million from $23 million after the Homeowner Services seller note was retired; that note had carried $795 million at year-end. Over the same period, interest expense rose $9 million, depreciation rose about $19 million, and diluted shares climbed to 199 million from 195 million as equity funding flowed in. Adjusted EPS strips out weather and merger transaction costs, but the loss of the base interest income is a real earnings headwind. Third-quarter growth of 3.1% sits well below the 7-9% long-term target, which leaves a lot riding on rate relief and capital deployment.
The call did more to reinforce the multi-year growth story than to defend the quarter. Regulatory outcomes were constructive. New Jersey granted a $68 million increase at a 9.5% ROE and 54% equity, following Pennsylvania's $75 million at 9.55% last quarter. AWK has secured $284 million in annualized revenue this year, with another $360 million requested in pending cases. Management lifted the five-year capital plan to more than $20 billion through 2030, up from $19-20 billion, and set a 10-year plan above $48 billion, driven by aging pipe replacement and PFAS work. About 81,000 customer connections were added year to date across 10 states, so the 2% acquired-customer growth target has already been met. Equity needs were left unchanged, and management reaffirmed the 7-9% EPS and dividend growth targets with or without the Essential deal.
Merger progress was the other major development. The deal now has approvals in three states, settlements in Pennsylvania, Texas and North Carolina, an expired HSR waiting period and a favorable Illinois ALJ recommendation. Management reiterated a close by the end of the first quarter of 2027. Bears still have legitimate ammunition, though:
- **Merger visibility:** Combined-company guidance and accretion detail were deferred until after close, and questions about Essential skipping a water rate filing went unanswered.
- **Monterey desalination:** The project's cost estimate rose to $825 million plus AFUDC amid legal challenges, and it remains subject to CPUC approval.
- **Illinois rate case:** The ALJ proposed $67 million against a $104 million updated request.
- **Financing costs:** The latest debt priced at 5.55%, compared with 4.625% in May.
- **Operating costs:** O&M ticked up modestly after a flat second quarter.
- **Acquisition pipeline:** Connections under agreement shrank to roughly 36,000, down from 57,000 last quarter and 105,000 in the first quarter. That decline is mostly from closings such as Nexus, but it also means a thinner acquisition backlog.
- **Affordability:** National scrutiny of utility affordability remains a constant backdrop for a company asking for ever-larger rate increases.
Investor sentiment remained negative but improved, rising to -0.40 from -0.49 at the prior report. That is a meaningful but not dramatic thaw. The stock has gone essentially nowhere, at $139.79, down 0.2% from the $140.00 open after July's report. However, it sits about 5.7% above its 200-day moving average, and the Earnings Whispers price and AVWAP trend readings are positive. That suggests the market has been holding the shares steady rather than repricing them on short-term misses. A utility trading on rate-base visibility tends to be judged more on guidance and regulatory outcomes than on a single quarter's EPS print.
The bottom line is that American Water's third-quarter miss reflects financing-side headwinds, mainly vanished seller-note interest income, rising debt costs and share dilution, rather than any break in the regulated growth engine. The top-half 2026 guide, the 8% 2027 outlook, the larger capital plan and steady merger approvals give the long-term thesis more support than the consensus miss suggests. Still, slow near-term EPS growth, Monterey cost escalation and the opacity around Essential accretion mean execution on the 2027 targets carries more weight than usual.
Read our earnings preview for American Water Works Company, Inc.: https://www.earningswhispers.com/article/AWK/20905
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 |
