ICE Clears Consensus But Misses The Whisper As Volatility-Driven Trading Masks A Softer Recurring And Mortgage Story
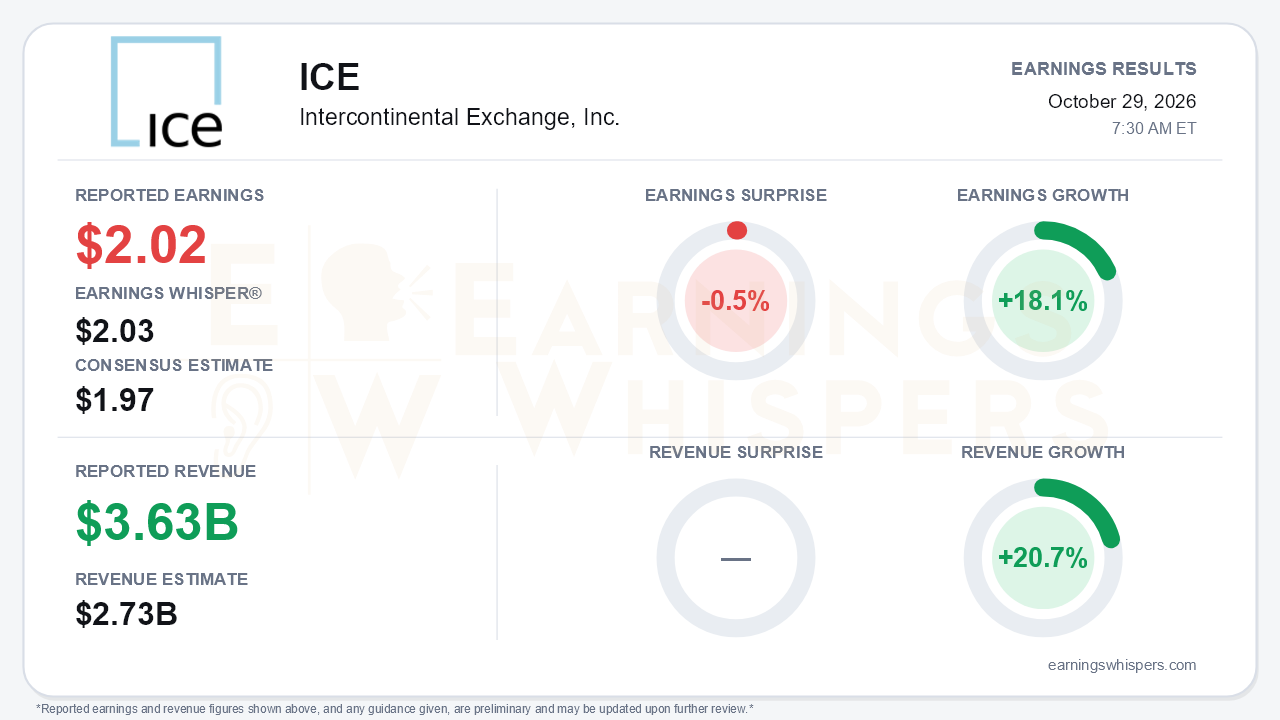
Intercontinental Exchange delivered what management called the best third quarter in its history, yet it still fell a penny short of the bar that mattered. Adjusted EPS of $2.02 rose 18.1% year over year and topped the $1.97 consensus, but it missed the $2.03 Earnings Whisper number by 0.5%. The headline revenue comparison needs context. Earnings Whispers shows revenue of $3.63 billion, up 20.7%, and a 33.0% beat against a $2.73 billion consensus. That surprise reflects a gross-versus-net mismatch. The $3.63 billion is total revenue before transaction-based expenses. ICE's own headline figure, net revenue of $2.77 billion, rose 15% and landed only modestly above the consensus figure. Even so, growth clearly reaccelerated. The call analysis puts the comparison at roughly 5% revenue growth and $1.90 of EPS in Q2, though the quarter did not match Q1's $2.35 spike.
The quality of the beat deserves scrutiny because nearly all of the acceleration came from trading activity. Net transaction revenue jumped 23%, while recurring revenue grew only 7%, down from 8% in Q2. The exchanges segment drove the quarter with 22% growth:
- Energy rose 25%.
- Financials climbed 37%.
- Ags and metals surged 62%.
- Futures and options volume grew 31%, and rates volume was up 49%.
Adjusted operating margin expanded to 61% from 59%, and GAAP EPS of $1.67 also rose 18%. Below the operating line, there were some headwinds:
- Interest expense rose to $222 million.
- Other income fell to $11 million from $71 million.
- MarketAxess-related transaction costs of $28 million pushed fixed income and data services' GAAP margin down to 36% from 39%.
The call preserved a credible growth story for the recurring franchises even as the mix shifted toward transactions. Management lifted 2026 exchange recurring revenue growth to about 9%, the top of the high-single-digit range set in Q2 and well above the mid-single-digit outlook from the start of the year. Fixed income and data services recurring growth moved to about 8%, the top of a 7-8% range that management had previously suggested would trend toward the low end. Black Knight synergies are tracking toward a roughly $270 million annualized exit rate. Leverage improved to 2.65x, and Q4-to-date volume is running up 13%.
Mortgage technology is where bears have legitimate ammunition. The segment grew just 4%, versus 5-6% in the first half. Its transaction growth slowed to 4%, down from 22% in Q1 and 11% in Q2. Adjusted margin slipped to 40% from 42%. Management guided Q4 mortgage transaction revenue lower both sequentially and year over year as rates rose late in the quarter, and it deflected on 2027 growth. An analyst openly questioned whether ICE should keep the business at all. Wells Fargo's MSP renewal and five new MSP clients this year are wins, but they are not yet offsetting the rate-driven drag.
Costs and capital spending also moved the wrong way. Full-year operating expenses are now expected at the top of the prior range. The release guides Q4 adjusted operating expenses to $1.082-1.092 billion and GAAP expenses to $1.317-1.327 billion, figures that differ from the higher Q4 range cited in the call summary. Capex was raised to roughly $1.05 billion in the release, largely for an Atlanta campus purchase, though the call summary cites a higher figure near $1.5 billion. Either way, the capex outlook is materially above earlier expectations. On the catalyst side, the list is long:
- HSR early termination pulled the MarketAxess close forward to Q1 2027.
- ICE made a strategic investment in TradeXYZ, under which ICE would operate regulated real-world-asset perpetual markets on Hyperliquid.
- GPU compute futures, private credit identifiers anchored by Apollo, and NYSE 23x5 trading launching in December extend the product pipeline.
Several of these initiatives hinge on CFTC approval or face regulatory uncertainty.
The market setup is more complicated than the surprise implies. Investor sentiment slid from roughly neutral (-0.04) to clearly negative (-0.34) heading into the report, a meaningful deterioration. Shares are essentially flat since the prior report, up 0.6%. They sit just 0.9% above the 200-day moving average and 5.3% below the October 23 inter-earnings high of $164.69. Price and momentum trend readings are positive while AVWAP remains negative, consistent with a stock that rallied into earnings but has not built durable gains.
The bottom line is that ICE produced a strong, volatility-fueled quarter and raised its recurring growth outlook, but the beat leaned on transaction revenue that can fade. Meanwhile, mortgage softness, a higher cost run rate, and heavier capex give skeptics specific concerns. Missing the whisper by a penny matters less than whether exchange recurring momentum and MarketAxess can carry growth once trading volumes normalize.
Read our earnings preview for Intercontinental Exchange, Inc.: https://www.earningswhispers.com/article/ICE/21085
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour |
NYSE Owner Plans to Bring Hyperliquid-Based Perpetual Futures to U.S.
ICE +5.89%
The Wall Street Journal
|
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 |
