Mastercard Accelerates To 14% Revenue Growth, But Q4 Timing Payback And Slowing Cross-Border Temper An Unchanged Outlook
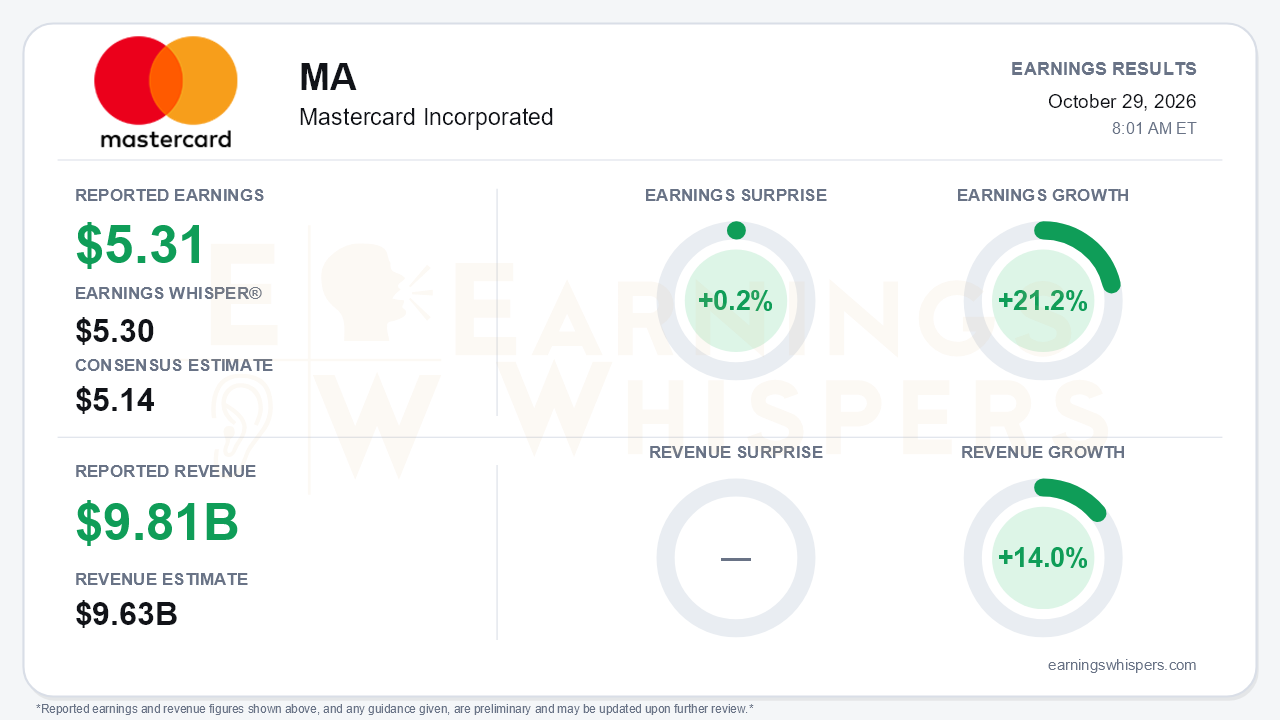
Mastercard delivered the cleanest acceleration it has shown all year, but the quarter's quality is more nuanced than the headline suggests. The company earned $5.31 per share on revenue of $9.807 billion for the September quarter. That was well ahead of the $5.14 consensus, though only 0.2% above the $5.30 Earnings Whisper number. Revenue topped the $9.63 billion consensus by 1.8%. Earnings grew 21.2% year over year and revenue rose 14.0%. That marks a step up from 12% revenue growth in each of the first two quarters and beats management's own guide of the high end of low double digits. The central tension is that the acceleration was real but partly borrowed. Management did not let it flow through to a higher full-year outlook.
The composition of the beat matters. Payment network revenue growth jumped to 11% from 8% in each of the prior two quarters. Value-added services edged up to 19% from 18%. Domestic assessments did much of the heavy lifting, climbing 13% versus 10% in the second quarter and just 6% in the first, helped by pricing and mix. Operating expenses grew 12%, slower than revenue, so operating income rose 15% versus 14% last quarter and EPS growth improved for a third straight quarter. The quality of the beat still deserves scrutiny. New CFO Ling Hai, on her first call, said some third-quarter upside came from services projects and deal signings pulled forward from the fourth quarter. She said that benefit will reverse.
Beneath the improving top line, the volume picture is softening. Cross-border volume growth has slowed four quarters in a row: 14% in Q4 FY25, then 13%, 12%, and now 11%. Cross-border assessments decelerated sharply to 16% from 20%. Card-not-present cross-border spending excluding travel slowed from 20% to 15%. Management blamed the new EU customs fee, promotional timing, and difficult comparisons against last year's crypto purchases. Worldwide gross dollar volume growth eased to 7% from 8%, and non-US credit slowed to 6% from 9%. In short, recent revenue strength leaned more on pricing and services than on underlying volume. That is a less durable mix as pricing begins to lap in the fourth quarter.
The forward guidance reflects that caution. Full-year net revenue growth remains at the high end of low double digits, the same range given at the start of the year. Management kept, but did not upgrade, last quarter's 'higher within range' language. Fourth-quarter revenue growth is guided to the high end of low double digits, below the 14% just reported. Several fourth-quarter headwinds are stacking up:
- the timing payback from services and deal signings;
- higher rebates and incentives as a share of gross assessments;
- roughly a 1-point foreign-exchange headwind from a stronger dollar, versus a full-year tailwind of about 1 point;
- fourth-quarter opex now tracking to the high end of low double digits.
Buybacks also slowed to $3.0 billion from $4.9 billion in the second quarter. Additional risks include elevated geopolitical and energy-price uncertainty, possible UPI fee changes in India, and friction from Mastercard's stance against virtual-card-based agentic payment flows.
The catalyst list, by contrast, expanded meaningfully. The BVNK acquisition closed in August and produced the Global Money Platform, with Nuvei and Marqeta as early customers. The OpenAI relationship broadened into a strategic partnership covering Agent Pay and joint services, and Shopify's Shop Pay is adopting Agent Pay and network tokens. Customer wins included a full portfolio migration from Pinnacle Financial Partners starting in 2027, an HDFC small-business deal of roughly 3 million cards, and Bank of China debit. Mastercard also secured key Nordic and German renewals. The call preserved a credible long-term growth story, and US switched volume was improving into October as the Capital One debit comparison laps.
Investor expectations had already shifted ahead of the print. Earnings Whispers sentiment improved substantially, from -0.27 at the prior report to roughly neutral at +0.02. Shares were up 5.7% since the open following the July report and about 14% above the 200-day moving average. However, the path was volatile. The stock fell to a quarterly low of $545.41 on October 2, then rallied to a 52-week high of $633.29 on October 22. It entered the report 3.6% below that peak. The Earnings Whispers trend signals are uniformly positive, consistent with that late-quarter momentum. Still, a run-up of that size raised the bar, and a result that only fractionally beat the whisper number does not clear it by much.
The bottom line is that Mastercard's third quarter showed genuine acceleration in revenue, earnings, and operating leverage, alongside a richer pipeline of agentic-commerce and stablecoin-related catalysts. Yet bears have legitimate ammunition. Cross-border growth keeps slowing, part of the upside came from fourth-quarter timing, and guidance was reaffirmed rather than raised. With sentiment repaired and shares near their highs, the fourth-quarter deceleration management has already flagged will be the next test.
Read our earnings preview for Mastercard Incorporated: https://www.earningswhispers.com/article/MA/21101
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 7 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 10 hours | |
| 10 hours | |
| 17 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 |
