Eli Lilly Clears Consensus But Misses The Whisper As A $4.57 IPR&D Charge Masks A Third Straight Guidance Raise
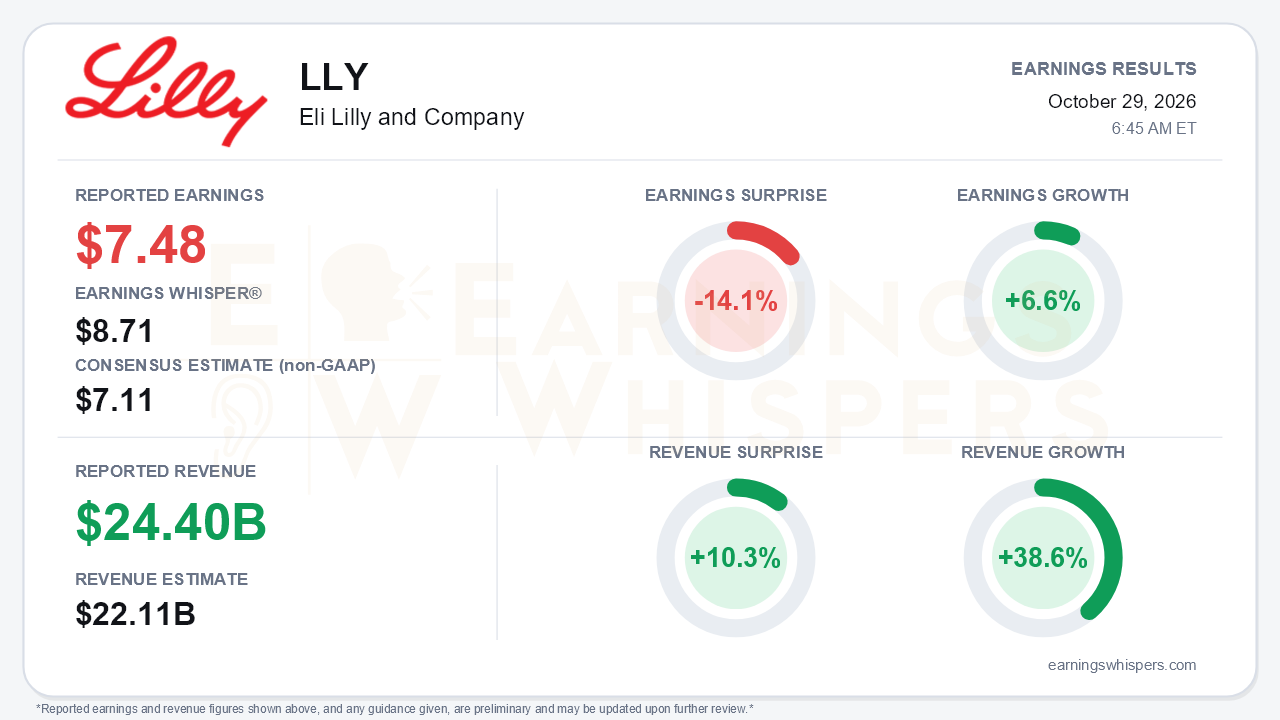
Eli Lilly's third quarter splits into two stories. Non-GAAP EPS of $7.48 topped the $7.11 consensus but fell 14.1% short of the $8.71 Earnings Whisper number. Earnings grew only 6.6% year over year. Revenue told a cleaner story: $24.4 billion beat the $22.11 billion consensus by 10.3% and grew 38.6%. The gap between the top and bottom lines comes almost entirely from business development. Lilly includes acquired IPR&D in its non-GAAP figures, and that charge rose to $4.57 per share, mostly from the AtaiBeckley and Curevo deals, compared with $0.71 a year ago. Investors who look through the deal accounting saw an operating quarter strong enough to drive the largest guidance raise of the year. Those focused on the printed number saw a miss against elevated expectations.
The quality of the revenue beat still deserves scrutiny. Q3 included roughly $900 million of favorable items, including a $410 million Jardiance sales-based milestone, the last one remaining, plus favorable rebate and discount adjustments. Management indicated that about $2 billion of such benefits in 2026 will not recur in 2027. Growth also continues to decelerate, with reported revenue growth slowing from 56% in Q1 to 48% in Q2 and 39% now. Pricing is the clearest crack. Volume rose 53%, but realized prices fell 15% worldwide. U.S. prices fell 7% on a reported basis versus 3% in Q2, and roughly 10% excluding adjustments versus 9% in the prior quarter. Outside the U.S., prices fell 29%, largely because Mounjaro joined China's reimbursement list. Non-GAAP gross margin of 84.4% was up 0.8 points from last year but down from 86.3% in Q2, and quarterly performance margin eased to 54.2% from 54.8%.
The demand picture, however, is improving rather than fading:
- **Incretin franchise:** Mounjaro grew 65% to $10.7 billion, and Zepbound grew 49% to $5.4 billion. Combined quarterly incretin revenue moved from $12.8 billion in Q1 to $14.9 billion in Q2 to more than $16 billion.
- **U.S. obesity scripts:** Total prescriptions for U.S. obesity incretins grew 82%, faster than Q2's 78%.
- **Medicare GLP-1 Bridge:** More than 500,000 patients have filled prescriptions since July 1. Seven of 10 new Bridge patients start on a Lilly drug, and about 80% are new to incretins, up from 60-70% in Q2. That suggests the program is expanding the market rather than shuffling existing patients.
- **International:** Lilly's incretin share rose to about 58% from 55%, and Mounjaro in China passed $1 billion in its first full year.
- **Foundayo:** The oral obesity drug captured roughly 40% of new oral obesity patients, up from about a quarter in Q2, and launched in four ex-U.S. markets.
- **Beyond obesity:** Key products in oncology, immunology and neuroscience doubled, led by Kisunla's 175% gain.
Guidance is where the quarter changed the setup most. Lilly raised its 2026 revenue range to $91-92 billion from $85-87 billion, the third increase this year, and roughly $10 billion above where the year began. Performance-margin guidance rose to 52-52.5% from 49-50.5%. Underlying EPS guidance increased by $4.07 at the midpoint, but the Q3 IPR&D charge more than offsets that, so the reported EPS range edges down to $35-36. The tax-rate assumption also moved up a point to 19-20%. The pipeline added depth:
- Retatrutide delivered 20-21% weight loss versus 9.4% for Ozempic 2 mg in a head-to-head type 2 diabetes trial.
- EloraTZP's Phase 2 showed 23.3% weight loss, with Phase 3 trials starting this quarter.
- The FDA approved Onswik, Inluriyo with Verzenio, first-line Jaypirca, and Mounjaro's cardiovascular indication.
Bears still have legitimate ammunition. The Bridge program runs only through December 2027, and its continuity depends on Part D integration or policy action. Some employers are opting out of GLP-1 coverage, and management expects commercial access only to hold stable in 2027. The 2027 mix shifts toward lower-net-price Medicare, Medicaid and self-pay channels. EloraTZP showed higher discontinuations due to adverse events at its top dose. International president Patrik Jonsson's retirement also consolidates leadership under Ilya Yuffa.
The market had already priced in much of the strength. Shares rose 9.7% from the open after the August report to $1,288.30. That leaves them 18.4% above the 200-day moving average and just 2.5% below a 52-week high of $1,321.21 set on October 22, within the inter-earnings period. Investor sentiment remained negative but improved meaningfully, from -0.38 to -0.15. The Earnings Whispers trend signals for price, sequential growth and momentum are mostly positive. A stock near its highs, with expectations high enough to produce a lofty Whisper number, leaves less room for a headline miss.
The bottom line is that Lilly's operating engine accelerated in the ways that matter most: volume, share, Medicare uptake, oral launch traction and full-year margin guidance. A deal-related IPR&D charge and roughly $900 million of non-recurring benefits distort the quarterly print in opposite directions. The real debate is 2027, when price erosion, the absence of one-time items, and the Bridge program's expiration test whether volume growth can keep outrunning pricing pressure.
Read our earnings preview for Eli Lilly and Company: https://www.earningswhispers.com/article/LLY/21098
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours |
