TeraWulf Must Prove Its HPC Ramp Can Outrun Rising Costs And Slipping Timelines
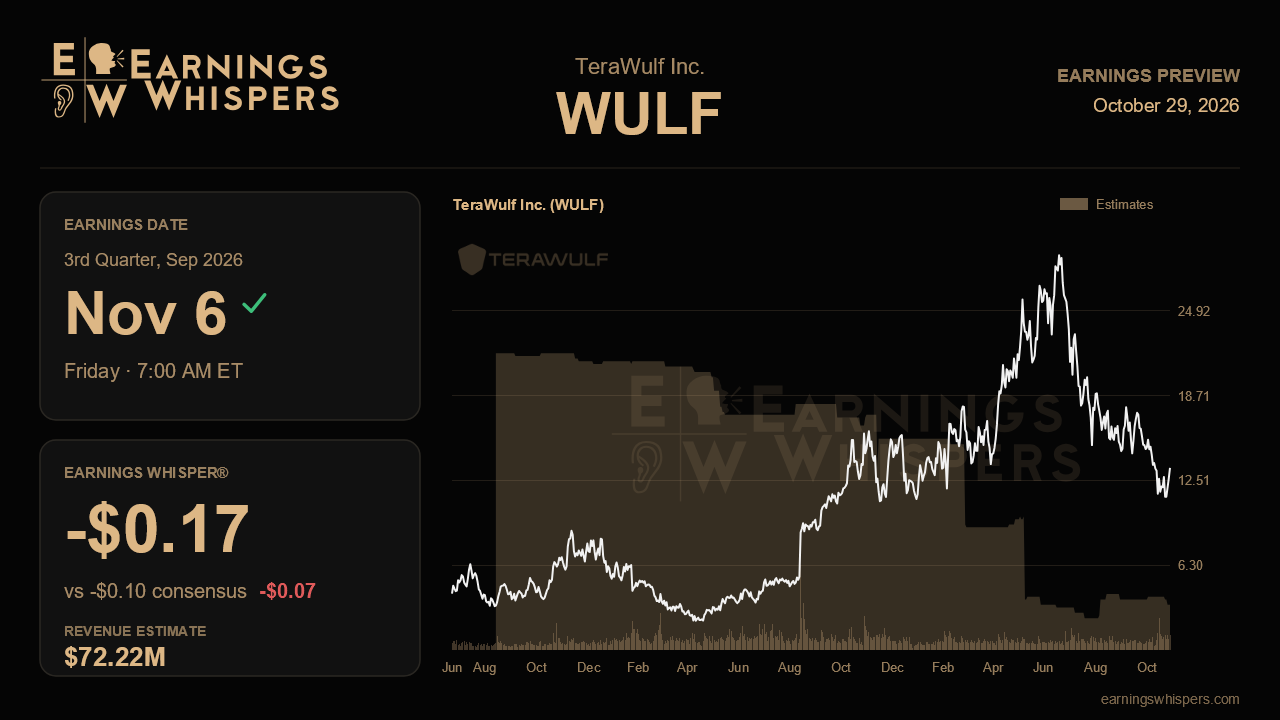
TeraWulf heads into its September-quarter report with a striking disconnect. Management spent the last call describing the busiest pipeline in company history, a roughly $19 billion, 20-year lease with Anthropic, and a gigawatt-scale campus in Kentucky. Yet the stock has fallen 27.5% since then while the S&P 500 barely moved. The report, due before the open on November 6, needs to show that the contracts signed on paper are turning into revenue and margin fast enough to justify the capital being poured into them.
The Street is looking for revenue of about $72.2 million, up 42.8% from a year ago and roughly 61% above the $44.8 million posted last quarter. That sequential jump is the real test. It assumes the 102 megawatts of critical IT capacity running at Lake Mariner as the quarter began, including the fully energized CB3 building, contributed for the full period. Consensus calls for a loss of $0.10 per share, worse than the $0.07 loss a year earlier. The whisper number of a $0.17 loss sits noticeably below consensus, suggesting traders expect heavier development spending to weigh on the bottom line. That lowers the bar on earnings, but it also signals skepticism that the revenue ramp will translate into profit this quarter. Management offered no formal financial guidance, so contract delivery milestones serve as the practical yardsticks.
The first milestone is CB4. On the prior call, management pushed its delivery to late September and CB5 to very early January, a modest slip from earlier framing of the third and fourth quarters of 2026. Because CB4 was scheduled to arrive at the tail end of the quarter, it should add little to reported revenue, but confirmation that it was handed over on time would matter far more than its contribution to the quarter. Another delay, particularly if tied again to evolving customer hardware requirements, would raise questions about whether the January date for CB5 is realistic and whether the Anthropic buildout at Hawesville faces similar friction.
Margins are the second issue. Reported HPC segment margin fell to roughly 28% last quarter from about 50% the quarter before, against a long-term target near 85%, and adjusted EBITDA deepened to a loss of $18.3 million as pre-revenue costs piled up. Management framed this as a temporary byproduct of building ahead of revenue. Evidence of validation would be margin recovery as CB3 runs at full capacity and a narrower EBITDA loss. A further deterioration would suggest that cost pressures are structural. Related to that, build costs climbed to about $9.1 million per critical megawatt, driven by tight electrical labor and rising hourly rates as the company scales toward roughly 1,000 electricians. Any additional upward drift, even within the $8 million to $10 million range management has cited, would erode the returns underpinning these long-term leases.
There is also the matter of GAAP noise. Last quarter's $939.9 million net loss was dominated by a $755.7 million non-cash mark on the Google warrant, so headline EPS could again swing widely on items unrelated to operations. On the commercial side, the annual signing target of 250 to 500 megawatts has been reaffirmed rather than raised for several quarters. With the Anthropic deal already in hand, an update on the Northern Europe site or progress at Muskie would show whether the pipeline is broadening.
Sentiment has soured, with the bearish reading deepening from the prior quarter. At $13.42, shares sit well below the 200-day moving average of $18.08 and in the lower half of the post-earnings range of $10.35 to $19.44, a sharp step down from the prior quarter's $14.81 to $29.84 band. That leaves room for relief if execution looks clean. Ultimately the report will turn on one question: can TeraWulf deliver capacity on schedule while showing that margins rebound as buildings come online, or are rising costs and shifting timelines becoming the defining feature of its transition?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-25 | |
| Oct-24 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 |
