Vistra's Third Quarter Must Show Whether Softer ERCOT Prices Threaten Its 2027 Outlook
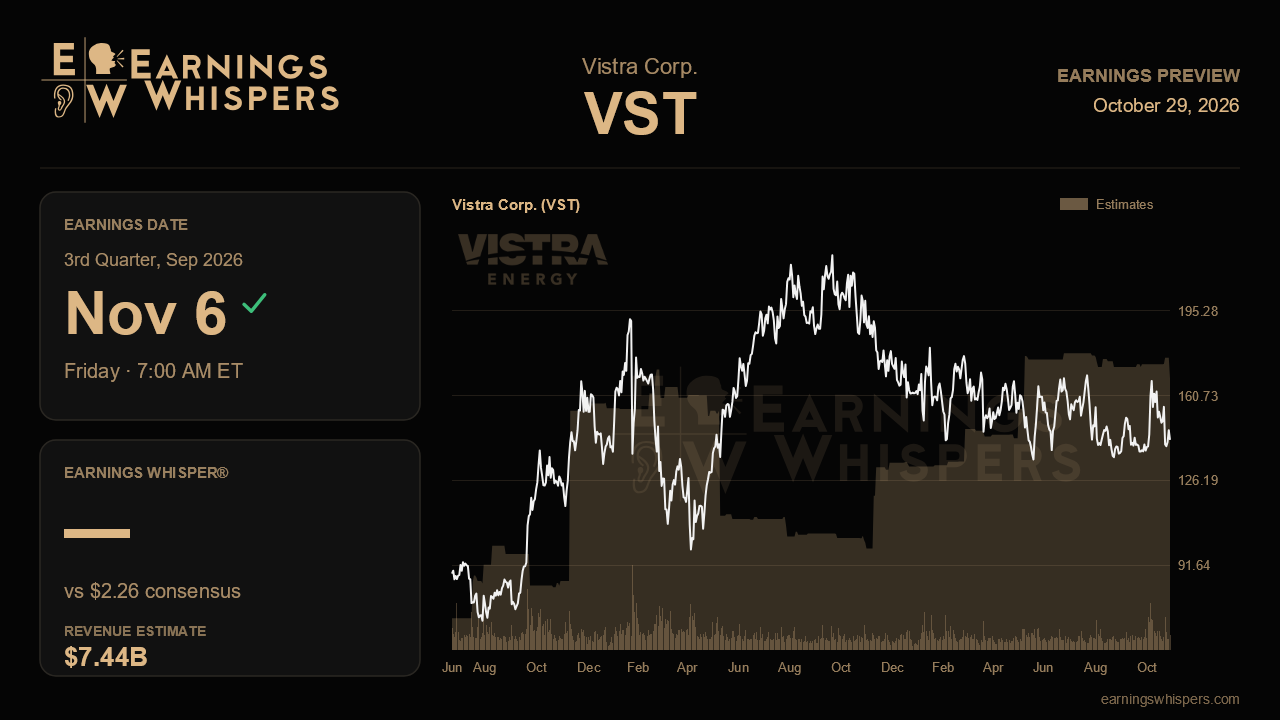
Vistra heads into its third-quarter report with an odd split personality. The 2026 story looks about as solid as a power producer's can be, with management promising last quarter to land at or above the midpoint of its earnings range. Yet the stock trades well below its 200-day moving average, and sentiment has turned from mildly bullish to mildly bearish. The reason sits a year out. Lower Texas power forward prices pushed management's 2027 view toward the bottom of its range, and the market now wants to know whether that slippage has stopped.
The near-term bar is demanding. Analysts expect earnings of $2.26 a share, up about 29% from $1.75 a year ago, on revenue of roughly $7.44 billion, nearly 50% above last year's $4.97 billion. That revenue leap is large for a company whose realized prices rose only about 5% last quarter, so the release should make clear how much comes from operations and how much reflects hedging swings or a changed asset base. The third quarter usually carries the summer, which makes it an important contributor to the full-year total. Management reaffirmed 2026 adjusted EBITDA of $6.8 billion to $7.6 billion, and its stated confidence in reaching at least the $7.2 billion midpoint means that a simple reaffirmation would now read as a mild letdown. Narrowing the range toward the upper half would confirm the second-quarter message.
The bigger question is 2027. For three straight quarters Vistra had reaffirmed a midpoint opportunity of $7.4 billion to $7.8 billion, then last quarter guided toward the low end as ERCOT forwards weakened. Higher PJM prices, existing hedges and the nuclear production tax credit only partly cushioned the blow. Texas wholesale prices have been stuck near $30 per megawatt-hour, held down by a glut of batteries and mild weather. If forwards slid further over the summer, the low end could start to look optimistic. If they firmed, the 2027 cut may prove to have been conservative. Management also deferred updating guidance for the Cogentrix acquisition and the Meta power agreement, which together would add about $700 million to the 2027 midpoint once closed. Progress toward closing, or a formal guidance update, could offset most of the ERCOT damage in one step.
The longer-term data center thesis needs evidence that it is turning into contracts. Management raised its structural load growth view to at least 4% to 6% a year and introduced Helix, a data center platform backed by KKR, the University of Pennsylvania and the Kuwait Investment Authority, in which Vistra committed up to $1 billion. A first project, a customer or a clear milestone would show Helix is more than a press release. FERC's June co-location order largely adopted Vistra's positions, and PJM compliance filings were expected within 30 to 60 days, so an update on how those rules shape actual deals matters. In Texas, the governor's directive pausing load interconnection reviews was described as lasting a couple of months. Confirmation that Comanche Peak's baseload projects remain on track would remove a lingering worry.
The stock is up about 3% since the last report, slightly ahead of the S&P 500, but at $142.72 it sits in the lower part of its post-earnings range of $133.44 to $168.75. That leaves room for relief if the 2027 picture stabilizes. With roughly $2 billion left on the buyback authorization and more than $6.5 billion already returned, capital return remains a support, though weaker Texas economics could temper its pace.
The third-quarter beat matters less than what management says about 2027. If Vistra can show that the ERCOT headwind has stopped worsening while Cogentrix, Meta and Helix move closer to contributing earnings, the growth story holds. Another step down in the 2027 outlook would suggest that Texas pricing, not data center demand, is setting the pace for earnings.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 5 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 |
Multinationals fall behind on ECCTA identity verification, survey finds
VST -9.81%
International Accounting Bulletin
|
| Oct-22 |
ECCTAs progress report warnings for overseas businesses
VST -9.81%
International Accounting Bulletin
|
| Oct-21 | |
| Oct-18 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 |
