Cheniere Misses On EPS But Raises Guidance For A Third Straight Quarter As Contracts Extend Visibility
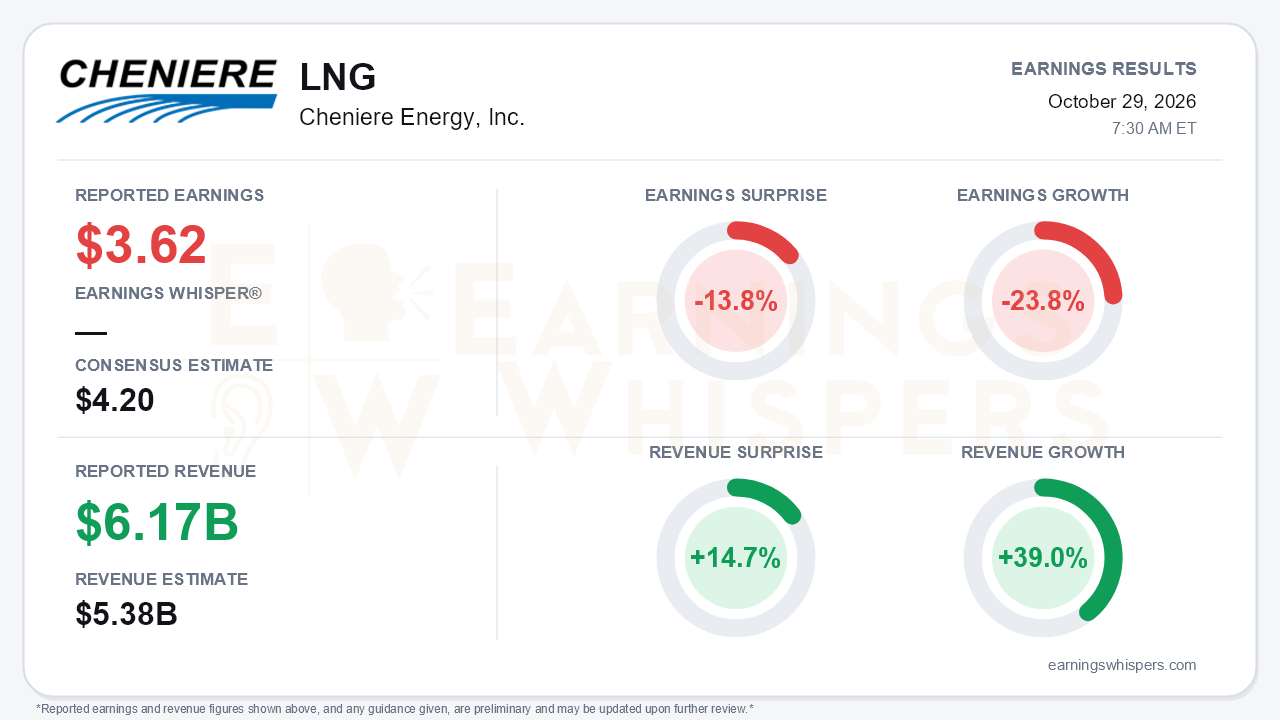
Cheniere Energy delivered a quarter where the headline miss and the forward story point in opposite directions. Third-quarter earnings of $3.62 per share fell 13.8% short of the $4.20 consensus and were down 23.8% year over year. Revenue of $6.173 billion beat the $5.38 billion consensus by 14.7% and rose 39.0%. Management also raised full-year 2026 guidance for the third consecutive quarter, lifting Consolidated Adjusted EBITDA to $8.75-$9.25 billion from $7.90-$8.40 billion and Distributable Cash Flow to $6.05-$6.55 billion from $5.30-$5.80 billion. The EBITDA midpoint is now about $2 billion above the initial February outlook. That gap between a disappointing quarter and a much stronger full-year outlook is the central tension.
The quality of the quarter deserves careful reading. GAAP diluted EPS was $5.65 because results included roughly $432 million of non-cash derivative gains, mostly tied to the long-term IPM agreements. The $3.62 figure lines up with Cheniere's Adjusted Net Income of $750 million, which strips out those gains.
The normalized comparison also needs context. Cheniere's own adjusted net income rose from $591 million a year ago, so the 23.8% year-over-year EPS decline reflects the normalized comparison base rather than a collapse in the company's adjusted profitability.
The revenue beat did not flow through proportionally. Cost of sales jumped to $3.21 billion from $1.75 billion, and Consolidated Adjusted EBITDA rose a more modest 18% to $1.90 billion. Sequentially, EBITDA stayed below the first quarter's roughly $2.3 billion, and DCF of about $1.2 billion was flat with the second quarter. Management attributed this to seasonality and cargo timing, with 61 TBtu of delivered-basis LNG still in transit at quarter-end.
Operationally, the business kept getting bigger. Exports reached a record 188 cargoes and 684 TBtu, up 17% by volume from a year ago. Daily production hit a record of more than 8.33 TBtu. The seventh and final midscale train of Corpus Christi Stage 3 reached substantial completion ahead of schedule and within budget, expanding production capacity by over 20%.
Management introduced a 2027 production forecast of 56-58 million tonnes, compared with 53-54 MT in 2026. About 52 MT of that is contracted long-term and only about 1 MT remains unsold, and roughly 4 MT has already been forward-sold at around $10 margins. Management described 2027 as "not too far off" 2026, which addresses the obvious worry that this year's windfall is a peak.
Bears do have legitimate ammunition on the guidance itself. By the call's own breakdown, the third-quarter raise came from four sources:
- about $250 million from netbacks climbing from above $10 to above $20;
- another $250 million from three cargoes shifting into December;
- about $150 million from optimization;
- roughly $100 million from the early Train 7 completion.
Much of that is timing or market-driven and may not recur. The 2026 production range was left unchanged at 53-54 MT. Management also flagged several sources of volatility:
- deteriorating security in the Strait of Hormuz, including attacks on LNG carriers;
- European storage at roughly 72% entering October, the lowest since 2011;
- a second year of declining Chinese imports;
- price swings large enough that a single cargo can move EBITDA by about $100 million.
The longer-dated catalysts are more durable. New SPAs with QatarEnergy (up to 4 mtpa through 2054) and Petrobras (0.8 mtpa for 22 years) add roughly $15 billion of fixed fees. Management said they commercially support the first phase of the Corpus Christi expansion. The SPL Expansion Project received its FERC final EIS and $3.25 billion of term-loan commitments, with FID now targeted around year-end rather than early 2027.
Capital returns are accelerating alongside the growth plans. The dividend rose more than 12% to $0.625, and Cheniere repurchased $731 million of stock in the quarter. Management signaled a likely buyback upsize after the SPL FID. S&P's upgrade of Corpus Christi Holdings to A- adds balance-sheet credibility to that expansion program.
The market setup is more complicated than the miss implies. Shares entered the report at $297.77, up 11.3% since the post-August open and 16.8% above the 200-day moving average. They sat just 2.3% below the 52-week high of $304.73 set on October 27. Investor sentiment moved the other way, sliding from a moderately positive 0.2465 to -0.1025, a meaningful shift into mildly negative territory despite the rally. Earnings Whispers trend signals were mostly positive, though sequential growth was only neutral, consistent with the soft quarter-over-quarter EBITDA.
The bottom line is that Cheniere's EPS miss reflects quarterly timing and a high bar more than any deterioration in the franchise. Volumes, contracting, project execution and guidance all moved in the right direction. The caveat is that part of the 2026 upside is non-recurring, and the stock came into the print near its highs with sentiment already cooling. That leaves less room for error if winter volatility or cargo timing turns against the company.
Read our earnings preview for Cheniere Energy, Inc.: https://www.earningswhispers.com/article/LNG/21099
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 11 hours | |
| 11 hours | |
| 11 hours | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-05 | |
| Oct-01 | |
| Sep-29 | |
| Sep-24 | |
| Sep-10 | |
| Sep-08 | |
| Sep-04 |
