Starbucks Tops EPS Estimates As Margins Hit FY28 Targets Early, But Shrinking Revenue And Ticket-Led Comps Complicate The Story
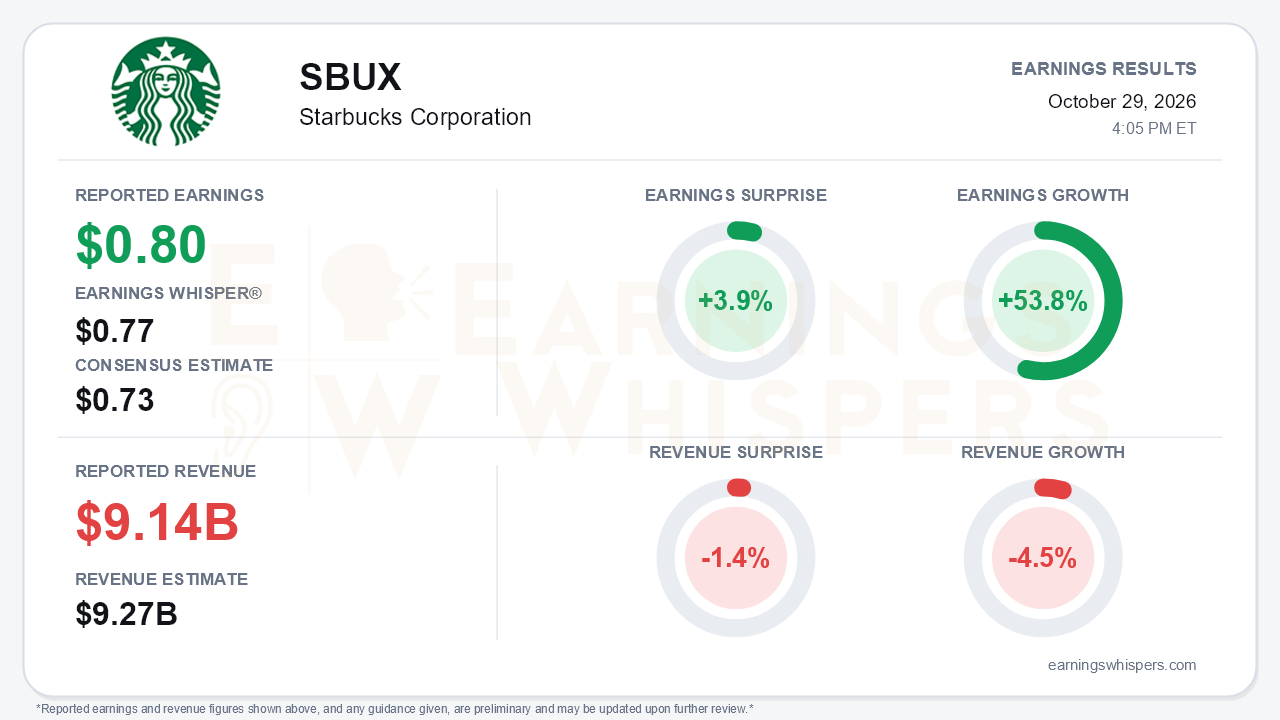
Starbucks delivered the quarter its turnaround needed on profitability. Non-GAAP earnings of $0.80 per share beat the $0.73 consensus and the $0.77 Earnings Whisper number, a 3.9% upside surprise, and rose 53.8% year over year. Revenue was the weak spot: $9.141 billion fell 4.5% and missed the $9.27 billion consensus by 1.4%. That split defines the quarter. Starbucks is becoming a smaller, more profitable company. Management's guidance says that trend continues into fiscal 2027. The open question is whether the comp engine powering it is starting to downshift.
The quality of the beat holds up better than a 392% GAAP EPS jump might suggest, though that GAAP figure needs context. GAAP operating margin expanded 790 basis points to 10.8%, but much of that came from restructuring charges falling to $272.8 million from $755 million. The cleaner measure is non-GAAP operating margin, which rose 450 basis points in constant currency to 14.0%. That expansion was real operating leverage:
- Coffeehouse operating expenses fell to 54.3% of company-operated revenue from 55.1%. In North America the ratio dropped to 54.0% from 56.2%.
- G&A fell 19%.
- Management put North America's non-GAAP margin at roughly 16%.
The headwinds were below the operating line. The non-GAAP tax rate rose 100 basis points to 24.7%, and the prior-year quarter had benefited from a $145 million litigation settlement that is excluded from non-GAAP results. The revenue decline itself is largely structural. International revenue fell 37% after China retail converted to a licensed joint venture, even though International operating income rose 15% and segment margin nearly doubled to 19.7%.
The call explains why management now calls "Back to Starbucks" a growth plan rather than a turnaround. The fiscal 2026 EPS outlook rose in three successive steps to $2.55-$2.65, and the company still finished above it at $2.72. Global comps climbed from 4% in Q1 to 7.9% in Q3. More than 80% of North American company stores posted positive comps, versus fewer than half a year ago.
The composition of that growth is shifting, though:
- Q4 global comps slipped to 7.2%.
- U.S. transaction growth slowed to 2.4% from 4.2% in Q3, so the 7.7% U.S. comp relied on a 5.2% ticket increase driven by mix, food attach, pricing and delivery.
- Management said fiscal 2027 comps will lean more on ticket.
- International company-operated comps fell to 0.9% from 5.7%, with transactions down 2.8%.
- Channel Development swung from +22% growth in Q3 to an 8.9% decline as coffee-price tailwinds reversed. It is guided down about 10% next year.
This is still decelerating growth from a high level, not a collapse, but bears have legitimate ammunition.
The fiscal 2027 outlook is where management made its strongest case:
- Non-GAAP EPS of $3.15-$3.25, about 18% growth including slightly more than a dime from the 53rd week.
- North America comps of about 4%, above the 3%-plus long-term algorithm.
- Non-GAAP operating margin of 13.5%-14.0%, which reaches the low end of the fiscal 2028 framework a year early.
- Roughly $1 billion of share repurchases, alongside the dividend raised to $0.63.
Catalysts include in-app delivery with Rewards integration in fiscal Q2, more than 2,000 store uplifts, AI drive-thru tests, and a matcha platform now above $1 billion.
The offsets are tangible. Consolidated revenue is guided down about 1% even with roughly $700 million from the extra week, which falls below Street estimates. North America will add only 90-100 net new units after 250 more closures. Management also called fiscal 2027 a heavy tech-modernization year, with POS and scheduling changes that carry execution risk.
Investors were not leaning hard into the print. Earnings Whispers sentiment cooled from 0.0775 to 0.0011, moving from mildly positive to essentially neutral. Shares closed at $103.20 before the report, down 3.7% from the open after the July release. The stock had not traced a straight line. It set a 52-week high of $110.51 in mid-August, fell to $87.35 on October 8, then rebounded 18.1% into earnings. That left it 3.6% above its 200-day moving average and 6.6% below the quarter's peak. The trend readings are mixed, with momentum and AVWAP positive while the price trend remains negative. That fits a stock that recovered quickly but has not regained its summer highs.
The bottom line is that Starbucks has moved past the question of whether margins can recover; they already have, ahead of schedule, and the fiscal 2027 EPS guide implies another year of high-teens growth. The debate now shifts to the top line. Revenue is shrinking by design, North American unit growth is thin, and comps are increasingly ticket-driven as transaction gains fade. With sentiment neutral and shares well off their highs, the market appears to accept the margin story while waiting to see whether traffic can carry it.
Read our earnings preview for Starbucks Corporation: https://www.earningswhispers.com/article/SBUX/21242
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 14 hours |
