BridgeBio Beats As Bayer Milestone Flatters The Quarter, But Slowing Attruby Adds Become The Debate Ahead Of Three PDUFAs
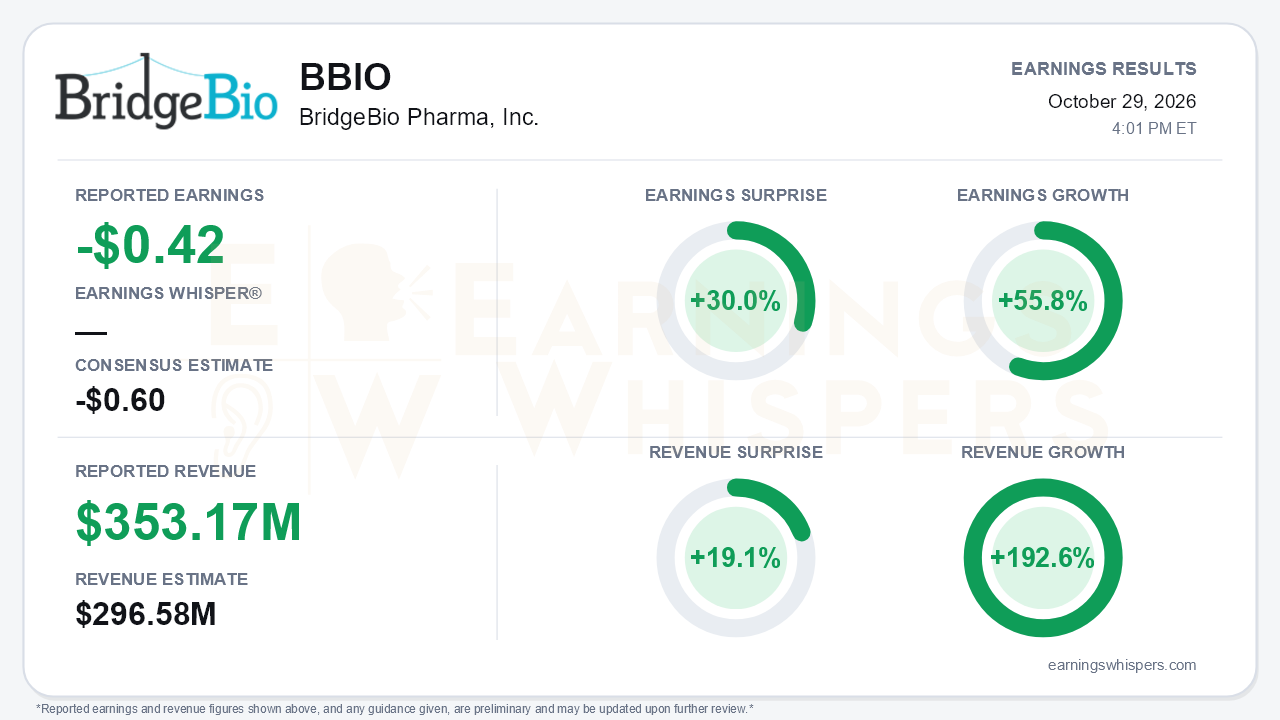
BridgeBio Pharma reported a third-quarter loss of $0.42 per share, beating the consensus estimate of -$0.60 by 30.0% and improving 55.8% from a year ago, when the company lost $0.95 per share. Revenue of $353.17 million topped the $296.58 million consensus by 19.1% and grew 192.6% year over year. Those are big numbers, but the quality of the beat deserves scrutiny. A one-time $75.0 million BEYONTTRA sales milestone from Bayer is larger than the entire revenue surprise. Meanwhile, U.S. Attruby, the engine of the equity story, is still growing but is adding dollars at a visibly slower pace. That is the central tension: the P&L and the pipeline are moving decisively forward while the core franchise's growth curve is flattening.
On the surface, the operating line looks transformed. The loss from operations shrank to $11.6 million from $107.1 million in the second quarter and $145.2 million a year ago. Management flagged two reasons that result should not be treated as a run-rate. The first is the Bayer milestone. The second is favorable timing of launch spending, with operating expenses expected to catch up in the fourth quarter. SG&A still climbed $63.2 million year over year to $200.9 million, and R&D rose $30.6 million to $143.5 million. Below the operating line, $42.3 million of noncash interest on deferred royalty obligations and $26.3 million of preferred dividends and accretion pushed the loss attributable to common stockholders to $83.0 million. Royalty revenue is a cleaner positive. It rose to $20.5 million from $15.4 million in Q2 and $9.5 million in Q1, and management described BEYONTTRA as the leading brand in Europe.
U.S. Attruby net revenue reached $253.2 million, up 134% year over year and now annualizing above $1 billion. Growth was again led by treatment-naïve patients, with Attruby gaining share of new starts. The sequential trajectory, however, has bent. Quarter-over-quarter growth slowed from 35% in Q4 2025 to 24%, roughly 23%, and now 14%. The dollar add of about $31 million trailed the $35 million-plus increments of prior quarters. The more consequential shift is in management's language. On the Q2 call, the company spoke of quarterly adds of "$35 million or more" and a "positive second derivative" within six to nine months. It now frames $25-30 million per quarter as the right near-term base and characterizes the slowdown as normal launch variance. Competitive pressure is also building. Better-resourced rivals are targeting long-tail prescribers, more than 60% of whom have not tried Attruby, which likely means more spending to defend share. UnitedHealth's Vyndamax preference also remains in place, although appeal approval rates exceed 90%.
The pipeline offers a credible offset. BBP-418 for LGMD2I/R9 has a November 27 PDUFA date, product already in the channel, and management confidence in a traditional full approval. Infigratinib's February 4, 2027 PDUFA arrives ahead of the mid-2027 timing given last quarter. Encaleret's May 8 date is unchanged, and confirmed ADH1 patients rose to more than 600 from about 500. RECLAIM-HP topline data in chronic hypoparathyroidism, an estimated 200,000-patient opportunity, were pulled in to early 2028. Fresh real-world comparisons favoring acoramidis over tafamidis strengthen Attruby's clinical narrative, including an 18% lower composite risk and 25% lower all-cause hospitalization in the Epic COSMOS analysis. Two developments cut the other way. BBP-418's EU filing slips to the first half of 2028 because regulators want 36-month FORTIFY data, and Ascendis has filed a citizen petition challenging infigratinib's safety. The $1.5 billion cash position funds all three launches, but it was built with $934 million of preferred stock and $632.5 million of 2033 notes. The $548 million of 2027 notes has also moved into current liabilities.
The market had already turned skeptical before the report. Shares fell 18.6% from the $87.02 open after the August release to $70.82. They peaked at $89.49 that first day and bottomed at $62.86 on October 14. The stock entered earnings 12.7% above that low but 20.9% below the high and 2.7% under its $72.82 200-day moving average. Investor sentiment swung sharply, from a clearly positive 0.38 to roughly neutral at -0.03. Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that BridgeBio delivered a headline beat that overstates near-term operating leverage, because the milestone and deferred spending will not repeat. The quarter also forced a reset of Attruby growth expectations that bears can legitimately exploit. Still, the call kept the larger story intact: a $1 billion-plus franchise, rising royalties, and three potential first-in-disease approvals within seven months. With sentiment already deflated and shares trading just below their long-term average, the next leg likely hinges less on Attruby's quarterly adds and more on how cleanly BBP-418 clears the FDA in November.
Read our earnings preview for BridgeBio Pharma, Inc.: https://www.earningswhispers.com/article/BBIO/21314
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-22 | |
| Oct-16 | |
| Oct-12 | |
| Oct-11 | |
| Oct-11 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 |
