First Solar Posts Record-Level Margins And A 16.5% Beat, But A First Guidance Cut And Shrinking Backlog Reframe The Story
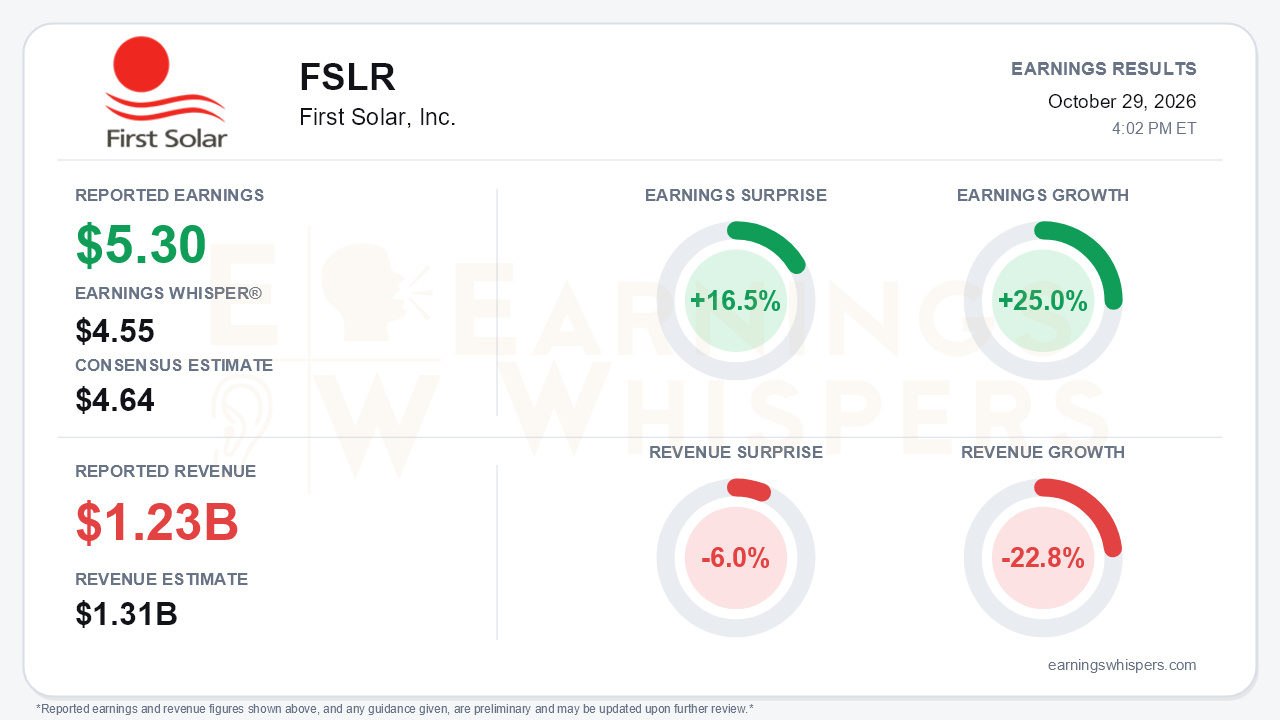
First Solar delivered the most profitable quarter in its recent history and lowered its full-year outlook at the same time, which is the central tension of the third quarter. Earnings of $5.30 per share beat the $4.64 consensus by 16.5% and cleared the $4.55 Earnings Whisper number. EPS grew 25.0% year over year. Revenue moved the other way. Net sales of $1.231 billion missed the $1.31 billion consensus by 6.0% and fell 22.8% from a year ago, driven mainly by lower module volumes sold to third parties. The company is earning more on less volume, and the guidance cut suggests that volume weakness is not yet resolved.
The margin performance was striking. Gross profit rose to $713 million from $611 million despite a $364 million drop in sales. Cost of sales roughly halved, pushing gross margin to about 58%, up from 57% in the second quarter and 47% in the first. Adjusted EBITDA reached $744 million, up from $644 million in Q2 and $520 million in Q1. A small tax benefit and lower interest expense also helped the bottom line.
The quality of the beat deserves some scrutiny, however, because earnings are not converting to cash.
- Operating cash flow was negative $403 million through nine months, compared with positive $815 million a year earlier.
- Government grants receivable, which largely reflect Section 45X credits, rose by about $1.29 billion. The long-term portion jumped to $1.59 billion from $126 million at year-end.
- Inventories also climbed.
- Net cash fell to $1.5 billion, from $1.7 billion in Q2, $2.0 billion in Q1 and $2.4 billion at the end of 2025.
The guidance revision is where the narrative shifted. After reaffirming its outlook in each of the first two quarters, First Solar made these changes:
- Volume sold: cut to 16.0-17.0 GW from 17.0-18.2 GW.
- Net sales: cut to $4.6-$4.9 billion from $4.9-$5.2 billion.
- Adjusted EBITDA: trimmed to $2.55-$2.75 billion from $2.6-$2.8 billion.
- Gross profit: unchanged at $2.4-$2.6 billion.
- Capex: lowered to $0.6-$0.8 billion.
The volume reduction came mainly from roughly 0.7 GW of lower India domestic volume and a lower low end for U.S. Series 6 and finishing volume. Unchanged opex and net cash targets rest partly on deferring South Carolina startup costs to mid-2027 and on reduced capital spending, rather than on stronger operations.
Management's demand commentary was notably more cautious. The August Section 232 proclamation, which management had expected back in the second quarter, has so far produced price-discovery paralysis rather than a buying surge.
- U.S. bookings slowed to 1.4 GW from 1.9 GW in Q2.
- Backlog slid to 44.0 GW from 45.1 GW in Q2 and 50.1 GW at year-end.
- Customers are showing little urgency on 2029-and-later deliveries.
- Management cited state moratoria and local opposition (one roughly 2 GW deal was halted), battery cost inflation, stockpiling of pre-232 inventory and uncertainty over minimum import prices.
- The company is moving away from multi-year framework agreements toward project-specific contracts, which shortens backlog visibility.
The constructive case remains intact.
- U.S. booking prices held near 36 cents per watt, and management says post-232 pricing has moved higher on new and early-stage negotiations.
- South Carolina's first finishing phase began production, with 2.2-2.5 GW guided for 2027.
- The Cubic PV perovskite license adds to the Oxford PV IP.
- A Series 7 CuRe conversion in India is slated for early 2027.
Bears have legitimate ammunition too.
- Roughly 4 GW of optional volume sits at pre-232 pricing that customers may exercise.
- Malaysia faces a binary run-or-shutdown decision in the first half of 2027.
- The Swift Current lawsuit over Series 7 warranty issues adds legal risk.
- Perovskite spending rose to about $120 million from about $100 million, and legal costs for TOPCon IP enforcement are climbing.
The new $500 million buyback signals confidence. It also arrives with net cash below the year-end target range and operating cash flow negative, so its pace will likely depend on 45X monetization.
The market had already priced in much of the disappointment. Shares entered the report at $176.30, down 17.1% since the open after the July report and 18.6% below the 200-day moving average. The stock has fallen about 35% from its August 7 high of $269.70 and sits just 6.3% above a fresh 52-week low of $165.86 set on October 26. Investor sentiment was essentially unchanged, moving from -0.177 to -0.166, which leaves it mildly negative. Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative. That mirrors the gap between improving profitability and a deteriorating stock chart.
The bottom line is that First Solar's profitability has never looked better, but the forward indicators investors care about are moving the wrong way. Guidance, bookings, backlog and net cash all declined, and Section 232 has yet to translate into orders. With shares near their lows and sentiment already subdued, the report may not shock holders. Still, a durable re-rating likely requires evidence that post-232 pricing is converting into bookings and that 45X credits are converting into cash.
Read our earnings preview for First Solar, Inc.: https://www.earningswhispers.com/article/FSLR/21197
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-21 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 |
