Sandisk Beats And Raises Again As Data Center Surges, But Slowing Sequential Growth And A Fading Pricing Tailwind Define The Quarter
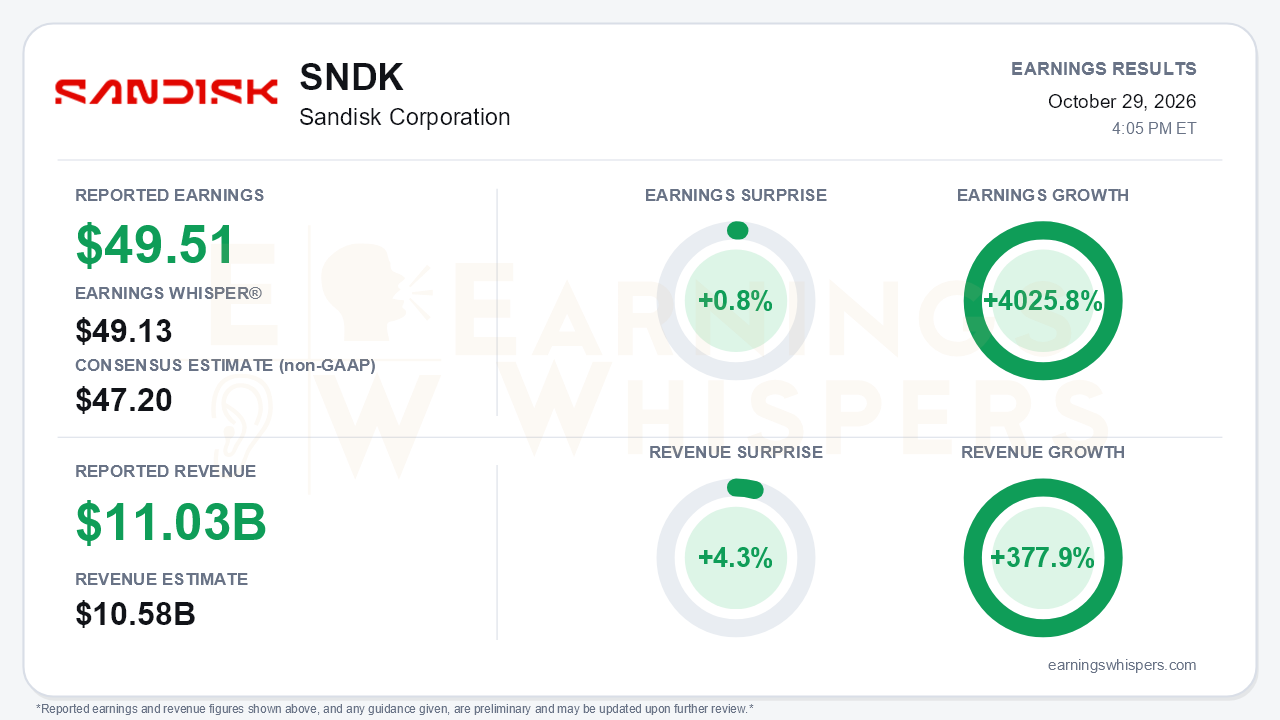
Sandisk delivered another beat-and-raise quarter. Fiscal first-quarter non-GAAP earnings of $49.51 per share topped the $47.20 consensus and edged past the $49.13 Earnings Whisper number, a 0.8% surprise. Revenue of $11.031 billion beat the $10.58 billion consensus by 4.3% and cleared the company's own $10.3-$10.8 billion guide. Year-over-year comparisons are extreme: earnings grew 4025.8% and revenue grew 377.9% against a period when the company earned $1.22 per share on gross margin below 30%. Fiscal second-quarter guidance of $12.2-$12.6 billion in revenue and $55-$57 in pre-split EPS was again above expectations. Yet the central tension is not whether Sandisk can beat. It is how fast the curve is flattening. Sequential revenue growth has gone from 97% in fiscal Q3 to 51% in Q4 to 23% this quarter, and the new guide implies roughly 13%.
The composition of the quarter shows what is changing. Management said growth was about 60% volume and 40% price, a reversal from roughly one-third volume and two-thirds price in Q4, and it described forward pricing as modest. That is arguably a healthier mix, since volume-led growth is more durable than price spikes. Still, it signals that the pricing windfall behind 85% gross margins is maturing. Margin itself kept inching up, with non-GAAP gross margin at 85.1% versus 84.6% and operating margin at 80.4% versus 79.2%. The incremental gains are now measured in tenths of a point rather than the leap from 78.4% two quarters ago.
Several lower-quality elements also deserve scrutiny:
- GAAP EPS of $52.60 ran above the non-GAAP figure because of a $513 million mark-to-market gain on equity securities.
- Operating cash flow fell to $6.36 billion from $7.13 billion, largely because customer prepayments under the company's long-term agreements (NBMs) shrank.
- Accounts receivable jumped about $1.9 billion to $6.6 billion.
- Adjusted free cash flow rose to $5.7 billion, but its margin slipped to 52% from 56%.
The segment picture is lopsided. Data center revenue rose 61% sequentially to $4.8 billion, up from $2.98 billion in Q4 and $1.47 billion in Q3, and is now the clear engine of the business. Edge grew only 7% to $5.8 billion as PC and smartphone units troughed and the low end contracted. Management cited Intel's PC-driven guide-down as evidence of that weakness. Consumer fell 29% to $397 million as demand adjusted to higher prices, extending a 32% drop in Q4. Sandisk is increasingly a data center story, and the end markets outside it are softening.
The forward-looking evidence gave bulls substantial support:
- **NBM pipeline:** Management said the pipeline of long-term agreements now exceeds supply through the end of the decade. It signed its first second-tranche NBM with a largest customer and expects NBM coverage to rise above two-thirds of fiscal 2028 bits, from roughly half of fiscal 2027.
- **Data center demand:** Calendar 2027 data center bit demand is guided to grow about 40% and exceed 55% of the NAND market.
- **New products and use cases:** The first high-bandwidth flash (HBF) die has taped out. Early customer interest in SLC-mode NAND as a DRAM substitute for agentic AI workloads could tighten supply further.
The offsets are real. No new NBM customers were added beyond the two announced last quarter. Management also steered investors toward conservative modeling of a seasonally weak fiscal Q3; bits fell 19% sequentially in the prior-year period. The capex outlook moved to mid-single digits as a percentage of revenue from about 6%.
Capital returns remain aggressive. Sandisk repurchased $5.0 billion of stock, up from $4.5 billion, and has retired about 4% of shares over two quarters. Diluted shares are guided to about 151 million versus 154 million this quarter. The eight-for-one split, with split-adjusted trading beginning November 20, changes nothing fundamentally but broadens accessibility.
Investor sentiment became meaningfully more positive heading into the report, rising from 0.20 to 0.39. Price action tells a more cautious story. Shares entered earnings at $1,404.77, up 19.7% since the open after the August report and 12.7% above the 200-day moving average. However, they sat 26.4% below the September 22 high of $1,909.48, having surrendered much of that run. The call analysis noted the stock trading notably lower despite the results, and analysts questioned management about neocloud credit exposure; management reported no impact. Sequential-growth and momentum trend readings remain positive, while AVWAP is negative, consistent with a stock that has lost altitude from its peak.
The bottom line is that Sandisk's fundamentals remain extraordinary: 85% gross margins, a data center business growing 61% sequentially, and a contract pipeline management says exceeds supply for years. But the market is now pricing the second derivative. Growth is decelerating quarter by quarter, pricing is giving way to volume, consumer and low-end Edge are shrinking, and management is already cautioning about fiscal Q3. Bulls can point to durable, contracted data center demand. Bears have legitimate ammunition in the slowing trajectory and a stock that has already given back a quarter of its peak value.
Read our earnings preview for Sandisk Corporation: https://www.earningswhispers.com/article/SNDK/21244
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours |
Sandisk Clears Fiscal Q1 Targets, Announces 8-For-1 Stock Split
SNDK -5.32%
Investor's Business Daily
|
| 4 hours | |
| 4 hours | |
| 12 hours | |
| 12 hours | |
| 13 hours | |
| 14 hours | |
| 15 hours | |
| Oct-28 | |
| Oct-28 |
