Reddit Misses The Whisper As Search Losses Turn Record Profitability Into A Growth Question
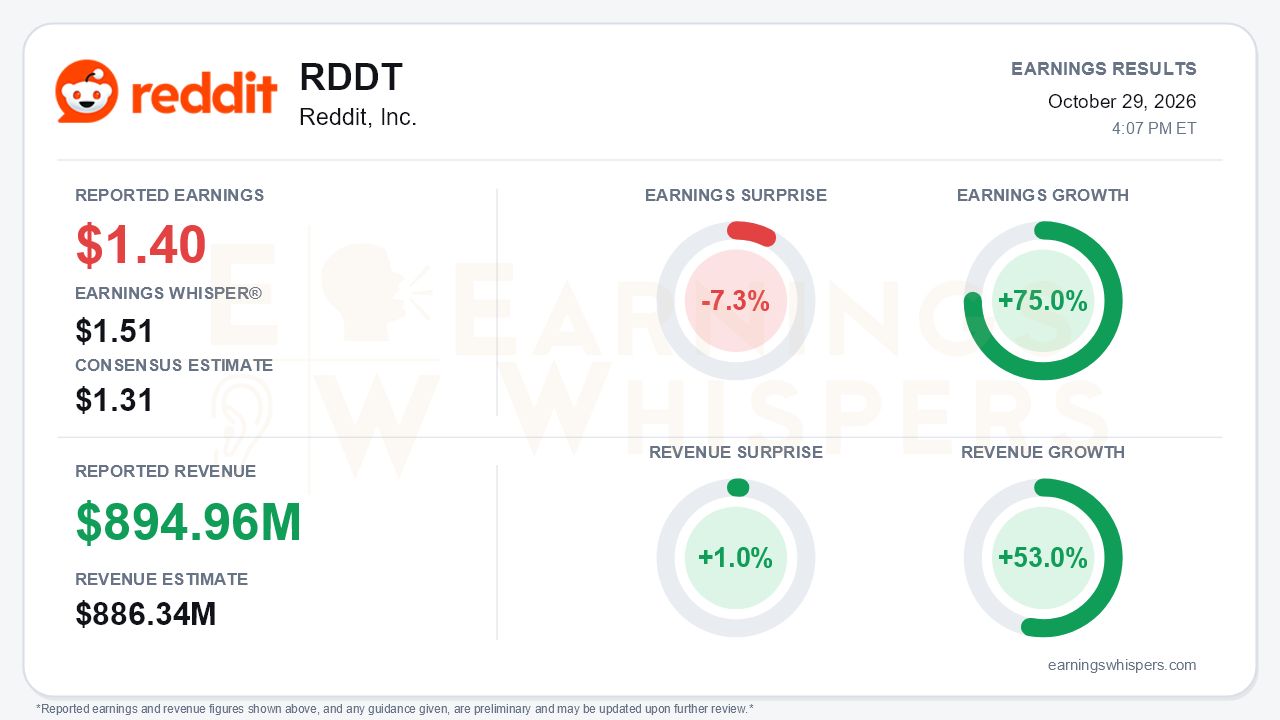
Reddit's third quarter delivered its most profitable results to date, but the report's most important line came from management's warning about users, not from the income statement. The company earned $1.40 per diluted share on revenue of $894.96 million. That cleared the $1.31 consensus estimate but fell 7.3% short of the $1.51 Earnings Whisper number. Earnings grew 75.0% year over year and revenue grew 53.0%, topping the revenue consensus by 1.0%. Those growth rates would be exceptional almost anywhere. At Reddit, though, the 53% revenue increase ended a run of eight straight quarters above 60%, and fourth-quarter guidance came in below estimates. That is the central tension: profitability keeps compounding while the top-line and audience story is clearly bending.
The quality of the quarter is strong on profitability and weaker on momentum. Adjusted EBITDA rose 70% to $402 million, a 44.9% margin, extending a steady climb from 40% in the first quarter and 43% in the second. GAAP net margin reached 31.7%, gross margin edged up to 91.5%, and free cash flow nearly doubled to $363 million. The trend in the beat deserves scrutiny, however. Revenue topped the $860-870 million guide by roughly $25 million at the high end. In the second quarter, revenue of $805 million beat the high end of the guide by about $80 million. Ad revenue growth slowed to 54% from 64% in the second quarter and 74% in the first. Stock-based compensation also rose to $131 million from $84 million a year ago, a cost the adjusted EBITDA figure excludes.
The user metrics explain why the call turned more cautious. Global DAUq rose 12% to 130.3 million, but the gain came entirely from international markets, up 24%. U.S. DAUq fell 2%, U.S. logged-out users dropped 4%, and U.S. weekly uniques were flat. Monetization has so far masked that weakness, with U.S. ARPU up 53% to $13.82. Management's commentary on search traffic, however, escalated sharply from earlier calls:
- In the first quarter, search referrals were described as business as usual.
- In the second quarter, they were called choppy.
- In the third quarter, they were down meaningfully, accelerating late in the period, with more than 1 million fewer referrals per week in October.
Management attributed the decline to Google's AI Overviews and AI Mode and to lower ranking of machine-translated content. That points to a structural problem rather than a cyclical one. Management also warned that total DAUq could fall by a low double-digit percentage in the fourth quarter. The tone shifted with it. CEO Steve Huffman called this a consequential time, likening it to when he returned to the company about 11 years ago. The 1 billion DAU goal emphasized earlier in the year went unmentioned.
The call still preserved a credible monetization story. Conversion volume more than tripled year over year, up from over 100% growth in the second quarter. Click volume grew over 50%, Reddit Max adoption more than tripled sequentially, and Ads API revenue jumped more than 45% sequentially. Management said logged-in and app users, who drive over 80% of monetization, grew sequentially. That is the logic behind the planned move to a logged-in-only experience, with tests starting in select non-U.S. markets in the fourth quarter. The trade is explicit: give up reach in exchange for engagement, with conversion rates still unknown. Other open items add risk. Content-licensing renewals with Google and OpenAI are unresolved, and management acknowledged that no deal is a possible outcome. Increased international user-marketing spend has yet to show a return.
Guidance reflects both sides of the business. Fourth-quarter revenue of $1.00-1.03 billion implies growth slowing to roughly 40%. Adjusted EBITDA of $480-510 million implies a margin near 49%, so management is effectively guiding to slower growth paired with higher margins. Investors had already turned cautious ahead of the report. Earnings Whispers sentiment fell from roughly neutral at -0.05 to -0.23, a meaningful move further into negative territory. Shares closed at $134.70 heading into the release, down 8.8% from the open after the July report. They sat 16.7% below the 200-day moving average and just 1% above the inter-earnings low of $133.33 set on October 26, nearly 27% below the August 14 high of $184.28. Reddit spent $100 million on buybacks during the quarter at an average of $149.81, well above where the stock entered earnings, while slowing repurchases from about $235 million in the second quarter. The Earnings Whispers trend signals are mixed, with sequential growth positive while price and AVWAP trends remain negative.
The bottom line is that Reddit beat consensus on a GAAP basis and keeps expanding margins at a remarkable pace, but it missed the whisper, guided revenue below estimates, and warned of a meaningful drop in users tied to changes in Google search. Bears have legitimate ammunition in the narrowing beat, the stalled U.S. audience, and the unresolved licensing renewals. Bulls can point to improving ad performance and a deliberate pivot toward higher-value logged-in users. Until audience trends stabilize, the market is likely to weigh where traffic is heading more heavily than how much profit Reddit earns from it.
Read our earnings preview for Reddit, Inc.: https://www.earningswhispers.com/article/RDDT/21235
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 15 hours | |
| 16 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 |
