Shell Beats On Record Refining Margins And Lifts Buyback To $5 Billion, But Q4 Headwinds Are Already Building
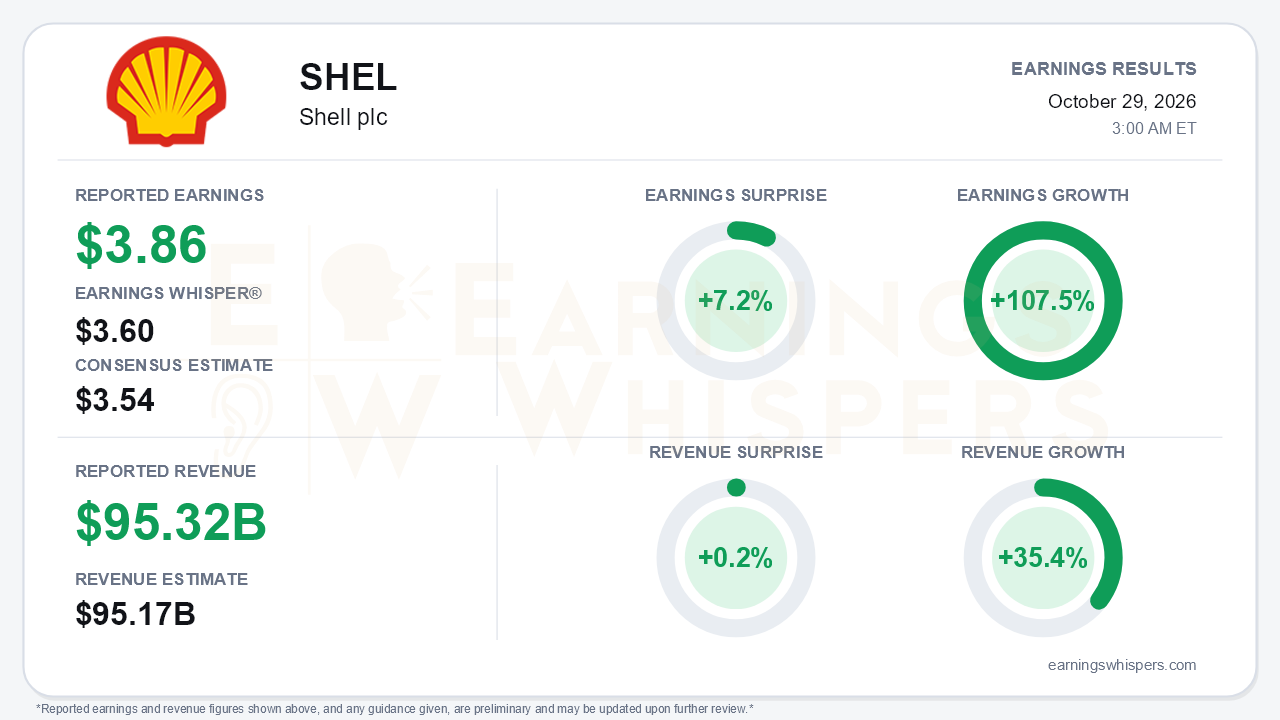
Shell delivered its strongest quarter of 2026. Adjusted earnings of $3.86 per ADS beat the $3.54 consensus by 7.2% and cleared the $3.60 Earnings Whisper number. Revenue of $95.32 billion was essentially in line, edging past the $95.17 billion estimate by 0.2%. Earnings grew 107.5% year over year on 35.4% revenue growth, and adjusted earnings rose to $10.8 billion from $9.8 billion in Q2, roughly $7 billion in Q1 and $3.3 billion in Q4 2025. The central tension is the source of that strength. It came largely from conflict-distorted refining and LNG markets, and management signaled that some of those tailwinds are already fading into the fourth quarter.
The quality of the beat deserves scrutiny. Chemicals and Products contributed $3.86 billion of adjusted earnings, up from $2.88 billion in Q2. Products alone generated $3.75 billion as refining margins added about $1.07 billion sequentially, while Chemicals earned just $103 million. Integrated Gas improved to $3.04 billion on higher realized LNG prices and one month of ARC Resources volumes. Upstream adjusted earnings slipped to $3.19 billion from $3.49 billion because of $309 million in higher well write-offs and lower liquids realizations. Marketing fell to $1.16 billion on weaker Mobility unit margins and softer lubricants volumes.
GAAP income of $12.06 billion also leaned on a $0.8 billion net gain from identified items. That gain combined a $1.29 billion impairment reversal tied to LNG Canada Phase 2 and changed commercial terms with a $777 million gain on the Na Kika sale. These offset a $1.9 billion write-down of European biogas assets.
Cash generation was robust but less clean than it looks. Operating cash flow of $21.0 billion was flat with Q2, and it was flattered by $3.4 billion of derivative inflows that management acknowledged could reverse with margining. A $2.2 billion outflow on emission-certificate and biofuel payment timing pulled the other way. Even so, the balance sheet improved meaningfully. Net debt fell to $39.7 billion from $41.8 billion despite absorbing ARC's debt, and gearing dropped to 16.6% (2.7% excluding leases). That strength funded a buyback increase to $5.0 billion from $3 billion in each of the first two quarters. Management framed the larger program as a top-up to keep distributions within its 40-50% of operating cash flow payout range, after analysts had flagged a run-rate below that band. The CEO also conceded that the April buyback trim had been premised on a temporary price spike that did not materialize.
The call preserved a credible growth story. ARC closed in September and adds roughly 370 kboe/d immediately. The LNG Canada Phase 2 FID will give Shell nearly 6 mtpa of additional LNG in the early 2030s, which management described as upside not included in the ARC thesis. Other developments:
- The Gulf of America posted its highest monthly production in two decades.
- Refining ran above 100% utilization outside Rheinland.
- Chemicals generated positive free cash flow for a second straight quarter, with sale discussions described as deep.
- Full-year capex guidance was trimmed to $23-25 billion from $24-26 billion despite the acquisitions, mostly on phasing.
Management sounded noticeably more confident on resource depth, calling 2030 de-risked.
Bears still have legitimate ammunition for the next print:
- October integrated refining margins were already below Q3 levels.
- Freight on Middle East-China routes is running about ten times year-ago rates, and management flagged lower fourth-quarter realizations across refining, chemicals and oil.
- Qatar and Pearl GTL disruptions persist, with train 2 not expected back until late Q1 2027.
- Cash tax payments are catching up.
- Shell expects a non-cash identified loss of about $6.4 billion in Q4 from the Dutch pension transition, which will weigh heavily on GAAP results even though it is excluded from adjusted earnings.
- Production available for sale of 2,574 kboe/d remains below the 2,821 kboe/d of a year ago.
The market has already rewarded much of the upswing. Shares have climbed 19.6% since the opening after the July report, to $107.67, and sit about 22% above the 200-day moving average of $88.08. The Earnings Whispers price and AVWAP trend readings are positive. Investor sentiment has not followed price, however. It was essentially unchanged at -0.20, still mildly negative, which suggests investors remain skeptical of how durable the margin windfall is even as they own the stock's rally.
The bottom line is that Shell paired a clean beat with tangible strategic progress: ARC closed, LNG Canada Phase 2 was sanctioned, debt fell and the buyback grew. Those gains build the long-term volume base. The near-term earnings power, though, rests heavily on refining and LNG conditions that management itself expects to soften, so the February 4 capital markets update and Q4 cash conversion will matter more than this quarter's headline beat.
Read our earnings preview for Shell plc: https://www.earningswhispers.com/article/SHEL/21128
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 10 hours | |
| 11 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 |
