Chevron Clears A Low Bar As Refining Strength Offsets A Sequential Upstream Slide, While Venezuela And Bakken Reshape The Growth Story
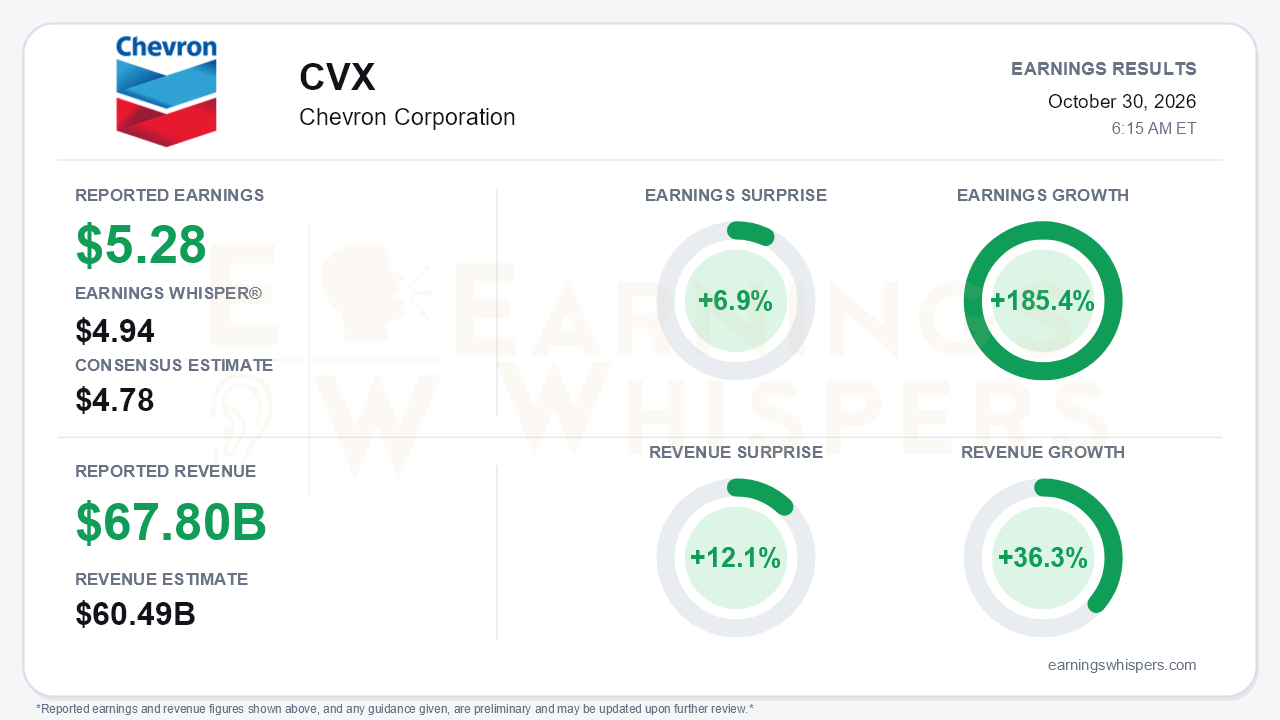
Chevron delivered a clean beat in a quarter that was weaker than the one before it. Adjusted earnings of $5.28 per share topped the $4.78 consensus and the $4.94 Earnings Whisper number by 6.9%. Revenue of $67.8 billion beat the $60.49 billion consensus by 12.1%. Year-over-year comparisons look spectacular: earnings grew 185.4% and revenue 36.3%, helped by a Brent average of $97 versus $69 a year ago. Sequentially, however, adjusted EPS fell from $6.06 in the second quarter. That is the central tension: a decisive beat against expectations, delivered while the upstream earnings engine was cooling from its second-quarter peak.
The quality of the beat holds up better than the sequential decline suggests. Timing effects reduced earnings by $1.58 billion in the quarter, compared with a $1.54 billion benefit in Q2. These are mark-to-market and LIFO effects tied to the late-quarter price spike, and they remain inside the adjusted figure. A swing of roughly $3 billion explains much of the step-down, so the $5.28 result absorbed a meaningful accounting headwind rather than being flattered by one. GAAP earnings of $5.06 per share ($9.9 billion) carried several charges:
- a $160 million legal reserve;
- a $110 million impairment;
- $24 million in pension settlement costs;
- $143 million in adverse currency effects.
The bigger story beneath the headline is the shift in the earnings mix. Upstream earnings fell to $5.7 billion from $8.2 billion in Q2 as realized prices dropped:
- U.S. liquids fell to $62.72 from $70.80 per barrel.
- International liquids fell to $86.09 from $96.41 per barrel.
Downstream earnings held at $4.9 billion, nearly matching the upstream segment. U.S. downstream alone earned $3.6 billion, up from $638 million a year ago, on record crude throughput of 1.09 million barrels per day and roughly 98% utilization. On the call, management credited a proprietary catalyst with lifting distillate yields by more than 10% at its largest U.S. refineries.
This is where bears have legitimate ammunition. Management itself expects refining and petrochemical margins to normalize as conflict-related outages resolve, and it flagged possible petrochemical oversupply. Total production slipped to 3,980 thousand barrels of oil equivalent per day, from 4,070 in Q2 and 4,086 a year ago. The release attributed the decline to price-driven entitlement losses and Middle East disruptions, and Permian volumes dipped slightly quarter over quarter. The freight-rate tailwind from Chevron's controlled fleet also depends on the conflict continuing.
What the call added was a materially larger growth pipeline.
- **Venezuela:** New fiscal terms and expanded acreage support a plan to reach roughly 300 thousand barrels per day gross by year-end and about 600 thousand by 2031. Management described this as self-funding, at an all-in cost below $20 per barrel, with $7 billion of joint-venture investment over five years.
- **Bakken:** The midstream restructuring cuts tariffs by about 50%, adds roughly half a point to corporate ROCE and deconsolidates $3.7 billion of debt.
- **Exploration:** Spending will rise about 50% from 2025 levels, the Angola discovery came in strong, and Tengizchevroil's expansion has lifted field capacity to roughly 1 million barrels per day.
There were trims alongside these additions. The Bakken plateau is now framed at 180 thousand barrels of oil equivalent per day, versus roughly 200 thousand cited earlier in the year, and the Tengizchevroil concession extension remains unresolved. Venezuela's upside also comes with obvious political risk.
The balance sheet gives Chevron room to pursue that agenda. Operating cash flow was $16.0 billion and adjusted free cash flow was $14.2 billion, though the latter was aided by a $1 billion loan repayment from Tengizchevroil and asset sales. Total debt fell another $3.5 billion and net debt fell $7.8 billion, taking net debt to operating cash flow down to 0.4x from 0.6x. Management reaffirmed capex at the low end of guidance and quarterly buybacks of $2.5 billion to $3 billion.
The market setup is more complicated than the surprise implies. Shares had climbed 18.6% since the open following the July report, to $231.46. That left them about 20% above the 200-day moving average and just 1.1% below a 52-week high of $234.08 set four days before the release. The stock entered earnings near the top of an inter-earnings range that bottomed at $185.87 in early August, so much of the commodity windfall was arguably already priced. Investor sentiment remained positive but weakened noticeably, falling from 0.39 to 0.25. That suggests enthusiasm was cooling even as the stock pressed higher. The Earnings Whisper trend readings are mostly positive on price and momentum, while sequential growth is neutral, which fits a quarter that eased from its peak.
The bottom line is that Chevron beat expectations comfortably and absorbed a large timing headwind. Its refining business is carrying an unusually heavy share of the load at record throughput. The upstream slide and management's own warning about margin normalization mean this quarter's mix is unlikely to persist. Venezuela, the Bakken reset and the exploration step-up gave the company a more credible long-duration growth story than it had three months ago. With shares sitting near their highs and sentiment fading, investors will need evidence that those catalysts can offset the eventual retreat in refining margins.
Read our earnings preview for Chevron Corporation: https://www.earningswhispers.com/article/CVX/21279
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours |
