Estee Lauder Beats Big And Raises Again, But The Guidance Lift Is Smaller Than The Quarter's Upside
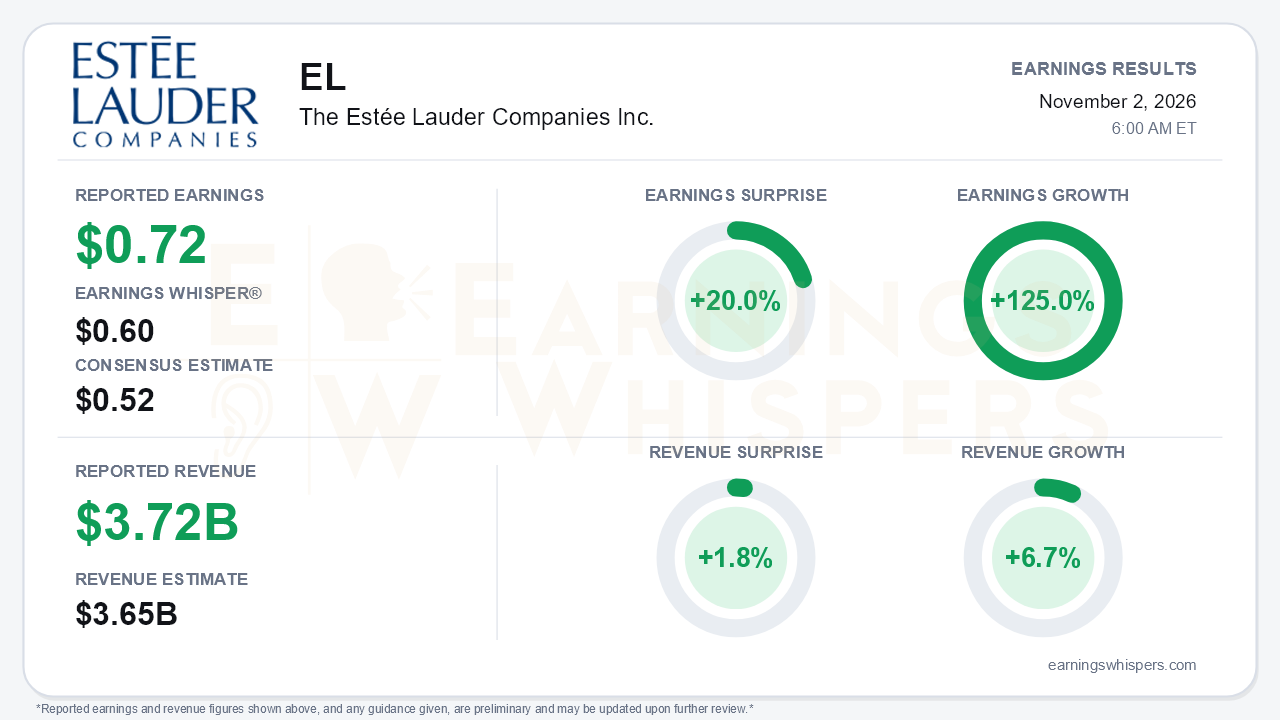
Estée Lauder opened fiscal 2027 with its cleanest quarter of the turnaround. Adjusted EPS of $0.72 beat the $0.52 consensus by 20.0% and topped the $0.60 Earnings Whisper number, while revenue of $3.715 billion beat by 1.8%. Earnings grew 125.0% year over year on 6.7% revenue growth, and management raised every full-year guidance line for the fourth consecutive call. The central tension is that the raise barely exceeded what the first quarter delivered. The EPS outlook rose by only $0.10 at the midpoint, to $3.20-$3.45, which is half the size of the quarter's beat against consensus. The company also says the new range remains in line with estimates, and management continues to guide to a stronger first half than second half.
The quality of the beat is mostly genuine, with one caveat. Organic sales rose 6%, the third straight quarter of acceleration from 2% two quarters ago and 5% last quarter, with growth in every region. Adjusted gross margin expanded 240 basis points to 75.7% on Profit Recovery and Growth Plan savings, pricing, and leverage. Adjusted operating margin jumped 480 basis points to 12.1%, a larger expansion than the 330 and 360 basis points posted in the prior two quarters. That gain came even as consumer-facing investment rose 8%. Adjusted operating income grew 76%, but EPS more than doubled. The gap is largely explained by tax: the adjusted effective rate fell to 31.9% from 40.5%, below the 33%-34% guided for the full year. Investors should treat some of the EPS leverage as non-recurring.
Beneath the headline, fragrance is doing the heavy lifting. Organic fragrance sales rose 20%, double the 10% pace for fiscal 2026, led by Le Labo, TOM FORD, Jo Malone London, KILIAN PARIS and Estée Lauder's Glimmer launch. Fragrance operating income rose 93% to $166 million. Skin care grew 4% organically, but its operating income climbed 40%. Makeup grew for a second straight quarter, and management noted that M·A·C is gaining both volume and value share in the U.S. for the first time in a long while. Asia/Pacific grew 10% organically as Beijing and Shanghai airport replenishment resumed, and management declared the duty-free retailer transition complete. Mainland China rose 9% organically, its seventh straight quarter of share gains, in a market that management said slowed to low-single-digit growth.
The risks are mostly about the back half. Management expects tougher comparisons in Asia travel retail and China during the second half. The first quarter also carried a heavy innovation load of 29% of sales, against a 25% full-year target, so the launch calendar is front-loaded. Deferred freight and commodity costs will weigh more on second-half gross margin. Aveda supply-chain problems left hair care flat. U.S. value share in skin care and makeup is still not positive overall. The outlook also assumes no further deterioration in the Middle East or in disrupted EUKEM markets. Cash flow improved, with free cash outflow narrowing to $235 million from $436 million. However, inventory rose $146 million, compared with a slight decline a year ago, and the raised $1.4-$1.5 billion operating cash flow target is still below fiscal 2026. Potential catalysts include the Forest Essentials acquisition, the Glimmer rollout to Europe and Latin America, and the November 4 Capital Markets Experience in Shanghai.
The market setup is more complicated than the surprise implies. Shares closed at $109.23 before the report, up 16.5% since the open following the August release. That leaves the stock 19.1% above its 200-day moving average and just 1.9% below its inter-earnings high of $111.33, set on October 29. Much of that move came late: the stock bottomed at $88.68 on October 1 and rallied roughly 25% into the print. Investor sentiment became more positive, rising from 0.065 to 0.162, but it remains only modestly constructive rather than euphoric. The Earnings Whispers trend signals lean positive on price, momentum and AVWAP, while sequential growth is neutral. That fits a business improving faster year over year than it is accelerating quarter to quarter.
Bulls have the stronger argument on fundamentals. Accelerating organic growth, broad-based margin gains, all-region growth and a fourth consecutive raise make the Beauty Reimagined story more credible. Bears, however, have legitimate ammunition on expectations. The guidance raise largely flows through the first-quarter beat rather than lifting the second-half run rate, and a tax tailwind flattered EPS. The stock also arrived at the report after a sharp run near its highs.
The bottom line is that Estée Lauder delivered a high-quality beat that confirms its turnaround has shifted from repair to growth, led by fragrance, China and travel retail. With management signaling a softer second half and the shares already priced near their quarterly highs, the next test is whether margin gains and share wins hold once the front-loaded innovation and easy comparisons fade.
Read our earnings preview for The Estée Lauder Companies Inc.: https://www.earningswhispers.com/article/EL/21346
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 26 min | |
| 1 hour |
The Ozempic Boom Has An Unexpected Winner: Americans Are Spending More On Beauty, Fashion And Wellness
EL
International Business Times
|
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 7 hours |
