Rocket Lab's Q3 Report Puts Neutron's Narrowing Launch Window Ahead Of Record Revenue
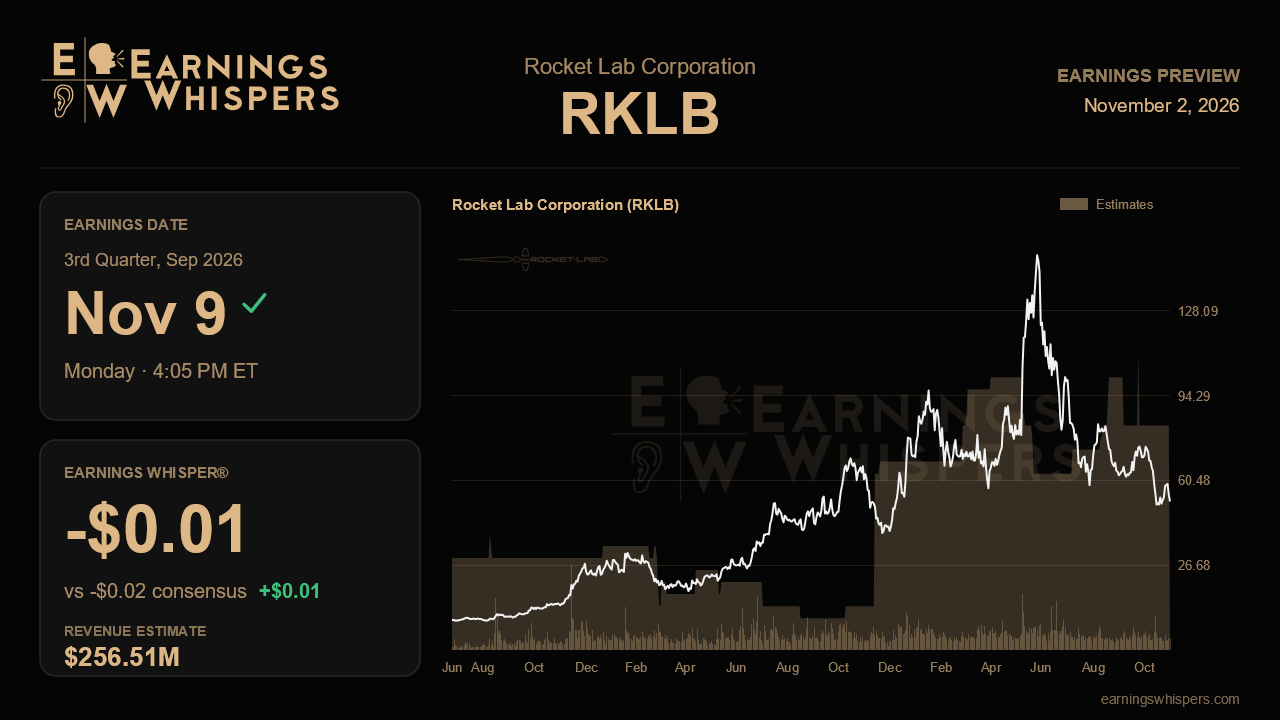
Rocket Lab heads into its third-quarter report with a striking disconnect. The business keeps setting records, the backlog keeps climbing, and management sounded more expansive last quarter than at any point in the past year. Yet the stock has lost more than a quarter of its value since that report. When the company posts results after the close on November 9, the revenue number may matter less than what management says about Neutron, the medium-lift rocket whose first flight is now targeted for the fourth quarter of 2026, a window that is already partly gone.
The Street expects a non-GAAP loss of 2 cents a share on revenue of about $256.5 million. That would be roughly 65% higher than a year ago, an exceptional growth rate for a company of this size, and a solid sequential step up from the record $234.1 million posted last quarter. Management guided to $250 million to $265 million, and consensus sits just below the $257.5 million midpoint, comfortably inside the range. Given that Rocket Lab has delivered an uninterrupted string of sequential gains, a print at or above the top of guidance would be needed to genuinely surprise. The Earnings Whisper of a 1-cent loss is a hair better than consensus, a gap too small to signal much beyond modest confidence that cost control will hold.
That cost control is a real question. Last quarter's adjusted EBITDA loss of $8.8 million was far narrower than the $20 million to $26 million loss management had guided, a beat that flattered the profitability story. This time, management guided GAAP gross margin down to a range of 35% to 37%, citing a heavier mix of lower-margin satellite platform work and dilution from the newly acquired Monaric business in Germany. Margins landing in the upper half of that range would suggest the mix drag is manageable; a slip toward the bottom, or below it, would reinforce worries that growth is being bought with weaker unit economics. Free cash flow deserves equal scrutiny after cash burn widened to $110.1 million last quarter on Neutron production and Monaric supply-chain rebuilding. The balance sheet, bolstered to roughly $2.4 billion in liquidity, can absorb that pace, but investors will want evidence the burn is plateauing.
Launch revenue is the other swing factor. It fell about 30% sequentially last quarter as the accounting mix shifted toward Haste suborbital missions recognized over time rather than Electron flights booked at a point in time. A rebound would show that lumpiness was just that, while another soft quarter would raise questions about Electron cadence. Backlog, which reached $2.36 billion with more than 90 launches booked, should continue rising if the extreme demand management described is real, especially with the $266 million Haste award, the $397 million SDA contract and the first geostationary satellite wins feeding the pipeline.
Sentiment has cooled, with bullish readings slipping from 8% before the last report to 3% now, and the stock tells the same story. At $54.73, shares sit far below their 200-day moving average near $80 and close to the post-earnings low of $49.25, after a prior quarter in which they touched $151. Expectations around the stock, if not the quarter's numbers, have reset sharply lower, which gives a clean report some room to be rewarded.
Ultimately, this report is a credibility test on Neutron. The first flight has slipped from mid-2025 to late 2025, then to early 2026, and now to the final quarter of this year, with stage testing still the riskiest milestone remaining. Management has tied free cash flow positivity to a window 18 to 24 months after Neutron's first launch, and the SDA and Kepler contracts depend on it. A concrete update showing stage testing completed and the vehicle on track would validate the space-power narrative behind the pending Iridium deal. Another delay into 2027 would push every downstream milestone back, regardless of how strong the revenue line looks.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 |
