On Holding's Wholesale Reset Faces Its Test As Q3 Growth Dips Below 15%
On Holding enters its third-quarter report with an unusual setup: a premium brand that just cut its growth outlook for the first time, yet whose stock has outperformed the market handily since that cut. Last quarter, management deliberately held back shipments to wholesale partners in the Americas, citing soft full-price sell-through of everyday running shoes in a promotional market. It also warned that most of the remaining wholesale cleanup would land in the third quarter. That makes this report the clearest evidence yet of whether the pullback was a contained, self-inflicted reset or the first sign of a broader demand problem.
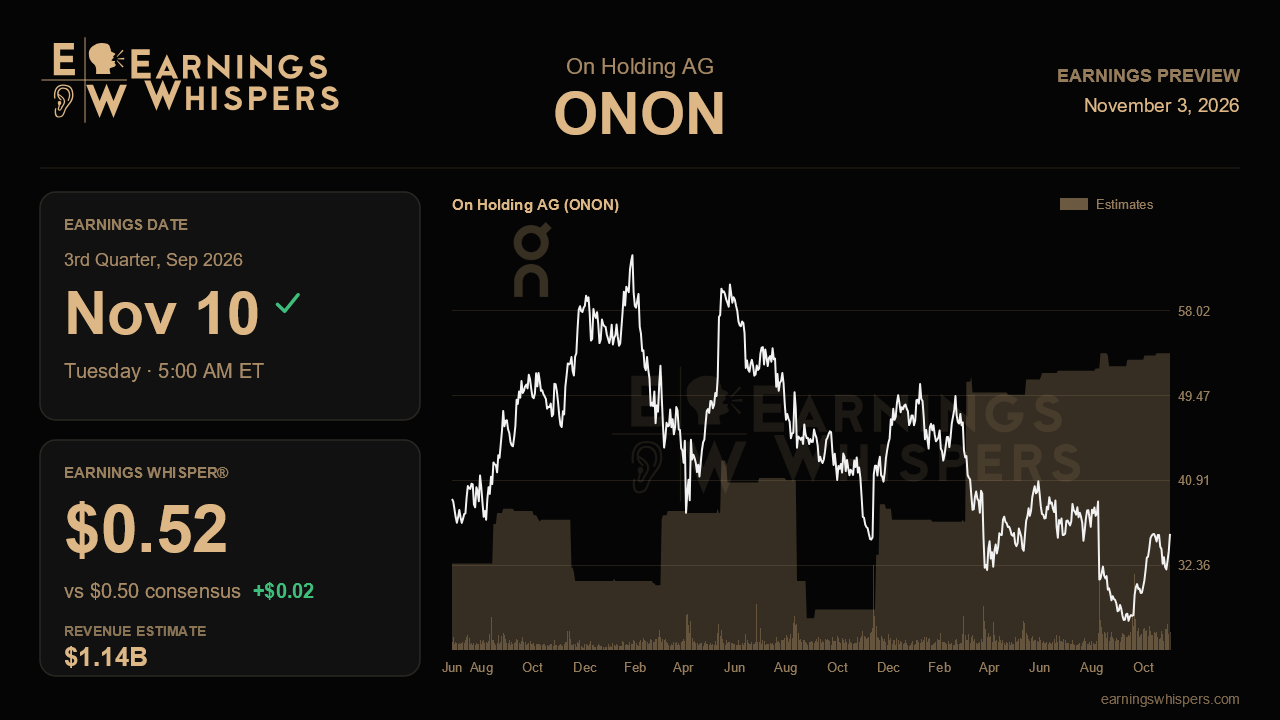
Wall Street expects earnings of $0.50 per share on revenue of about $1.14 billion. The revenue figure implies growth of roughly 14.8% in dollars, a sharp step down from the low-to-mid 20s pace of recent quarters and well below the low-20s constant-currency rate management now targets for the full year. That gap is not alarming in itself, since management explicitly guided third-quarter growth below the fourth quarter. The earnings whisper of $0.52 sits only slightly above consensus, so the bar for a modest beat is a bit higher than the official number but not by much. EPS would compare with $0.42 a year ago and $0.39 last quarter. Management has since reaffirmed its 2026 revenue outlook of $4.28 billion to $4.39 billion, and the $4.33 billion consensus sits comfortably near the midpoint. In other words, the Street has accepted the reset rather than betting on a quick rebound.
The wholesale and Americas lines matter most. Wholesale growth slowed to 12.7% in constant currency last quarter from 25.1% in the first quarter, and the Americas decelerated for a third straight quarter to 13.0%. If those figures slow sharply again but management describes cleaner channel inventory and healthier full-price sell-through, the story holds that this is discipline rather than weakness. If sell-through commentary stays soft or management signals more actions into the fourth quarter, the case for a transitory drag weakens considerably. Company inventory, which was up about 30%, is another tell. A slowdown in that build would suggest supply is being matched to demand.
The offsets also need to hold up. Direct-to-consumer sales accelerated to 34.3% growth in constant currency and reached a record 45.7% of the mix, while gross margin climbed to 65.4% and full-year margin guidance was raised for the third consecutive time, to at least 65%. Continued DTC strength, plus apparel and Asia-Pacific growth near last quarter's blistering pace, would show that the brand's pull with consumers remains intact even as wholesale is reined in. The softer spot is adjusted EBITDA margin, which slipped to 19.8% last quarter and was only reiterated at 19.5% to 20% for the year. A higher gross margin that fails to reach the operating line would raise questions about spending. Early reads on the CloudSurfer 3 rollout to run specialty stores in October, and the doubled spring-summer 2027 order book, could help explain why management sees the wholesale slowdown as temporary.
Sentiment has turned more bearish than it was ahead of the last report, yet the shares have gained 12.4% since then while the S&P 500 fell 2.9%. The stock has rallied from a post-earnings low of $26.37 to $35.52, within about 2% of its post-report high of $36.08, putting it close to a breakout. It still sits just below its 200-day moving average and beneath last quarter's range, which topped out above $41. That suggests a recovery is under way, but confidence has not been fully rebuilt.
Ultimately, the quarter comes down to one question: does the wholesale reset look finished? Clean channel inventory, steady DTC momentum and a reaffirmed outlook would let investors treat the third quarter as the low point. Another round of wholesale caution would turn a one-time adjustment into a trend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 | |
| Sep-28 | |
| Sep-28 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 |
