D-Wave's Q3 Test: Can Backlog And Bookings Steady A Stock Down 45% Ahead Of Q4?
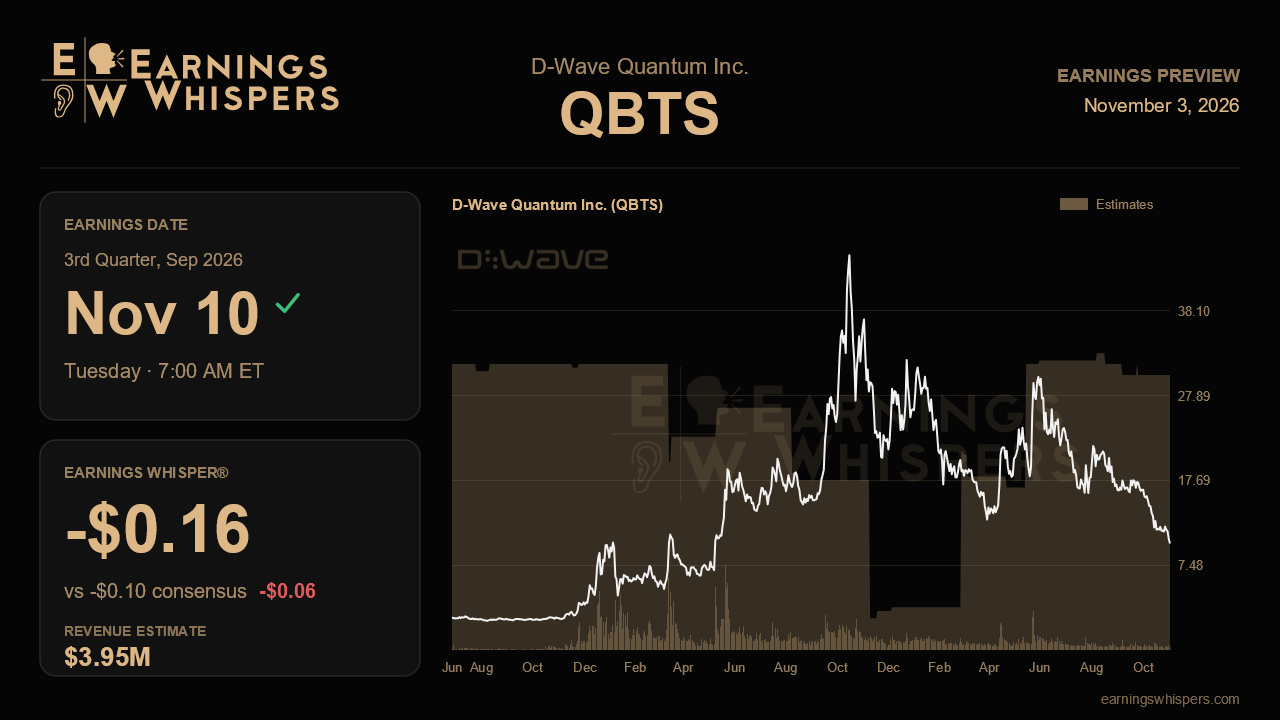
D-Wave Quantum heads into its third-quarter report with the market having already passed judgment. Since the last earnings call the shares have fallen 45.3%, compared with a 2.4% dip in the S&P 500. That call was arguably the company's most commercially encouraging yet, with a much richer customer mix, ballooning backlog and a peer-reviewed gate-model milestone. The stock now trades at $10.09, just pennies above its post-earnings low of $10.02 and roughly half its 200-day moving average of $19.24. The quarter will probably not settle the bull case on its own, because management has already said the year's revenue will land mostly in the fourth quarter. What it can do is show whether the groundwork for that fourth quarter is still holding.
Wall Street expects a GAAP loss of $0.10 per share on revenue of about $4.0 million. That revenue figure is up just 5.6% from $3.7 million a year ago, so this is a modest-growth quarter at best. The projected 75.6% improvement in per-share losses looks dramatic, but much of it reflects an easy comparison with last year's $0.41 loss and a much larger share count. It does not mean the cost structure has suddenly improved. The whisper number of a $0.16 loss is noticeably more pessimistic than consensus and matches last quarter's result. That suggests the more skeptical camp expects little narrowing in losses, which lowers the bar on earnings while making clear that nobody is counting on near-term operating leverage. The company has offered no formal quarterly guidance, so the call commentary is the best yardstick available.
The most important figures may sit below the revenue line. Last quarter, remaining performance obligations jumped to $40.7 million from $5.3 million a year earlier, and management said 57% of that is recognizable within 12 months. Bookings, however, were heavily front-loaded. The first half's $35.5 million came almost entirely from first-quarter deals, including the FAU system, and second-quarter bookings slumped to just $2.1 million. A rebound in bookings would support the claim that the sales pipeline grew 120% since December. So would a backlog that holds near its current level even as revenue is recognized. Another thin bookings quarter would suggest the first-quarter surge was a lumpy one-off rather than a new baseline.
Recurring cloud revenue is the other gauge of underlying demand. Subscription revenue rose 50% to $1.9 million in the second quarter, and production applications reached 37% of first-half cloud revenue. Customers such as AT&T, Optum and NTT Docomo moving into live production is the heart of the commercialization story. Evidence that those deployments are expanding, or that a seventh production application has arrived, would strengthen it. On the cost side, gross margin slid to 55.4% from 63.8% on higher personnel costs, and the adjusted EBITDA loss swelled 85% to $37.1 million. Further margin erosion without matching revenue growth would sharpen concerns about cash burn. Cash had already dropped to $546.2 million after the roughly $250 million QCI acquisition.
Sentiment has soured in step with the share price. Bearish readings deepened to 31.0% from 22.5% heading into the prior report. Combined with a stock pinned near its lows, that means expectations are subdued rather than stretched. Subdued expectations can work in a company's favor, but only if management gives investors something concrete to hold onto.
The central question is whether the two annealing system deliveries already pushed into the fourth quarter remain firmly on schedule. Management raised its system-sale cadence to two or three a year and then merely reaffirmed it. Any further slippage, or more revenue carried into 2027, would undercut the back-half thesis just when the stock can least afford it. A firm delivery timeline, recovering bookings and visible progress toward the 17-qubit gate-model target for 2026 would show the improving narrative is intact, even if the headline numbers stay small.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-17 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 |
