Diamondback Beats On Price And Cost Discipline, But Flat Oil Volumes And Rising 2027 Capital Temper The Setup
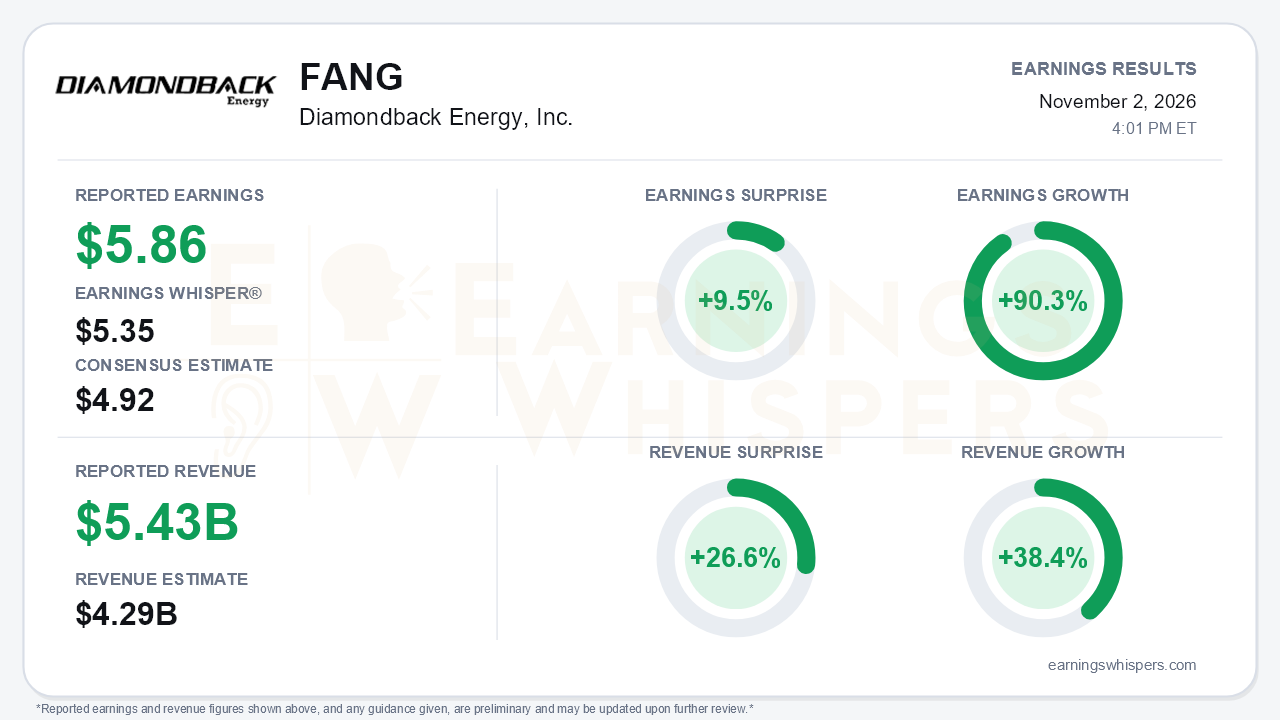
Diamondback Energy delivered a clear third-quarter beat. Adjusted earnings of $5.86 per share topped the $4.92 consensus by 9.5% and cleared the $5.35 Earnings Whisper number. Revenue of $5.431 billion beat the $4.29 billion consensus by 26.6%. Earnings grew 90.3% year over year and revenue rose 38.4%. Most of that came from a much richer commodity backdrop rather than a step change in the business. Realized oil averaged $87.30 per barrel, up from $64.60 a year earlier, while daily oil output rose only about 4% to 525 MBO/d. The quarter's real story is what happened beneath the price tailwind: cost execution, new technical levers, and capital that is quietly drifting higher.
The quality of the beat deserves scrutiny in both directions. On a sequential basis, the price tailwind actually faded. Realized oil fell from $96.82 in the second quarter, and the hedged combined price slipped from $52.90 to $50.01 per BOE. Oil volumes were essentially flat at 524,946 barrels per day versus 525,176 in Q2. That fits the neutral reading on sequential growth in the Earnings Whispers trend signals. Offsetting that, gas realizations swung from a negative $2.15 per Mcf in Q2 to a positive $1.12. Total cash operating costs held at $10.91 per BOE. GAAP EPS of $5.69 included a $182 million derivative loss, compared with $3.51 a year ago. Free cash flow reached $2.1 billion despite a $575 million working-capital drag, mostly from receivables. Cash capex, however, climbed to $1.026 billion from $774 million a year earlier.
The conference call reinforced a confident, steady growth posture. Management retired its stoplight framework and reaffirmed a green light, running a level-loaded 19-20 rigs and five frac crews. That program targets low-single-digit organic growth into 2027. The EBITDA beat was attributed to operating costs. Lease operating expense held just under $6 per BOE, and full-year guidance tightened to $5.95-$6.20. Gathering, processing and transportation guidance was cut to $1.30-$1.50, and the production-tax assumption fell to about 6.5% of revenue. The Barnett has progressed from delineation to roughly 20% of drilling activity, and management called it "one of the best investments we've ever made." AI-driven artificial-lift optimization is extending to roughly 1,000 more plunger-lift wells within months. A surfactant enhanced-recovery program will receive $50-$100 million, with recovery factors seen rising from about 10% to 11% within a couple of years.
Guidance moved up, but so did spending. Full-year oil production guidance rose to roughly 524 MBO/d from 522+, and total output to about 1,015 MBOE/d from 1,000+. Capital also increased, to $3.95-$4.00 billion from about $3.9 billion. Fourth-quarter oil guidance of 518-528 MBO/d implies flat production on a lighter completed-footage quarter. Bears have legitimate ammunition here. Management indicated that 2027 capex at $100 oil would likely run "a little higher" than the Q4 high end of about $1.05 billion per quarter, citing a somewhat inflationary cost environment. That compares with a $1.0-$1.1 billion range discussed last quarter. A cash tax rate above peers is another headwind. Higher Waha prices add optionality from gassier inventory, but gas-weighted growth would require more midstream control and capital.
Capital returns were measured relative to cash generation. Diamondback raised its base dividend 7.3% to $1.18 per quarter and repurchased $251 million of stock at about $186 per share. Total third-quarter return of capital was $582 million against $2.15 billion of adjusted free cash flow. Cash also went to acquisitions, debt reduction, and a 7.5% stake in the Solitude Pipeline. Standalone net debt fell to $10.4 billion, though consolidated net debt rose to $12.8 billion as Viper borrowed.
Investor sentiment improved modestly, from -0.049 to -0.016, but remains slightly negative. Investors appear less skeptical without being enthusiastic. Shares have gained 5.6% since the open following the August report, to $199.74, and sit about 5.3% above the 200-day moving average of $189.70. Most Earnings Whispers trend readings are positive, with sequential growth the neutral exception. That pattern matches a stock that has firmed alongside commodity prices while volumes plateau.
The bottom line is that Diamondback paired a decisive, largely price-driven beat with genuine operational progress: lower costs, a scaling Barnett program, and technology and recovery upside that strengthen the long-term inventory story. The tension is that oil volumes have stalled sequentially while capital intensity is rising into 2027. Future upside will lean more heavily on execution and commodity prices than the headline beat suggests.
Read our earnings preview for Diamondback Energy, Inc.: https://www.earningswhispers.com/article/FANG/21392
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 |
Diamondback Energy Lifts Production Targets Again as Revenue Grows
FANG -5.82%
The Wall Street Journal
|
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 |
