Pfizer Beats And Raises Again As Launch Growth Accelerates, But 2027 Patent Cliff Still Shadows The Rally
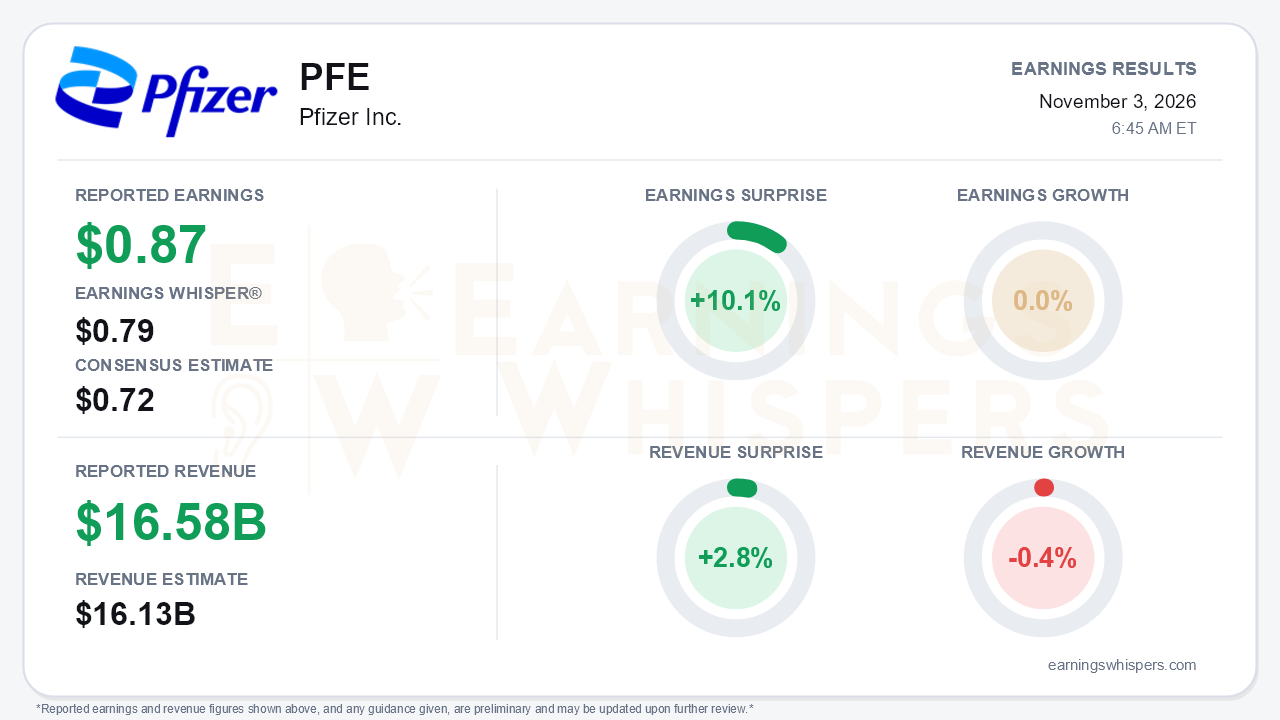
Pfizer delivered a clear beat-and-raise third quarter, and the more important development is how the business is moving rather than the year-over-year comparison. Adjusted EPS of $0.87 topped the $0.72 consensus by 10.1% and cleared the $0.79 Earnings Whisper number. Revenue of $16.58 billion beat the $16.13 billion consensus by 2.8%. On a year-over-year basis, though, the numbers look static: earnings were flat at 0.0% growth and revenue slipped 0.4%. The central tension is that sequential momentum is plainly improving while the company heads toward a heavy 2027 exclusivity and pricing reset that a strong quarter does not resolve. Quarterly revenue climbed from $14.5 billion in Q1 to $15.0 billion in Q2 to $16.6 billion, and adjusted EPS rose from $0.75 to $0.77 to $0.87.
The quality of the beat deserves a closer look, and on balance it holds up better than the flat headline suggests. Flat adjusted EPS absorbed a $650 million acquired IPR&D charge tied to the Innovent deal, worth roughly $0.10 per share. It also absorbed an adjusted tax rate of 14.0%, up from 7.9% a year ago. Underneath, COVID products remain a drag. Paxlovid fell 63% and Comirnaty 29%, yet non-COVID revenue grew 7% operationally. Launched and acquired products grew 32% to about $3.8 billion. Padcev rose 55%, Lorbrena 43%, Nurtec 33% and the Vyndaqel family 12%. The caveat is Eliquis. Its 25% operational gain was driven primarily by higher U.S. net price from lower rebates and favorable channel mix, not just volume. That kind of contribution is harder to extrapolate, especially with international Eliquis exclusivity ending at the end of 2026. On a GAAP basis, diluted EPS fell to $0.56 from $0.62.
The call reinforced that the growth engine is broadening. Launched and acquired product growth has stepped up from 22% in Q1 to 27% underlying in Q2 to 32% now, and legacy Seagen U.S. growth accelerated to 39%. Adjusted gross margin edged up to 77% from 76% in each of the first two quarters, helped by mix. Profitability below the gross line is a different story. Adjusted R&D rose 18% on oncology and obesity spending, and adjusted operating margin of 36% remains below Q1's 38%. Analysts pressed on combined SG&A and R&D of roughly $24-25 billion, a level similar to 2022, so bears have legitimate ammunition on cost discipline despite a cumulative savings target of about $9.7 billion. Management's tone was noticeably more assertive. Executives contrasted last year's policy anxiety with current stability, challenged Street models on Nurtec and Elrexfio, and reiterated the high-single-digit 2028-2033 revenue growth aspiration.
Guidance now carries real weight. Full-year revenue guidance rose $1.5 billion at the midpoint to $62-64 billion, the second consecutive increase. Adjusted EPS guidance moved to $2.95-3.05 from $2.80-3.00 despite the Innovent charge, while the COVID revenue expectation stays at about $4 billion. The pipeline added credible catalysts:
- a second positive Phase 3 for Elrexfio;
- encouraging ESMO data for atirmociclib and the PD-1xVEGF bispecific;
- approval of ecnoglutide in China for type 2 diabetes;
- EMA validation of the Lyme vaccine filing;
- FDA label expansions for Talzenna and Tukysa.
The offsets are equally concrete. The MEVPRO-1 readout slipped to roughly February 2027, and the amylin study was downsized. Prevnar fell 10% on lower vaccination rates and adult share erosion. Business development capacity has shrunk to about $6 billion. For 2027, management flagged U.S. exclusivity losses for Ibrance and Xtandi, IRA price setting on two products, and changes from Most-Favored-Nation pricing and the 340B rebate model. Leverage of 2.6x is now below target but is expected to stay around current levels through the patent-expiration period, and no buybacks are planned this year.
The market had already moved ahead of this report. Shares rose 22.5% from the post-Q2 open to $30.67, sit 14.4% above the 200-day moving average, and entered earnings just 1.2% below a 52-week high of $31.04 set the day before. Investor sentiment improved from -0.37 to -0.24, a meaningful gain but still net negative. Investors appear to be leaning toward the improving story without fully embracing it. Earnings Whispers trend signals are largely positive, with price, sequential growth and momentum all pointing upward. Still, with the stock near the top of its range, the beat-and-raise is partly a validation of a move that has already happened.
The bottom line is that Pfizer produced a genuinely better quarter than flat year-over-year growth implies: accelerating launch revenue, a second guidance raise and a deepening late-stage pipeline. The open debate has shifted from whether the post-COVID base can grow to whether new products and cost savings can outrun the 2027 exclusivity and pricing headwinds. This report strengthened the bull side of that debate, but it did not settle it.
Read our earnings preview for Pfizer Inc.: https://www.earningswhispers.com/article/PFE/21503
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 5 hours | |
| 6 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 11 hours |
Pfizer Hikes Guidance On Solid Third Quarter, Names Company Vet As New CFO
PFE
Investor's Business Daily
|
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours |
