Booking Holdings Clears The Whisper On Broad Q3 Acceleration, But A Steep Q4 Slowdown And Fading Margin Ambitions Dominate
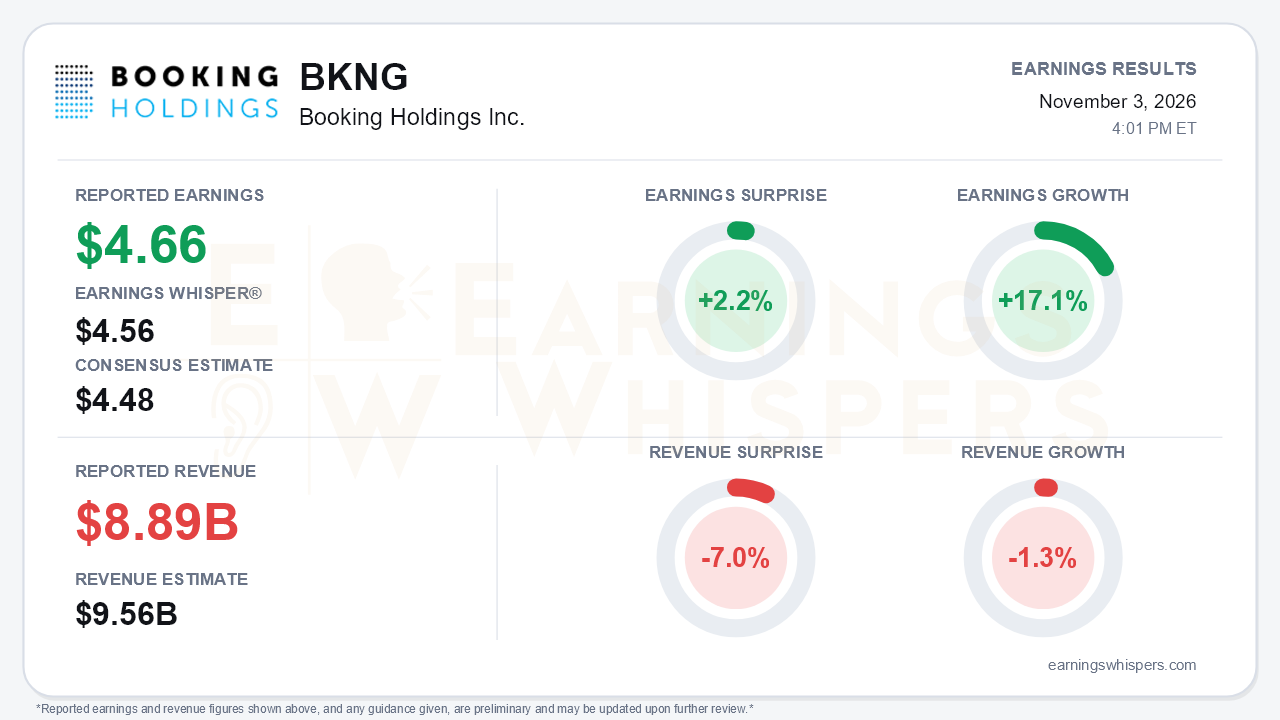
Booking Holdings delivered the kind of third quarter that would normally settle nerves. It then issued a fourth-quarter outlook that explains why investors had been selling the stock for three months. Adjusted EPS of $4.66 beat the $4.48 consensus by 2.2% and topped the $4.56 Earnings Whisper number. Earnings grew 17.1% year over year, an acceleration from 15% growth in the second quarter. Room nights rose 7%, ahead of a 3-5% guide and a 5% pace in Q2. Gross bookings grew 10%, or 11% in constant currency, against a 4-6% guide. That is the central tension: Q3 marked a peak, while management's Q4 guidance points to a sharp slowdown.
The headline revenue figures need explanation. Reported revenue of $8.893 billion fell 1.3% year over year and missed the $9.56 billion consensus by 7.0%. On the measure management emphasizes, the quarter looked very different. Adjusted Revenue grew 9%, or about 10% in constant currency. The quality of the earnings beat also deserves scrutiny. GAAP net income declined 1% and adjusted net income rose 8%, yet adjusted EPS climbed 17% and GAAP EPS 7%. A meaningful share of per-share growth came from a smaller share count rather than profit growth. Repurchases totaled $2.1 billion in Q3, down from $3.7 billion in Q2. Free cash flow fell to $1.1 billion from $3.6 billion, which management attributed mainly to the seasonal unwind of deferred merchant bookings. Adjusted EBITDA rose 9% to roughly $4.6 billion, and margin edged up to 47.0%.
Beneath the totals, the business broadened. Alternative accommodation room nights grew 7%, up from 4% in Q2, and listings growth accelerated to 9%. Flight tickets jumped 19% versus 4%. Attraction tickets rose 24%, and connected-trip transactions grew close to 20%. Merchant mix climbed to about 75% from 73%. There is a cost to that mix shift: flights are lower-yield, and adjusted revenue as a share of gross bookings slipped about 15 basis points. The AI story also moved from aspiration toward measurable results. Users of the Penny and Agoda AI assistants convert at roughly twice the rate of non-users. Agoda AI users carry about 20% higher booking value. Booking.com daily AI search visitors rose tenfold quarter over quarter. LLM referrals are accelerating but remain well under 1% of Booking.com room nights.
The forward picture is where bears have legitimate ammunition. Management said global demand moderated late in Q3, led by international travel. October was then hit by Middle East disruption, elevated airfares and localized unrest in parts of Europe. The Q4 guide calls for:
- room nights up just 1-3%;
- gross bookings up 2-4%, or 4-6% in constant currency;
- adjusted revenue up 0-2% reported, or 2-4% in constant currency.
That outlook comes against the toughest prior-year comparison and includes a roughly 2-point currency headwind. The full-year outlook was held at high-single-digit gross bookings growth and low-to-mid-teens EPS growth, not raised. That pattern follows successive trims since early in the year. Full-year EBITDA margin is now expected to be stable, down from about +50 basis points initially and +0-25 basis points in Q1, as Q4 investment spending runs elevated. Offsetting catalysts include:
- transformation savings tracking toward a $650 million run-rate in 2027;
- a combined B2B unit launching January 1, likely with separate disclosure;
- Meta Muse partnerships for OpenTable and Agoda;
- first-half 2027 on-the-books bookings that management described as healthy.
Regulatory uncertainty in the EU and UK could slow AI-agent adoption. Management said it has seen no benefit yet from Google's DMA changes.
The market had already priced in much of this caution. As of the pre-report snapshot, shares were 26.0% below the open following the August report. They sat 13.0% under the 200-day moving average and 29.3% beneath the late-August inter-earnings high of $217.32. The stock entered earnings just 5.1% above its October 28 low of $146.28, near the bottom of its quarterly range. Investor sentiment swung from modestly positive at 0.169 to slightly negative at -0.046, a meaningful deterioration rather than outright pessimism. Earnings Whispers price and AVWAP trend readings remain negative. The setup is therefore more complicated than the surprise implies: a stock this washed out may have already absorbed a soft guide. It has not been given a reason to believe the slowdown is temporary.
The bottom line is that Booking showed real operating strength in Q3: broad vertical acceleration, a clean beat against guidance and early evidence that AI lifts conversion. Investors, however, will trade on Q4 guidance implying near-flat adjusted revenue, a shelved margin-expansion target and a full-year outlook that is merely holding. Until demand stabilizes and the healthy early-2027 bookings translate into reaccelerating growth, the strong quarter reads as a high-water mark rather than a turning point.
Read our earnings preview for Booking Holdings Inc.: https://www.earningswhispers.com/article/BKNG/21553
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 3 hours |
Booking Stock Falls After Mixed Earnings Report. Here Are The Numbers To Know.
BKNG
Investor's Business Daily
|
| 4 hours | |
| 4 hours | |
| 4 hours | |
| Nov-02 | |
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 |
AI Agents Are a Threat to Travel Businesses. Airbnb Could Still Be a Winner.
BKNG
The Wall Street Journal
|
