Duolingo's User Surge Clears The Whisper, But Paid Subscribers And Q4 Profits Still Trail The DAU Story
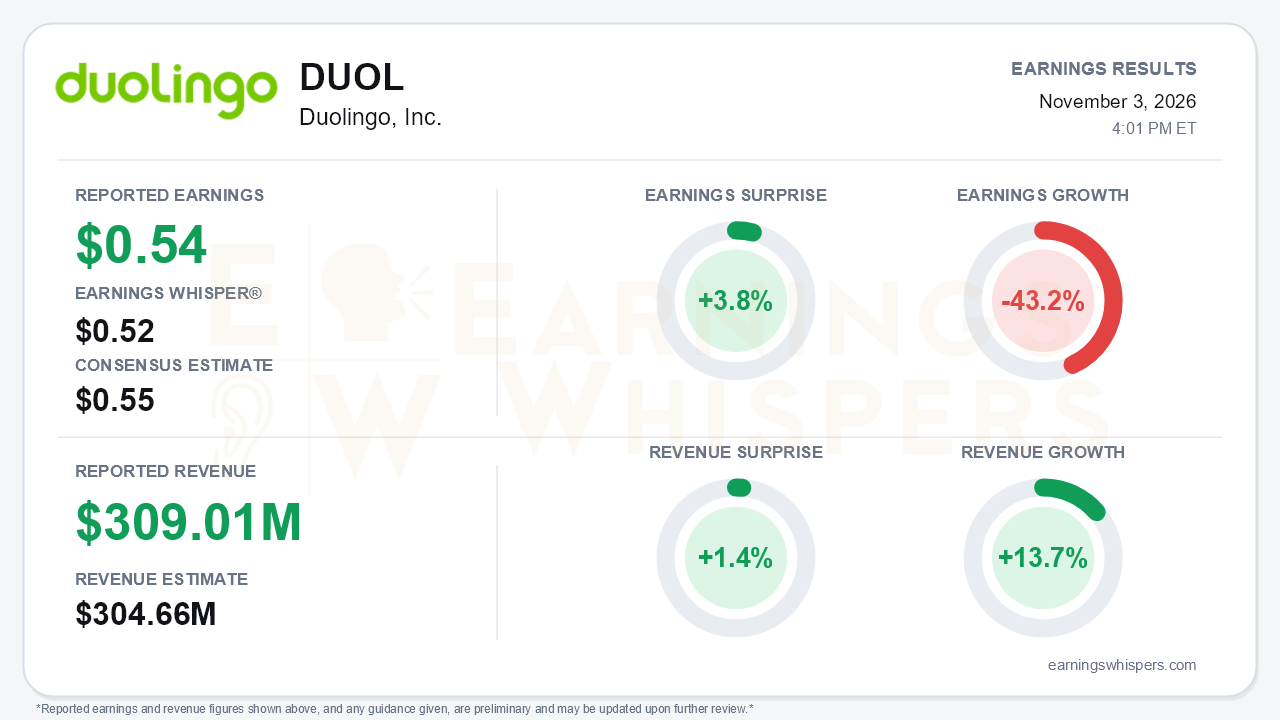
Duolingo's third quarter was a split decision on earnings and a clear win on users. The company earned $0.54 per share, beating the $0.52 Earnings Whisper number by 3.8% but landing a penny below the $0.55 consensus. Revenue of $309.01 million topped the $304.66 million estimate by 1.4% and grew 13.7% year over year. Earnings, however, fell 43.2% from a year ago. The central tension is between engagement and monetization. Daily active user growth accelerated to 29%, while profits per share shrank and paid subscriber growth kept slowing. Management's 2026 bet on user growth is clearly working. The open question is how quickly that audience becomes revenue and earnings.
The quality of the quarter deserves scrutiny in both directions. On the positive side, nearly every operating target moved higher. Full-year bookings growth is now 12%, up from about 10.5% at the Q1 point and about 11% in Q2, putting it at the top of the original 10-12% range. Full-year revenue growth reached 18%, the top of the 15-18% range. The adjusted EBITDA margin target held at 26.5%, well above the roughly 25% framed at the start of the year. Gross margin hit a record, about two points better than planned, helped by stronger revenue and falling AI costs. On the other side, Q3 revenue growth of 13.7% runs below that full-year growth framing. The sharp year-over-year drop in EPS also shows that the user-first strategy has come at a cost. Part of that cost is an approximately $11 million bonus accrual tied to DAU targets.
The call made the acceleration look broad-based rather than promotional. DAU growth has climbed steadily from 21% in Q1 to 23% in Q2 to 29% in Q3. Management expects Q4 to be similar, against a full-year plan of about 20%. The improvement showed up in eight of the top ten countries, and most regions posted double-digit subscription bookings growth. Chess reached 10 million DAUs, up from about 7 million in Q4 of last year, and management called it under-monetized with low-hanging fruit. Gaming partnerships with Supercell's Brawl Stars and Eggy Party are bringing in millions of users who retain well. Execution speed is also rising. A/B test volume grew about 90% while headcount rose about 10%, as internal AI tooling lets non-engineers ship experiments.
The most consequential product decision is the sunset of Duolingo Max. Its AI video call feature now goes to all Super subscribers, roughly ten times as many users. That move was made possible by inference costs falling from about 30 cents to under 1 cent per call. It should strengthen the value of the core paid tier, but it carries two near-term costs. Management expects gross margin to dip about a point sequentially in Q4. It also flagged possible cannibalization as Max individual subscribers shift to the Super Family plan. Bears have other legitimate ammunition:
- Paid subscriber growth is still decelerating, and management only expects a bottom in a couple of quarters.
- The ads business was flattish.
- Super Light tier tests were not "home runs."
- Q4 adjusted EBITDA is guided roughly flat year over year at about $84 million, a 26.1% margin, as bonus payouts and investment outpace revenue.
- There is no 2027 guidance.
The forward catalyst is management's explicit pivot toward monetization in 2027. Planned levers include in-app purchases, avatar suits, longer free trials and higher-quality direct ads, all intended to protect the free experience. Q4 bookings are guided to 13% growth, slightly ahead of the prior plan. Paid marketing is now profitable and makes up about 60% of more than $100 million in non-compensation marketing spend. That gives the company a lever it can push harder as monetization improves.
Investor expectations entered the report skeptical but less so. Earnings Whispers sentiment improved from -0.45 to -0.34, still negative but meaningfully better. Price action reflects that ambivalence. Shares hit their inter-earnings low of $112.02 on the first trading day after the August report, then rallied to $167.38 by early September. By November 2 they had given back much of that move, closing at $135.27, 19.2% below the high and just 4.0% above the post-report open. The stock sits 9.1% above its 200-day moving average. Price, sequential growth and momentum trend readings are positive, while AVWAP remains negative, consistent with a stock that has stabilized but not fully regained its September highs.
The bottom line is that Duolingo delivered the audience growth investors have been waiting for and pushed full-year targets to the top of their ranges. It has not yet shown that the user surge is translating into faster paid subscriber growth or rising earnings. EPS fell sharply, Q4 profits are guided flat, and 2027 is unguided. Investors should weigh the operating momentum favorably. The real test is whether next year's monetization push can close the gap between 29% DAU growth and low-teens bookings growth without eroding the free experience behind it.
Read our earnings preview for Duolingo, Inc.: https://www.earningswhispers.com/article/DUOL/21567
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 6 hours | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 |
