Block Beats And Raises Again As Margins Hit A Record, But Cash App And Lending Growth Keep Slowing
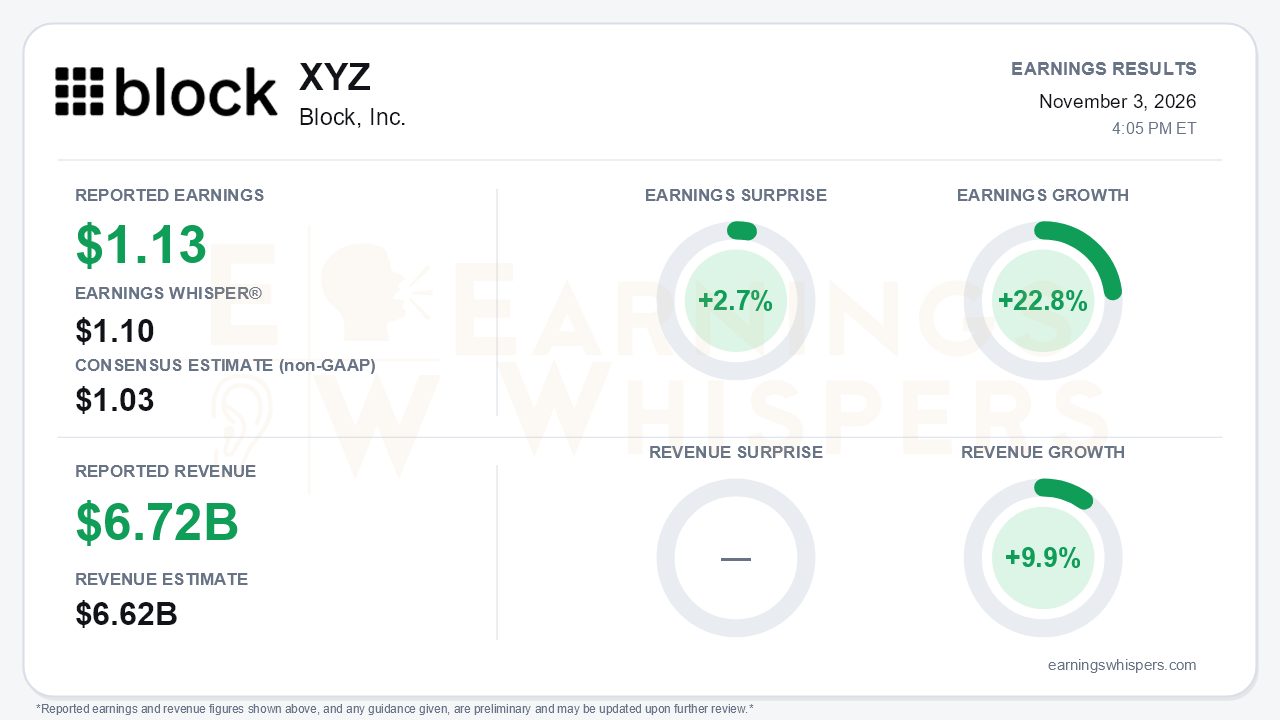
Block delivered its fourth consecutive beat-and-raise, and the profit story is now running well ahead of the top line. The company reported third-quarter earnings of $1.13 per share on revenue of $6.719 billion. That topped the $1.03 consensus and the $1.10 Earnings Whisper number, a 2.7% surprise. Revenue beat the $6.62 billion consensus by 1.5%. Earnings grew 22.8% year over year and revenue grew 9.9%. The headline is clean. The more important development is that Block is turning slowing gross profit growth into accelerating profitability, and it is betting investors will accept that trade. That is the central tension.
The press release itself was only a pointer to materials on the investor relations site, so the operating detail comes from the call. There, the margin trajectory is hard to argue with. Adjusted operating income rose 92% to $923 million, a record 29% margin, up from 25% in Q1 and 27% in Q2. Fourth-quarter guidance calls for a 30% margin.
Full-year guidance moved up again:
- Gross profit to $12.626 billion, or 22% growth, from $12.2 billion at the start of the year.
- Adjusted operating income to $3.519 billion.
- Adjusted EPS to $4.15, up 75%.
The quality of the raise deserves scrutiny. The $116 million gross profit increase was smaller than prior raises. Fourth-quarter gross profit growth is guided to only better than 15%, and Earnings Whispers characterizes the guidance as in line. Management raised the year while signaling a sharp exit-rate slowdown. Those two facts are both true, and investors should hold them together.
Beneath the totals, the two engines are moving in opposite directions.
Square is accelerating:
- Gross payment volume grew 14%, its strongest pace since Q1 2023.
- Food and beverage, mid-market and international are each growing roughly 20% or more.
- The ISO partner channel doubled to more than 400 from 200-plus in Q2, and new sellers via ISOs rose 90% sequentially.
Cash App is decelerating:
- Gross profit growth slowed from 38% to 31% to 27% across the year.
- Consumer lending origination growth fell from 82% to 59% to 40%.
- Originations per customer fell 7% sequentially during the shift from four- to six-week Borrow products.
- Aggregate loss rates are rising as the mix moves toward higher-fee, higher-loss products.
- Inflows per active slowed to about 6% from 9% and 10%, and management acknowledged primary banking actives growth moderated.
Total gross profit growth has stepped down from 27% to 25% to 22%. Bears have legitimate ammunition here.
Management's answer was a preliminary 2027 outlook that arrived better than expected and, by its account, a year ahead of its Investor Day schedule on operating income. The outlook calls for:
- At least 15% gross profit growth.
- An adjusted operating margin of about 32%.
- Roughly 30% growth in adjusted operating income.
Other supports for the growth story:
- The Borrow target variable profit margin was lifted to 2.8% from 2%, with a 37% return-on-capital target.
- Cash App actives reached 60 million, up 4% and the fastest pace since mid-2024, with at least low single-digit growth expected in 2027.
- Neighborhoods scaled to roughly $5 billion in annualized seller GPV, about fivefold since June, ahead of a Cash App-wide rollout in early 2027.
- First AI revenue from BuilderLab and Buzz is expected in Q4, with an event scheduled for November 10.
The risk is that management plans to reinvest profit upside into these nascent bets, whose monetization is unproven. Tough Borrow and Cash App Green comparisons also loom. Hardware and memory cost inflation flagged in Q2 remains a background concern.
The market had not been rewarding the raises. Shares entered the report at $77.08, down 8.0% from the open after the August report. They sat 11.3% below the 52-week high of $86.92 set on August 27 and 6.6% above the October 1 low of $72.28. The stock remains 8.3% above its 200-day moving average, so the longer-term trend has not broken, but the post-August enthusiasm has largely faded. Investor sentiment improved modestly, moving from slightly negative at -0.0485 to slightly positive at 0.0441. That is a shift in tone rather than a surge in conviction. The Earnings Whispers trend readings lean favorable, with sequential growth and momentum positive, though the AVWAP trend remains negative and reflects the stock's retreat from its summer high.
The bottom line is that Block is executing a credible margin expansion story, with record profitability, a reaccelerating Square and a 2027 framework that pulls targets forward. However, the growth that funds it is slowing. Cash App gross profit, lending originations and engagement metrics all decelerated again, and fourth-quarter gross profit guidance implies another step down. The beat and raise strengthen the earnings case. Whether the shares recover their summer highs likely depends on investors believing that Neighborhoods, AI and Borrow economics can stabilize top-line growth before margin gains run their course.
Read our earnings preview for Block, Inc.: https://www.earningswhispers.com/article/XYZ/21647
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-19 |
