Hut 8 Misses On EPS And Revenue As AI Campuses Stay On Track And Management Turns More Cautious On Cash
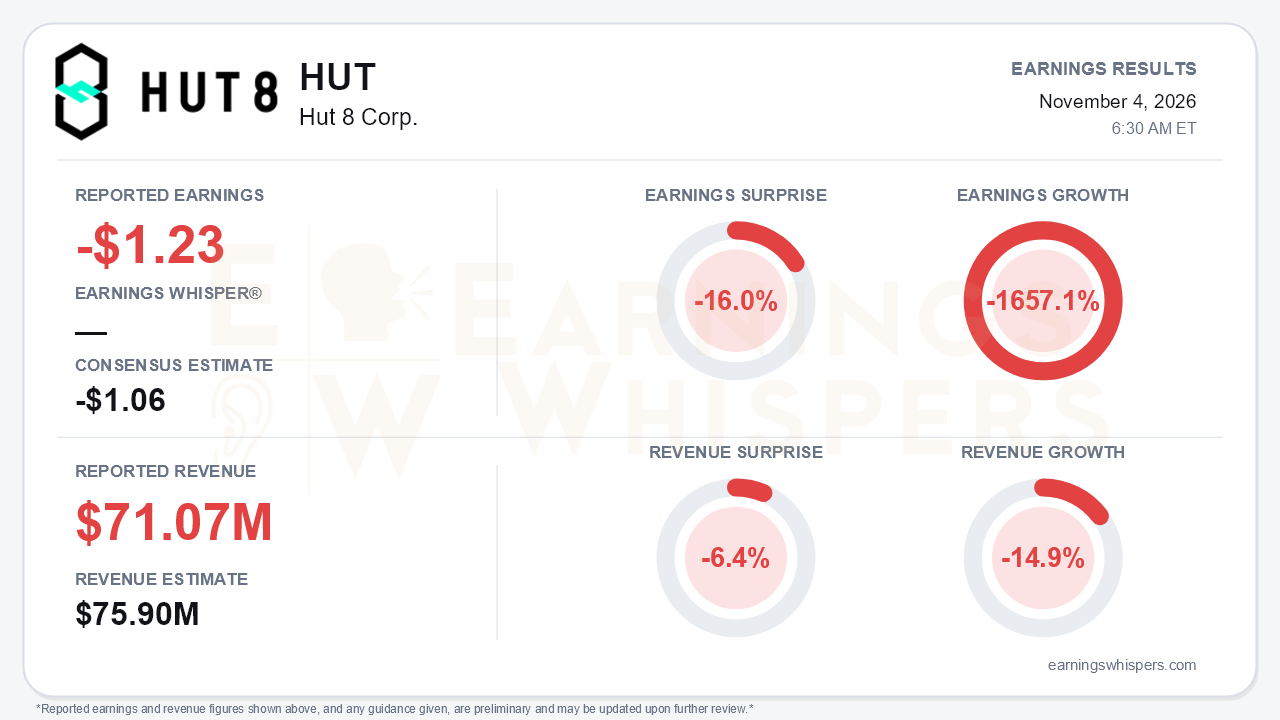
Hut 8 Corp. (NASDAQ: HUT) missed on both lines in the third quarter. It reported a loss of $1.23 per share against a consensus estimate of -$1.06, a 16.0% shortfall, and earnings fell 1657.1% year over year. Revenue of $71.07 million missed the $75.9 million consensus by 6.4% and declined 14.9% from a year ago. The quarter was mostly about building and defending the balance sheet. River Bend and Beacon Point construction remains on schedule, but there was no new lease signing, legacy revenue continued to run off, and management sounded noticeably more guarded about capital. That shift in tone is the central tension in the report.
The headline figures need careful reading. On a GAAP basis, Hut 8 reported net income of $189.5 million, or $131.1 million attributable to Hut 8. That result was driven by $413.8 million of primarily unrealized gains on digital assets. Strip out Bitcoin price appreciation and the cost structure looks much heavier:
- General and administrative expense jumped to $99.6 million from $25.9 million, including $64.7 million of stock-based compensation.
- Interest expense rose to $105.5 million, against $61.8 million of interest income, reflecting the carrying cost of construction-period debt.
- A $62.8 million loss on derivatives and other financial liabilities added further drag.
The Earnings Whispers loss per share reflects that underlying burden rather than the mark-to-market windfall. Adjusted EBITDA, which excludes Hut 8's digital-asset gains, was a brighter spot at $33.0 million, up from $10.4 million in Q2 and $30.5 million a year earlier.
The revenue picture explains much of the call's caution. Sales fell from $74.9 million in Q2, largely by design. The Far North sale and the exit from Traditional Cloud shrank the Power and Compute lines. Digital Infrastructure revenue also dropped to $1.4 million from $5.1 million a year ago because of churn. Compute cost of revenue rose to $28.0 million from $22.0 million, compressing segment margin from roughly 66% in Q2. Cash G&A climbed to $34.8 million from $24.8 million in Q2 and $19.5 million a year earlier.
The sources conflict on the Beacon Point Phase 2 lease. The release leads with it as a quarterly highlight: 352 MW and roughly $9.8 billion of base-term value, fully commercializing the campus. The call analysis, however, shows contracted capacity unchanged at 949 MW and about $27 billion. It treats Phase 2 as a prior-quarter signing and characterizes Q3 as the first quarter without a new lease after back-to-back deals. The incremental Q3 change it notes is an extension of the Phase 2 term from 15 to 17 years.
The forward story still has real substance. About 1.3 GW moved into exclusivity, bringing the total to 3,180 MW, compared with only 200 MW added in Q2. Management also disclosed a geographically diversified pipeline led by MISO, PJM and SERC, with less than 5% in ERCOT. Hut 8 agreed to acquire two energized West Texas sites with up to 230 MW of capacity out of a Chapter 11 process for up to $180 million, with closing possible as early as Q4 2026. River Bend and Beacon Point Phase 1 are funded by non-recourse bonds, and management expects no equity issuance for either. Key upcoming milestones:
- A Beacon Point baseload classification decision expected around December 17.
- First data hall delivery at River Bend in Q2 2027.
Bears have legitimate ammunition, though. Phase 2 financing is not done, and management flagged possibly higher financing costs alongside industry-wide build-cost inflation. The Texas governor's race and proposed data center guardrails add regulatory uncertainty around Beacon Point. Liquidity has also tightened. Unrestricted cash fell to $156.9 million from $233.6 million. Unencumbered Bitcoin dropped to about 1,361 BTC from roughly 5,600 after Q1, after Bitcoin sales funded the full $250 million buyback. The board lifted the repurchase authorization to $1.0 billion, yet management's 'cash will be king' language and deliberately slower buyback pace suggest that authorization is optionality, not a commitment. The new $1.07 billion revolver is undrawn and improves flexibility, but it does not replace contracted cash flow.
The market had already priced in a good deal of this. Shares entered the report at $63.75, down 38.4% since the open after the August report. The stock sat 22.6% below its 200-day moving average of $82.40 and just 18.3% above the inter-earnings low of $53.87 set on November 2. That low came after the stock peaked at $110.93 on the day of the prior report. Investor sentiment nonetheless became modestly more positive, rising to 0.205 from 0.138. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive while price and AVWAP remain negative.
The bottom line is that Hut 8's quarter preserved a credible long-dated infrastructure story but delivered a weaker near-term one. Operations are shrinking toward a transition, costs and interest carry are climbing, and management's tone has moved from expansion to preservation. Until Phase 2 financing, the baseload decision and Texas regulatory clarity are resolved, the stock is likely to trade on execution risk rather than on contract value.
Read our earnings preview for Hut 8 Corp.: https://www.earningswhispers.com/article/HUT/21709
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 9 hours | |
| 9 hours | |
| Nov-02 | |
| Oct-30 | |
| Oct-30 |
