SharkNinja Crushes Estimates And Raises Again, But Tariff Refunds Flatter The Margin Story And Q4 Profit Growth Slows Sharply
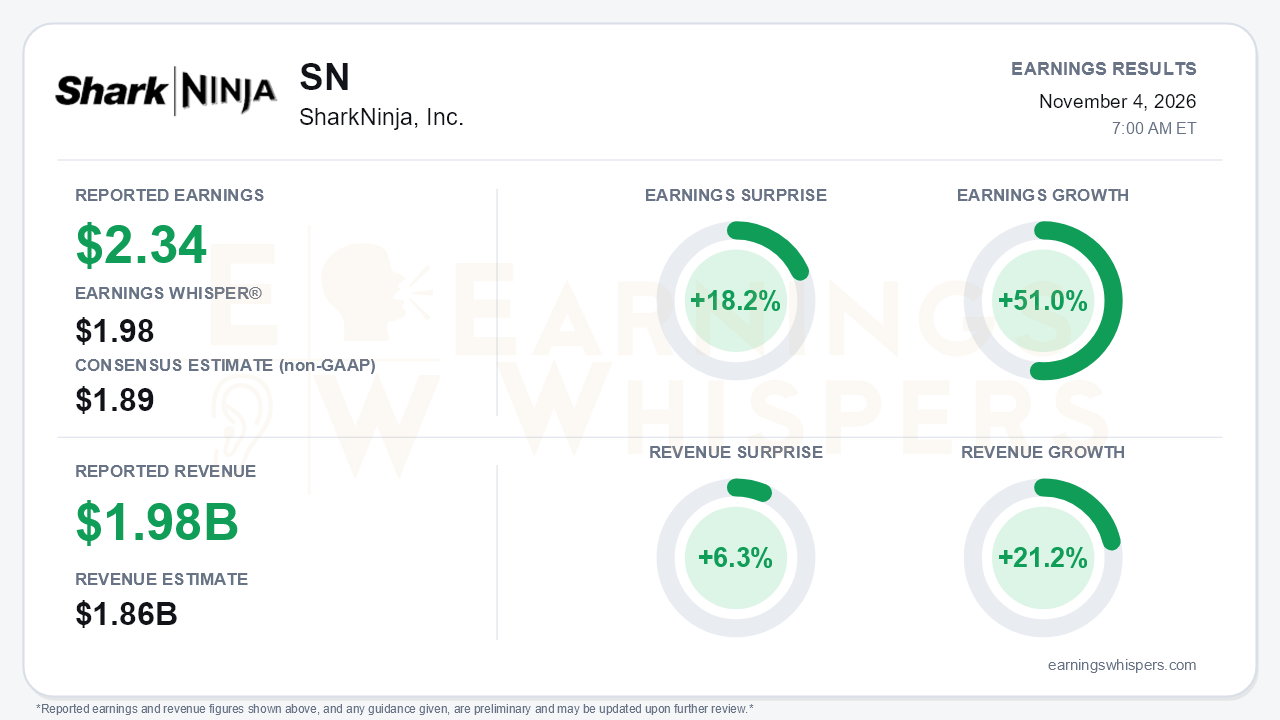
SharkNinja delivered the kind of quarter that resets expectations. Adjusted EPS of $2.34 beat the $1.89 consensus by 18.2% and cleared the $1.98 Earnings Whisper number. Revenue of $1.976 billion topped the $1.86 billion consensus by 6.3%. Earnings grew 51.0% year over year by Earnings Whispers' measure; the company cites 56% against its own $1.50 adjusted base. Sales rose 21.2%, the second straight quarter above 20% after Q1's 15.6%, and management raised full-year guidance for the third consecutive quarter. The central tension is that the quarter's extraordinary profitability leaned heavily on tariff refunds, while the guidance implies Q4 profit growth slows to a crawl.
The quality of the beat deserves scrutiny. GAAP gross margin jumped 910 basis points to 59.2%, and adjusted gross margin rose 560 basis points to 55.9%. Both figures were driven primarily by refund claims for duties paid under IEEPA. The company stripped the $109.6 million attributable to 2025 duties, net of $45.2 million owed to factory partners, out of adjusted results. However, the $134.3 million tied to duties expensed in 2026 stays in adjusted gross profit. That is consistent accounting, since those duties depressed earlier 2026 quarters, but it means the headline margin is not a run rate. Excluding refunds, Q3 gross margin actually fell about 100 basis points: SharkNinja absorbed commodity inflation and delayed price increases. Below the gross line, adjusted operating expenses rose to 34.4% of sales from 32.6%, ending five quarters of leverage. Adjusted G&A climbed 43%, and share-based compensation more than quadrupled to $42.0 million.
The top line itself needs no such caveats, and it improved broadly. Domestic sales grew 19.4%, up from 15.5% in Q2 and 8.4% in Q1. U.S. growth reached 20.8%, its best since late 2024. International rose 25.2%, and Latin American distributor markets posted a record quarter. Cooking and beverage surged 36.6% on the Ninja Luxe Café and Crispi. Beauty and home environment jumped 45.8%. Food preparation swung to 18.3% growth from a 3.3% decline in Q1. The soft spots were real but contained. Cleaning, still the largest category, grew only 4.1%, and U.K. growth slowed to 13.3% from roughly 19% in Q2. Updated guidance now calls for 18% to 19% sales growth, versus 16% to 17% previously and 10% to 11% in February. It also calls for adjusted EPS of $6.65 to $6.75 and adjusted EBITDA of $1.380 billion to $1.391 billion.
The forward picture is where bears have legitimate ammunition. Implied Q4 sales growth decelerates to roughly 17%, against tough social-commerce comparisons. Implied adjusted EBITDA growth is only about 9%, with adjusted gross margin down around 100 basis points as refund reinvestment slips from Q3 into Q4. The balance sheet also absorbed the growth. Cash fell to $487.8 million from $777.3 million at year-end, and inventories reached $1.43 billion. Receivables rose to $2.1 billion, and nine-month operating cash flow was just $107.4 million even with buybacks continuing. Management is positioning the inventory for holiday demand, which makes Q4 sell-through more consequential than usual.
Management's catalyst list was unusually deep. Ninja HydraSense marks SharkNinja's 41st subcategory, entering water filtration with a market sized at more than $6 billion. Filter subscription attach is running more than three times internal expectations. The company also committed to two more new subcategories in 2027. TikTok Shop is now live in 14 countries, double the count at Q2. AI-powered site search is lifting revenue per search visitor by a high-single-digit percentage. AI optimization of more than $1.5 billion in annual media and promotional spend targets a 2027–28 payoff. Tone escalated accordingly: CEO Mark Barrocas framed the company as a "Consumer Technology company operating at hyperscale" and said he has "never been more excited."
The market setup is more demanding than the surprise alone implies. Investor sentiment rose sharply, from a barely positive 0.08 at the prior report to 0.53, a substantial shift in expectations. Shares entered the report at $210.59, up 24.4% since the open after the August release. The stock sat nearly 47% above its 200-day moving average and just 2.6% below the 52-week high of $216.11 set on November 2. The Earnings Whispers trend signals are uniformly positive. Even so, a stock priced near its highs with enthusiastic sentiment leaves less room for a Q4 guide implying single-digit EBITDA growth.
The bottom line is that SharkNinja's demand engine is accelerating across regions and categories, and the guidance raise is credible on revenue. But the margin expansion is substantially refund-driven, and underlying gross margin and opex trends moved the wrong way in Q3. With the stock and sentiment already pricing in strength, the next test is whether holiday sell-through and 2027 pricing can carry profitability once the tariff windfall fades.
Read our earnings preview for SharkNinja, Inc.: https://www.earningswhispers.com/article/SN/21743
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
SharkNinja Crushes Third-Quarter Sales, Earnings Targets. Forecasts Bright Holiday Season.
SN
Investor's Business Daily
|
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 |
IBD 50 Stock SharkNinja In Buy Zone Ahead Of Pivotal Third-Quarter Earnings Report
SN
Investor's Business Daily
|
| Oct-26 |
