Nebius Must Show Its Billion-Dollar AI Deals Can Outrun Losses And A Street Above Guidance
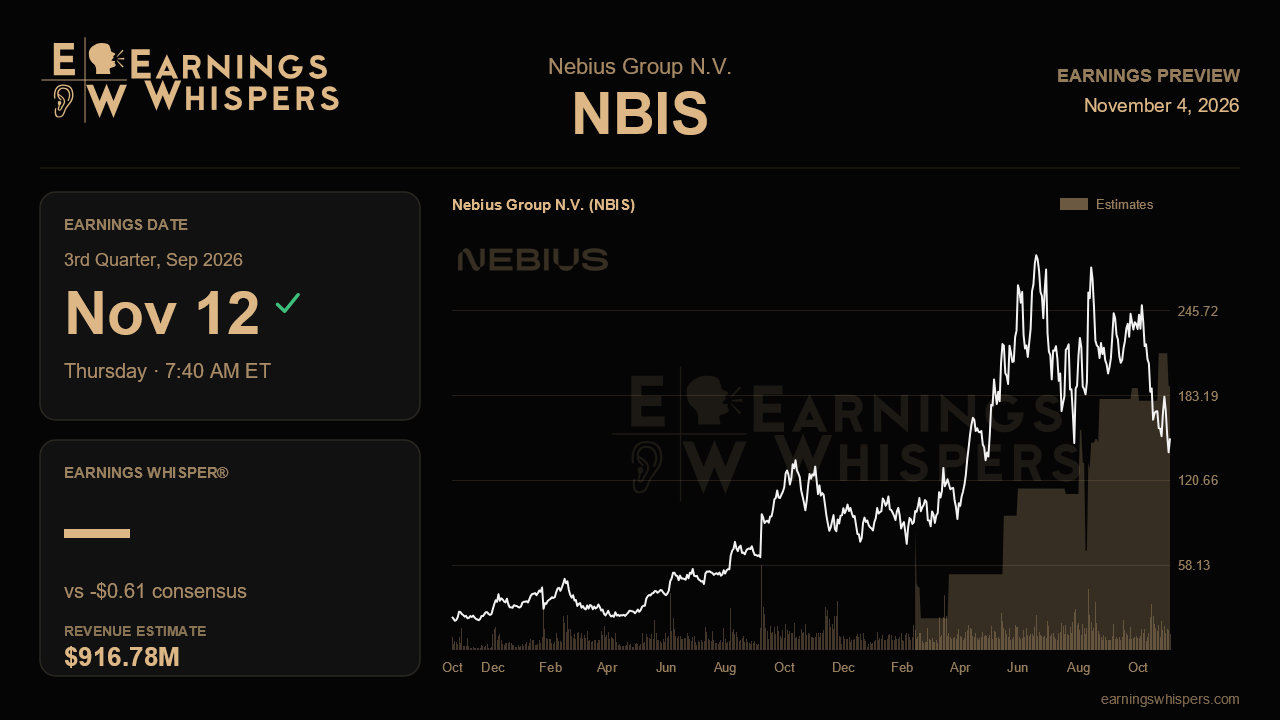
Nebius heads into its third-quarter report with a striking disconnect. On the last call, management described its business as stronger by nearly every measure: faster revenue growth, fatter margins, a broader customer roster and proof that it could raise prices. Since then the stock has fallen about 33%, trailing the S&P 500 by roughly 30 percentage points. The report, due before the open on November 12, has to settle whether the market is underestimating the operating story or correctly pricing the cost and financing risks behind it.
The headline numbers ask for a lot. Consensus calls for revenue of about $916.8 million, up roughly 527% from $146.1 million a year ago and about 57% above the $582.3 million reported last quarter. That sequential jump would be larger than the 46% gain in the second quarter, so analysts are counting on growth to keep speeding up. The bottom line moves the other way. The Street expects a loss of $0.61 per share, much wider than last quarter's $0.12 loss and the $0.39 loss a year earlier. That gap is the clearest sign that depreciation and financing costs on a huge buildout are arriving faster than profits on the revenue it supports.
Guidance adds another wrinkle. Management reaffirmed its 2026 revenue outlook of $3.0 billion to $3.4 billion rather than raising it, and full-year consensus of $3.48 billion sits above the top of that range. First-half revenue was about $981 million. If the third quarter lands near consensus, the fourth quarter would need roughly $1.5 billion just to reach the high end of guidance, and more than that to match the Street. Management explained the conservative stance by noting that the large deals signed in the second quarter come online late in the year and help 2027 more than 2026. A raise here would close that gap. Another plain reaffirmation would suggest analysts got ahead of the company.
The last call offers several checkpoints. The most important is whether the four competitive AI cloud contracts, each worth more than $1 billion and signed with customers including Reflection and Cohere, are turning into capacity on schedule. Those deals ended the company's earlier dependence on Microsoft and Meta. Their economics matter as much as their size: $20 million to $25 million of revenue per megawatt, a payback period under two years, and prepayments covering half or more of the related capex. Other things would support the pricing claims made last time:
- further growth from the $3 billion in annualized revenue reached at the end of June, measured against the $7 billion to $9 billion year-end target;
- the adjusted EBITDA margin staying near the 41% posted last quarter;
- more capacity auctions or short-term premium deals at the $40 million to $50 million per megawatt levels cited before.
Any slippage in contracted power against the newly raised 5 gigawatt target, or delays at the Vineland, New Jersey site after its switch to Bloom fuel cells, would undercut the deployment story.
Financing is the other swing factor. Nebius tapped its at-the-market program for the first time, raising about $2.8 billion at an average near $224 a share. It also arranged a $775 million asset-backed facility against what it describes as $40 billion of committed backlog. With the stock now near $152, further equity raises would be far more dilutive. Updates on the more than $9 billion of expected 2026 prepayments, the asset-light partnership model and debt costs will therefore weigh heavily alongside capex plans of $20 billion to $25 billion. Sentiment remains bearish, though slightly less so than before the last report. The stock trades well below its 200-day moving average of about $178 and only about 8% above its post-earnings low of $140.60.
In the end, the quarter will be judged on whether Nebius can show its higher-yielding contracts are coming online fast enough to justify full-year expectations above its own guidance, while funding that growth without leaning harder on its shareholders. Strong revenue plus a credible path to the top of the range would support the story management told last quarter. A reaffirmation paired with heavier losses would give the stock's skeptics more evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| 17 hours | |
| Nov-03 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 |
