Ondas Must Prove Its Steep Second-Half Ramp Is Real As Stock Sinks Toward Lows
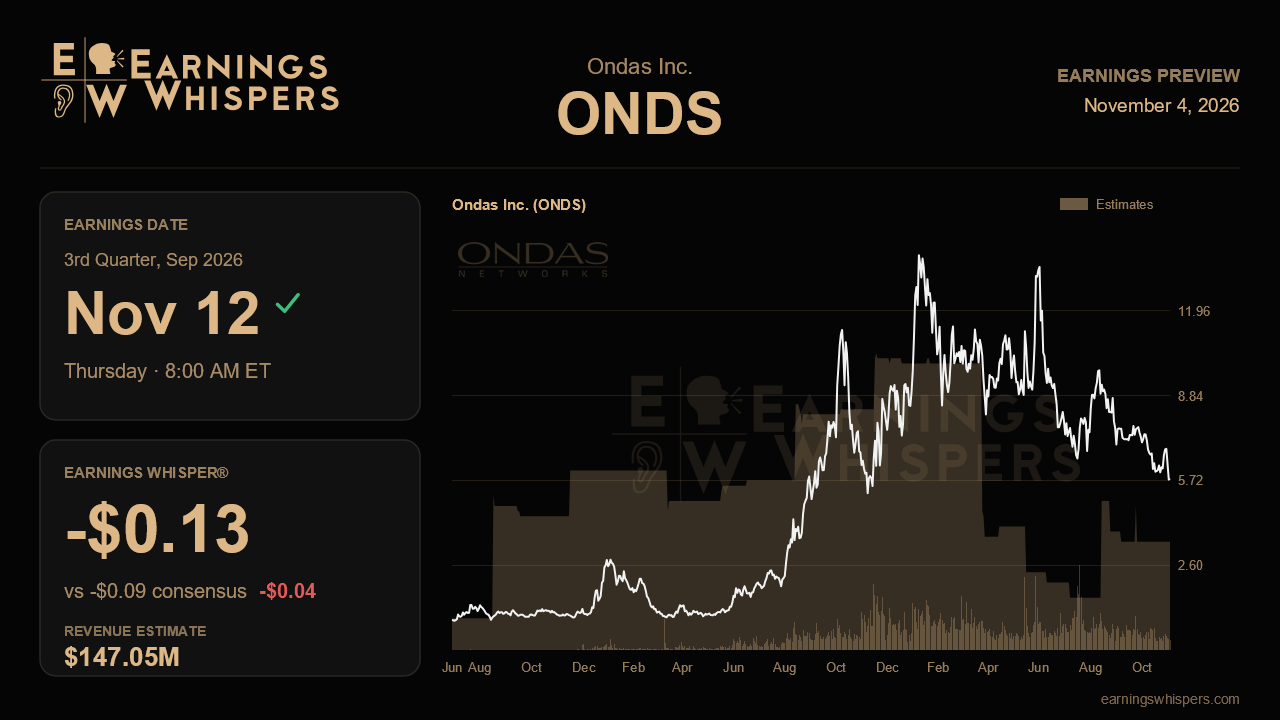
Few small-cap defense names have raised their outlook as aggressively as Ondas, and few have seen the market respond with such skepticism. Since its last report, when management lifted 2026 revenue guidance for the fourth straight quarter and declared its confidence had never been stronger, the stock has fallen about 35%, trailing the S&P 500 by roughly 33 percentage points. The third-quarter report, due before the open on November 12, is the first real test of whether the company's sharp acceleration story can survive contact with the numbers.
The Street is looking for revenue of $147.1 million, almost exactly the midpoint of management's $140 million to $155 million guide and a staggering 1,356% above the $10.1 million posted a year ago. Even sequentially, the bar is steep: hitting consensus requires roughly 75% growth from the record $83.8 million reported last quarter. Notably, the consensus figure has drifted down from around $157 million when the guidance was issued, so analysts have moved from the top of the range toward its center. On the bottom line, consensus calls for a non-GAAP loss of $0.09 per share, while the Earnings Whisper sits at a deeper $0.13 loss. That gap suggests the market is braced for heavier spending than published estimates assume, which matters for a company whose adjusted EBITDA loss ballooned to about $51 million last quarter.
Management described that $51 million loss as the peak, and this report should show whether that claim holds. Adjusted cash operating expenses jumped to roughly $93 million from about $37 million the quarter before, including about $29 million earmarked for growth. If revenue arrives near guidance while opex stabilizes, losses should narrow meaningfully and the front-loaded investment argument gains credibility. If expenses keep climbing, particularly with the Design and Cyber Hawk acquisitions now folded in after roughly $325 million was deployed, the peak-loss framing will look premature. Gross margin is the other swing factor. Management already warned that mix and excess capacity from acquired businesses would weigh on second-half margins after they slipped to 50.4%, so a modest decline is expected; a sharp one would raise questions about the quality of the growth.
The composition of revenue deserves as much attention as the total. Because acquisitions closed during the quarter, investors should look for evidence that organic demand is still carrying the load, as it did when pro forma organic growth ran near 85%. The most important tangible signal would be early volume shipments under the US Army Lethal Unmanned Strike contract, where roughly $240 million in orders were slated to begin shipping in the second half, along with initial IronStrike counter-drone deliveries. Updates on backlog, which jumped to $757 million, and on the $105 million in orders booked early in the quarter will show whether conversion is keeping pace with the ambitious $1 billion annualized run-rate target for the end of 2026. Confirmation that the operating platform remains on track for EBITDA profitability in the fourth quarter would also help.
Sentiment has soured noticeably, swinging from solidly bullish before the last report to slightly bearish now. The chart tells the same story: at $5.79, shares sit just above their post-earnings low of $5.72, well beneath the 200-day moving average near $8.98, and below the prior quarter's trough of $6.22. That depressed setup cuts both ways. Expectations embedded in the share price appear modest, but any stumble on the ramp could confirm the market's doubts.
Ultimately, the quarter hinges on execution rather than ambition. Ondas has repeatedly told investors that demand, backlog and pipeline are expanding faster than anyone expected. What it must now show is revenue landing inside the guided range, losses beginning to recede from their stated peak, and fourth-quarter guidance that keeps the $525 million to $550 million annual target intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 12 hours | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-10 | |
| Oct-09 |
