Applied Materials Brings Record AI Demand Into A Report The Market Has Stopped Trusting
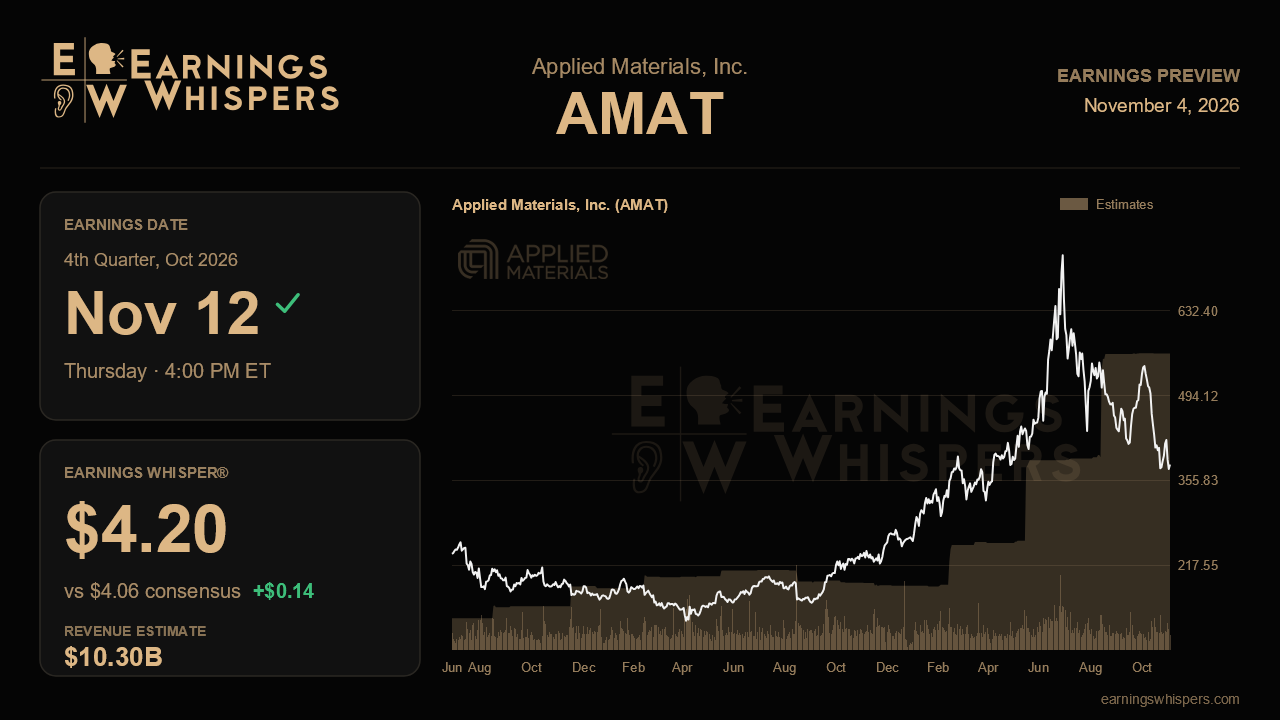
Applied Materials enters its fiscal fourth-quarter report with one of the widest gaps in large-cap tech between what management is saying and what the stock is doing. Three months ago the company posted record revenue, raised its industry growth outlook for the third straight quarter and described customer conversations stretching toward 2030. Since then the shares have fallen 23.5%, about 20 percentage points worse than the S&P 500. The question for Thursday after the close is whether the numbers can force the market to re-engage with that story, or whether investors are pricing in a peak that management has not yet acknowledged.
The bar is high in absolute terms. Analysts expect earnings of $4.06 a share on revenue of $10.30 billion, which would be growth of roughly 87% and 51% from a year ago. That is extraordinary for a company of this size. Management guided to $3.82 to $4.22 in EPS and $9.75 billion to $10.75 billion in revenue, so consensus sits slightly above the midpoint of both ranges. The whisper number of $4.20 is more demanding, landing near the top of guidance. In other words, the more engaged corners of the market expect a clean beat, not simply delivery against the plan. Hitting the midpoint would be a respectable result on paper and could still feel like a letdown.
The previous call gives a clear checklist. Management lifted its calendar 2026 outlook for packaging to more than 70% growth, put process diagnostics and control above 50%, raised services growth to over 20% and said China, which had been treated as flat for most of the year, should now grow in both 2026 and 2027. DRAM was the standout at a record level. Validation this quarter means seeing those segment trends hold up in the actual mix, along with a calendar 2027 framework that at least preserves the idea of another record year. Any softening in China language, or a less specific 2027 view, would undercut the most recent upgrades, because those were the incremental pieces of the bull case.
Margins are the second test. Gross margin reached a record 50.4% last quarter, the 13th consecutive year-over-year improvement, yet management guided the fourth quarter roughly flat because hiring and capacity ramp costs are absorbing volume leverage. The company added more than 1,500 manufacturing and support staff in a single quarter and plans to double quarterly output capacity by 2028. That is a large bet on durable demand. A margin that holds near 50% while revenue jumps would suggest the build-out is disciplined; a dip would invite questions about whether the company is spending ahead of orders. The coming 14-week first quarter, with its outsized expense step-up, and a tax rate rising to about 13% in 2027 add to the importance of how management frames next year's profit trajectory.
Sentiment has cooled to 19.8% bullish from 25.1% heading into last quarter, still positive but noticeably less enthusiastic. Technically, the stock is trading below its 200-day moving average of about $444 and sits only a few percent above its post-earnings low of $372.80, far beneath the $547 high reached after the last report. That positioning cuts both ways: expectations embedded in the price look depressed even as the published estimates remain lofty.
Ultimately, this report comes down to forward visibility. The current quarter is largely spoken for by guidance. What matters is whether management can show that the AI-driven order momentum, newer catalysts such as the Broadcom engagement in its EPIC program and the capacity expansion are translating into a 2027 outlook strong enough to justify the spending. If it can, the selloff looks like an overreaction. If the tone merely holds steady, the market may conclude the best growth rates are already behind it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 |
