Cisco's AI Super Cycle Faces Its First Test As Margins And A Sliding Stock Raise Doubts
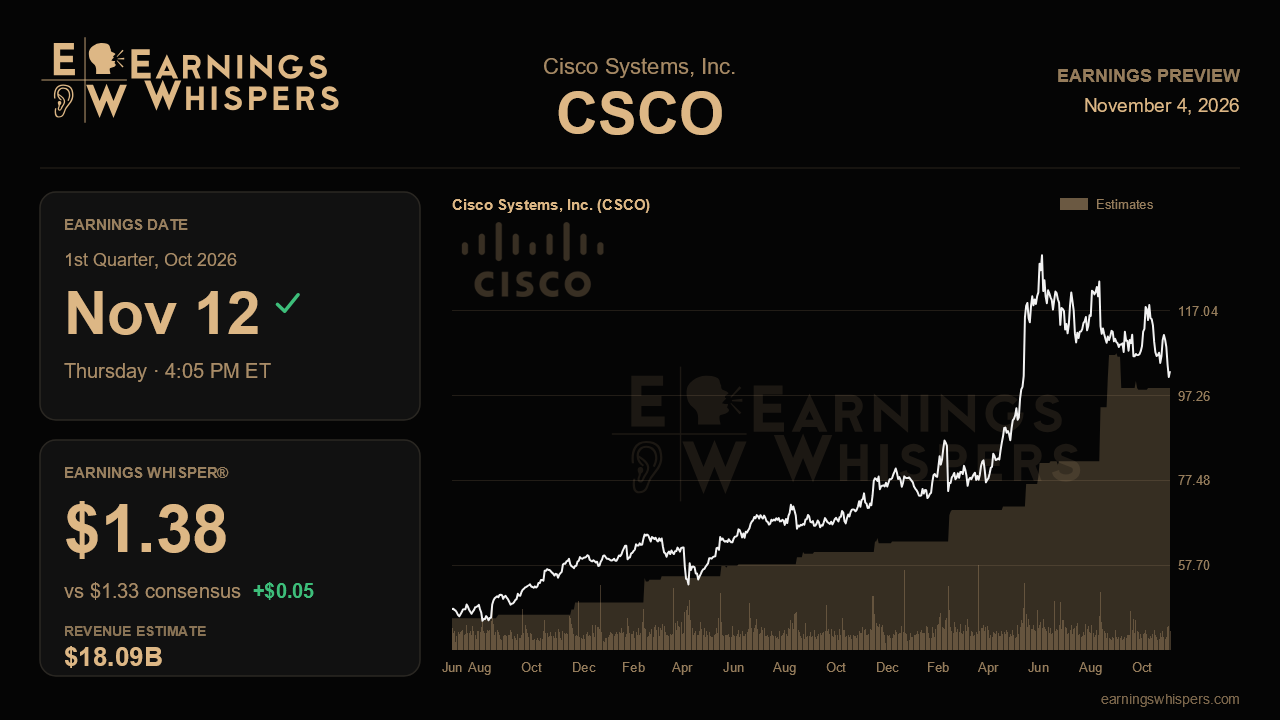
Cisco enters its fiscal first-quarter report with a contradiction that the numbers will have to resolve. Three months ago, management delivered its most confident call in years. It described a multi-year networking super cycle, set a first-ever forward AI revenue target, and guided well above Wall Street. The stock has fallen 9.6% since then, trailing the S&P 500 by about 7 percentage points. That shows either deep skepticism about how durable the boom is, or an opportunity if the company proves its framing was not an overreach.
The bar is set squarely at management's own guidance. Analysts expect non-GAAP earnings of $1.33 a share on revenue of $18.09 billion, right at the midpoints of Cisco's ranges of $1.32 to $1.34 and $18.0 billion to $18.2 billion. That revenue figure would mean growth of roughly 21.6% from a year ago, which is exceptional for a company of Cisco's size. It would also extend a pattern of sequential acceleration through fiscal 2026, when quarterly growth climbed from 8% to 18%. The Earnings Whisper of $1.38 sits meaningfully above consensus. That suggests the more aggressive crowd expects Cisco to clear the top of its range, as it repeatedly did last year when it raised its annual revenue outlook twice and still finished above it.
The most important evidence will come from the AI hyperscale business. Cisco booked about $9.3 billion of AI orders in fiscal 2026 but recognized only around $4 billion as revenue. That gap is the basis for its $7.5 billion revenue target this year. A quarter that shows those orders converting at a pace consistent with nearly doubling AI revenue would validate the target. Investors should also look for follow-through on the three hyperscaler design wins added last quarter, including the third win for the P200 Scale Across platform. Continued strength from the NeoCloud, sovereign and enterprise AI customers, which contributed more than $1 billion of orders last year, would ease concerns about reliance on a handful of lumpy buyers. If product orders slow sharply from the 35% growth of the last two quarters, the peak-cycle argument raised by analysts will gain traction.
The core business matters nearly as much. Enterprise orders reaccelerated to 21% growth by the fourth quarter. Security revenue swung to 14% growth after a year of declines, helped by firewall orders up 30% and Splunk momentum. Evidence that campus refresh and security are sustaining that pace would support management's claim that this cycle extends well beyond hyperscalers. A security result that slips back toward flat would suggest the fourth quarter was a one-off.
Gross margin is the genuine swing factor. Non-GAAP gross margin slid from 68.1% to roughly 66% over fiscal 2026, pressured by a heavier hardware mix and rising memory costs, and the full-year guide of 65% to 66% implies more erosion. Cisco has offset this with operating leverage and price increases, but those price benefits begin lapping this year. A margin print at or above the guided range, alongside operating margin near 35%, would show the earnings model can absorb the mix shift. A drop below 65% would sharpen worries that growth is becoming less profitable.
Sentiment has cooled noticeably. The bullish reading fell to 21.7% from 50.1% heading into the last report. The stock sits near the bottom of its post-earnings range of $101.41 to $118.65 and barely above its 200-day moving average. That entire range lies below the prior quarter's, so the market is clearly not pricing in perfection. Ultimately, the report hinges on whether Cisco can show AI orders turning into revenue on schedule while holding gross margin steady. Delivering both, plus reaffirming its $5.05 to $5.11 full-year earnings outlook, would keep the super-cycle narrative intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-25 | |
| Oct-24 | |
| Oct-20 |
