E.l.f. Beauty Crushes Q2 And Raises Again, But Guidance Implies A Sharp Second-Half Slowdown
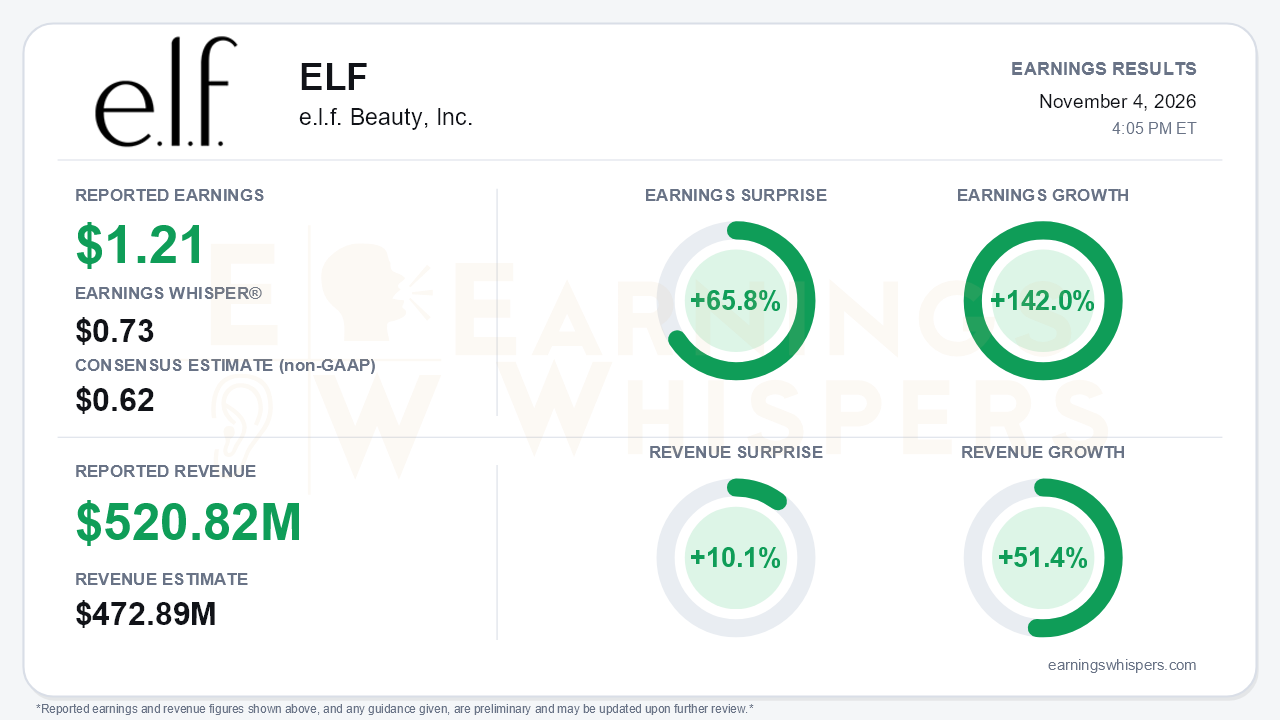
e.l.f. Beauty delivered the kind of quarter that forces a rethink of the post-slowdown narrative. Adjusted EPS of $1.21 beat the $0.62 consensus by 65.8% and cleared the $0.73 Earnings Whisper number by a wide margin. Earnings grew 142.0% year over year. Revenue of $520.82 million rose 51.4% and topped consensus by 10.1%. The company also raised its fiscal 2027 outlook for the second straight quarter. Net sales growth guidance moved to 22-24% from 18-20%, and adjusted EPS guidance rose to $3.82-3.86 from $3.50-3.55. The central tension is that the same guidance implies second-half growth of only 7-10%. Investors are being asked to embrace a spectacular quarter while accepting that a meaningful part of it reflected timing.
The quality of the beat deserves some scrutiny, though less than skeptics might hope. On a GAAP basis, diluted EPS was $0.50, up from $0.05 a year ago. The gap to the adjusted figure reflects:
- $24.6 million of stock-based compensation;
- $11.1 million of acquired-intangible amortization;
- a $17.7 million contingent-consideration charge.
That last item is effectively a cost of success. It stems from rhode outperforming its earnout thresholds, and the first earn-out payment has now been made.
Gross margin rose about 160 basis points to 71%. Only about 30 basis points came from IEEPA tariff refunds, a far cleaner contribution than the roughly 520 basis points of refund benefit embedded in the first-half margin. Adjusted EBITDA jumped 86% to $123.4 million, or 24% of sales. First-half operating cash flow more than doubled to $126.3 million, which funded $50 million of buybacks. One caution: receivables climbed $71 million during the half, which is consistent with heavy retailer pipeline loading.
Beneath the headline, the more important change is that the core e.l.f. brand is working again. Organic growth was roughly 35%, compared with a high-single-digit organic decline in Q1 and just 1% organic growth in Q4 of fiscal 2026. Units added 31 points to growth after subtracting 3 points in Q1 and 5 points in Q4. e.l.f. Cosmetics gained 30 basis points of share, even though the category is growing only low single digits. International sales surged 165%, accelerating from 61% in Q1. The UK, Germany and Canada all recovered from earlier softness.
The catalyst slate is broad:
- rhode's 19-country Sephora Europe launch, described as the largest in Sephora history, with the brand still in only about 40% of doors;
- e.l.f. Cosmetics ranking first in dollars and units in its early weeks at Sephora Brazil;
- Naturium's entry into Sephora Canada and Mexico;
- e.l.f. Hair reaching the top 20 at Target within three months;
- the e.l.f. Pop fragrance and body launch.
The risks sit squarely in the back half. Q2 benefited from an unquantified rhode pipeline fill tied to the Europe rollout. Q4 faces tough comparisons against last year's Ulta expansion, DM Germany, Mecca and Naturium's Walmart launch, so management expects Q4 growth below the 7-10% second-half range. Second-half gross margin is guided down year over year as rhode shifts into lower-margin retail. Second-half adjusted EBITDA margin is now framed in the low teens, down from the mid-teens implied after Q1. That cut reflects reinvestment of roughly $52 million in tariff refunds and marketing spending pushed out of Q2. Excluding refunds, gross margin is still guided flat for the year. Bears therefore have legitimate ammunition: the full-year EPS raise of about 32 cents at the midpoint is smaller than Q2's upside versus consensus, which suggests some of the quarter's strength was pulled forward or will be reinvested.
The market had already been leaning into a recovery. Shares closed at $111.50 the day before the report, 24.8% above the open following the August release. That left the stock 36.7% above its 200-day moving average and 5.7% below its October 16 inter-earnings high of $118.29. Earnings Whispers investor sentiment improved substantially, from -0.48 to -0.15, but remains negative. That combination describes a stock that has rallied while many investors stayed doubtful. Price, momentum and AVWAP trend readings are positive, while sequential growth is neutral, which fits a business whose near-term cadence is about to slow.
The bottom line is that e.l.f. answered the biggest question hanging over the stock: the core brand's unit momentum has genuinely returned, and the rhode acquisition is outperforming. Even so, the second half will look far less impressive. Growth is set to downshift to single digits, and margins will absorb reinvestment and channel mix. With the shares already well extended above long-term trend and sentiment still cautious, the debate shifts from whether e.l.f. can grow to how much of Q2's surge proves durable once the pipeline fill washes out.
Read our earnings preview for e.l.f. Beauty, Inc.: https://www.earningswhispers.com/article/ELF/21831
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Oct-30 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 |
