Qualcomm Misses The Whisper As Data Center And Auto Momentum Run Into Shrinking QCT Margins
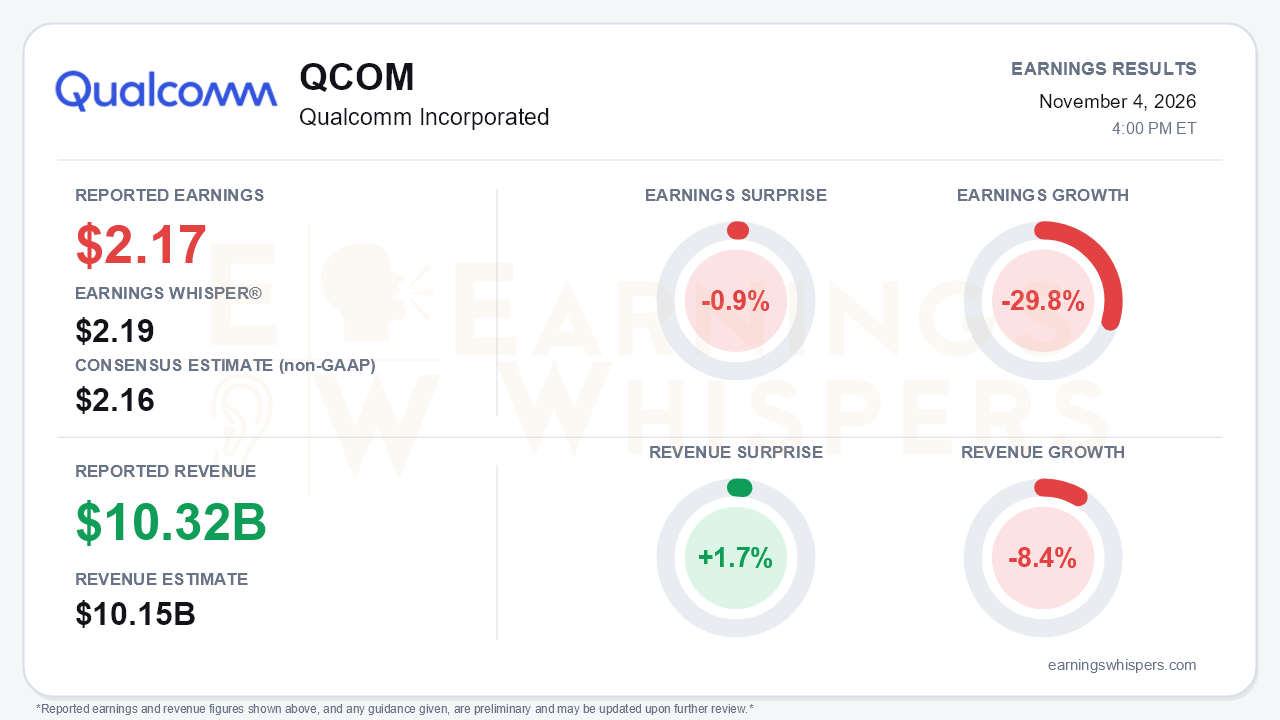
Qualcomm's fiscal fourth quarter delivered a split verdict. The company earned $2.17 per share, a penny above the $2.16 non-GAAP consensus but short of the $2.19 Earnings Whisper number, a 0.9% miss against the bar that mattered. Revenue of $10.322 billion beat the $10.15 billion consensus by 1.7%. The year-over-year comparisons were weak: earnings fell 29.8% and revenue fell 8.4%. Guidance for earnings came in below estimates. That is the central tension. Qualcomm has largely cleared the strategic overhangs that weighed on the stock, but it is paying for its data center build with margin compression that shows up in near-term earnings power.
The brief press release contained no figures, so the call carried the substance. On the call, management cited total revenue of about $10.4 billion, which differs modestly from the $10.322 billion normalized figure above. Either way, revenue improved sequentially from $9.9 billion in the June quarter, and QCT rose 6% to $9.0 billion. The quality of that growth deserves scrutiny, however:
- **Handsets stalled.** Handset revenue was flat sequentially at $5.1 billion and is guided down mid-single digits on the continued Apple ramp-down.
- **Auto carried the quarter.** Automotive posted its first $2 billion quarter, up 89% year over year. That growth has accelerated every quarter this year, from 15% to 38% to 61% to 89%. Management now sees an exit run rate near $8 billion, about $1 billion above the $7 billion target raised just one quarter ago.
- **Non-handset QCT is gaining weight.** Combined auto and IoT growth reached 36%, up from 28% and 20% in the prior two quarters.
Margins moved the other way. QCT EBT margin slid to 24%, down from 26% in the June quarter and 31% in the December quarter. The fiscal first-quarter guide calls for 20-22%, which includes roughly three points of drag from moving data center into the QCT segment and from pre-revenue investment. Gross margin is expected to return only to the low end of the 48-50% range in the second half of fiscal 2027, and custom silicon will then dilute it further. Operating expenses are also rising, to $2.8 billion from $2.7 billion. Bears have legitimate ammunition here. The new growth engines come with structurally lower margins than the handset franchise they are meant to offset.
The catalyst list is unusually dense:
- **Data center revenue begins.** Management guided to more than $650 million in the December quarter, reiterated $5 billion for fiscal 2027, and set a $7 billion exit run rate. It said supply, not demand, limits upside beyond $5 billion.
- **AWS agreement.** A long-term deal for custom AI inference silicon and optical connectivity could be worth up to $60 billion over ten years, and custom accelerators have been shipping since October.
- **Pipeline wins.** Qualcomm added a second optical customer, two new high-bandwidth accelerator prospects, and a large potential CPU customer beyond Meta.
- **SpaceX/Starlink.** A multi-year agreement to power a U.S. terrestrial 5G network expands the infrastructure story, though meaningful revenue is mostly a fiscal 2028 event.
- **Licensing de-risked.** QTL renewals with Apple, Huawei and Transsion held the royalty run rate, with no major OEM renewals due until fiscal 2030.
- **ARM verdict.** A favorable jury ruling against ARM helps, though the remedies phase is still pending.
Management's tone was notably more confident; it described the uncertainties as now behind the company.
The risks are mostly about the core business and execution. The global handset market is expected to decline low-to-mid teens in calendar 2026, with fourth-quarter units down more than 20%, and fiscal 2027 is assumed flat to down. Management declined to reaffirm its earlier view that the March quarter would be up sequentially, a subtle but meaningful softening. IoT growth slowed to 4% from 9% as memory constraints hit consumer products.
Investor sentiment improved meaningfully into the report. It rose from -0.20 after the July release to roughly neutral at -0.01, so investors moved from skepticism to something closer to wait-and-see. Price action tells a more complicated story. Shares were up 12.2% since the open after the prior report, at $164.43. But they ran to $205.85 in late September and then gave back much of that spike, entering earnings 20.1% below that high and 3% below the 200-day moving average of $169.50. The Earnings Whispers price and AVWAP trend readings remain negative. In short, the market priced in the data center narrative quickly and then started demanding proof.
The bottom line is that Qualcomm has traded one set of questions for another. Licensing, Huawei, the China Android bottom and the ARM dispute have largely resolved in its favor, and auto plus data center now offer a credible path to diversification. But the quarter missed the whisper, earnings are well below last year, guidance trails estimates, and QCT margins are heading toward the low 20s just as handsets weaken again. Whether investors look through that margin trough to the fiscal 2027 data center ramp will likely determine whether the stock can reclaim the ground it lost after its September peak.
Read our earnings preview for Qualcomm Incorporated: https://www.earningswhispers.com/article/QCOM/21916
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
Qualcomm Revenue Falls as Handset Slowdown Offsets Automotive Gains
QCOM +5.33% QCOM -7.52% AH
The Wall Street Journal
|
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
