Snap Turns A GAAP Profit And Lifts Its Q4 Outlook, But 4% Ad Growth Shows A Weaker Core
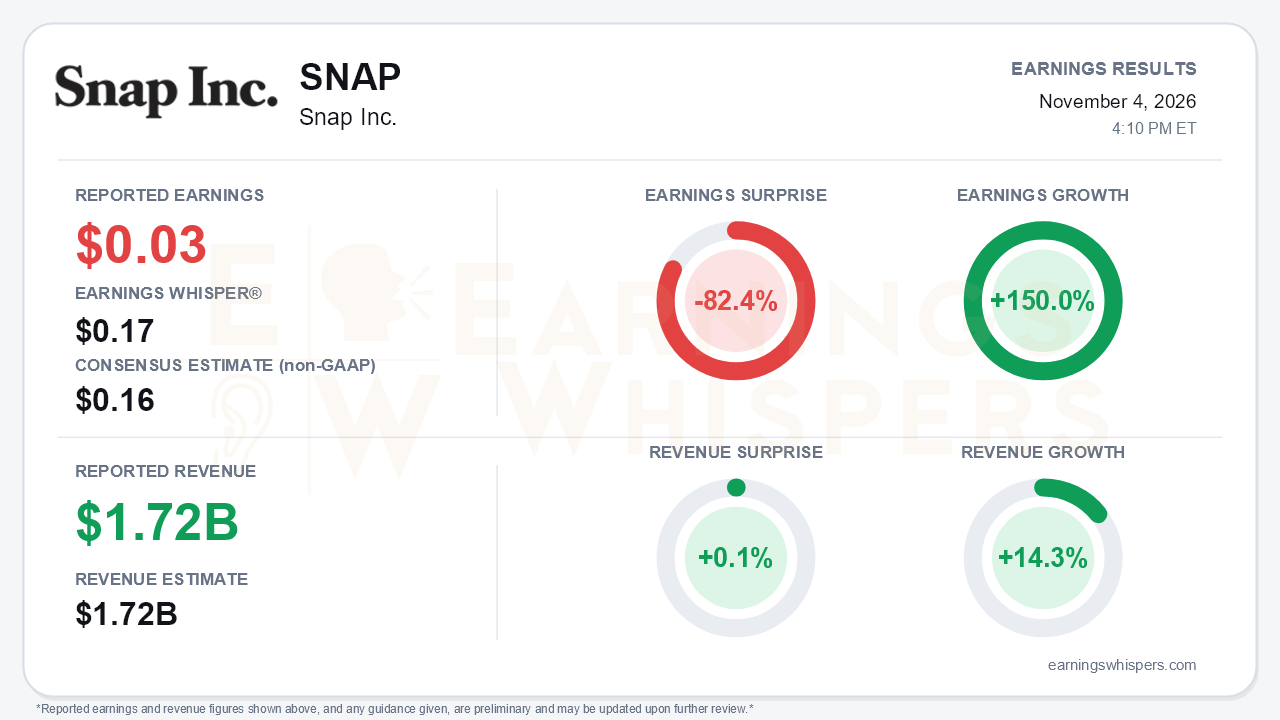
Snap Inc. reported third-quarter earnings of $0.03 per share, an 82.4% miss against the $0.16 consensus and well short of the $0.17 Earnings Whisper number. Revenue of $1.722 billion edged past the $1.72 billion consensus by 0.1% and grew 14.3% year over year. The miss needs context. The reported figure is GAAP diluted EPS, while the consensus was set on a non-GAAP basis, so the gap reflects accounting basis at least as much as operating shortfall. On Snap's own scorecard, the quarter was a profitability breakout. The company swung from a $0.06 loss a year ago to a $0.03 profit, which works out to 150.0% earnings growth. Adjusted EBITDA of $383 million cleared the $300-350 million range management set in August. The central tension is that this margin breakout arrived alongside a sharp slowdown in advertising, the business that still defines Snap.
The profit improvement came mostly from cost discipline rather than top-line strength:
- **Gross margin:** reached 62%, up from 58% in Q2 and 57% in Q1, clearing the 60%-plus full-year goal.
- **Costs:** cost of revenue fell year over year even as revenue rose 14%, and total costs grew only about 1%.
- **Headcount:** full-time employees fell to 4,540, down 13%, after the restructuring that cost $128.5 million earlier in the year.
- **Flow-through:** about 93% of incremental revenue reached adjusted EBITDA.
The quality of that profit deserves some scrutiny. Stock-based compensation was still $255 million, nearly 15% of revenue, which is why $383 million of adjusted EBITDA became only $77 million of GAAP operating income. Management also flagged the 93% flow-through as specific to this quarter's mix, seasonality and expense timing. Free cash flow of $164 million rose 76%, and trailing free cash flow reached $777 million. Operating cash flow, however, absorbed a $104 million drop in accounts payable.
The call made the revenue picture more complicated than the headline beat suggests:
- **Advertising:** ad revenue growth slowed to 4% from 9% in Q2. Spiegel called the pace "below our ambitions."
- **Total revenue:** growth slowed to 14% from 19%, and revenue landed mid-range of guidance after topping the high end in Q1.
- **Brand spending:** upper-funnel brand advertising declined year over year. Management cited weaker CPG budgets tied to U.S. macro pressure and the Middle East, plus lapping World Cup spend, and expects brand to recover only over 2027.
- **Other revenue:** grew 84%, with paid subscribers above 30 million versus 24 million at the end of 2025. Subscriptions are now doing a meaningful share of the growth work.
- **Direct response:** now roughly 77% of revenue, and these products are gaining traction. Sponsored Snaps revenue rose 56% sequentially after auction-based pricing launched in Europe. Promoted Places revenue more than doubled across 14 countries. App-purchase revenue grew more than 54%.
The forward setup tilts constructive on profitability. Q4 guidance calls for revenue of $1.95-1.985 billion, about 13-15% growth and above estimates, and adjusted EBITDA of $490-525 million versus $358 million a year ago. Management also trimmed its infrastructure cost range to $1.65-1.66 billion while increasing AI/ML spending. Near-term catalysts include the Commerce Powerpack ahead of the holidays, unified attribution with AppsFlyer and Adjust, and Specs shipping later this fall.
Bears have legitimate ammunition on three fronts:
- **User metrics:** North American DAUs fell 6% to 92 million, and Snap will replace DAU with MAU as its primary audience metric starting in 2027, stating it will not optimize for daily use. Investors may read that as obscuring engagement trends in the most valuable region. North American ARPU rose 20%, so monetization of that shrinking base is still improving.
- **Dilution:** shares underlying stock awards rose 42%, pushing the fully diluted count up 3.8%. The new dilution management program targets a stable count only in 2027.
- **Regulation:** youth-related regulatory and litigation risk remains unresolved.
Investor sentiment heading into the report was modestly positive and improving, rising from 0.157 to 0.223. That is a meaningful but not dramatic shift. The price action was more muted. At $5.59, shares were up 4.9% from the open after the August report and only about 3% above their 200-day moving average of $5.43. More notably, the stock sat 18.4% below its October 13 high of $6.85, so it had already given back much of the quarter's rally before reporting. Most Earnings Whispers trend readings are positive, though AVWAP remains negative, which fits a stock that has improved but has not held its gains.
The bottom line is that Snap delivered on the profitability narrative, with record gross margin, positive GAAP income, rising free cash flow and a strong Q4 EBITDA guide. The engine underneath is less convincing. Ad growth of 4%, a declining brand business and a shrinking North American user base mean the margin story is running ahead of the revenue story. Until advertising reaccelerates, subscriptions and cost cuts are carrying more of the load than a growth-oriented investor would like.
Read our earnings preview for Snap Inc.: https://www.earningswhispers.com/article/SNAP/21941
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 |
Meta Settles Another Lawsuit Over Being Addictive As Legal Reckoning Continues. Its Stock Edged Down.
SNAP
International Business Times
|
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Oct-30 |
