AppLovin Rebuilds Credibility With A Re-Accelerating Q3 Beat, But A Slower Q4 Guide Meets A Stock Near Its Lows
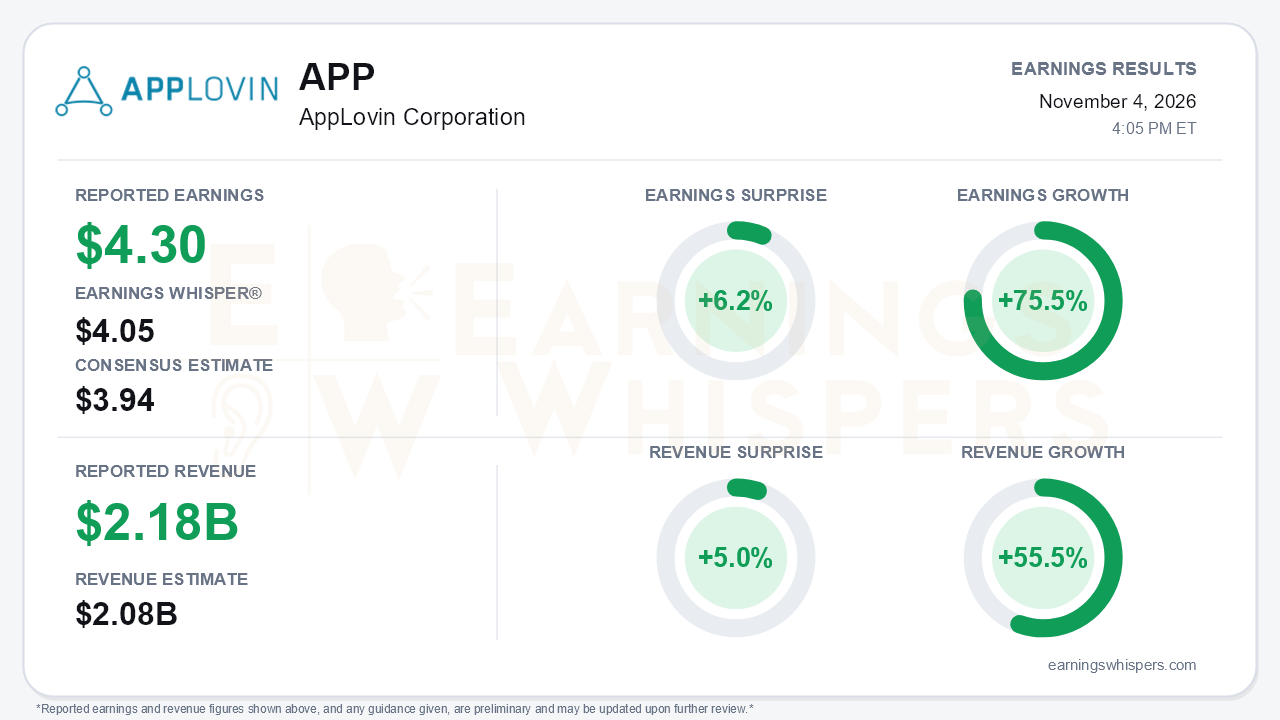
AppLovin answered its second-quarter stumble with a beat that cleared every bar. The company earned $4.30 per share in the third quarter, topping the $3.94 consensus by 6.2% and also clearing the $4.05 Earnings Whisper number. Revenue of $2.185 billion beat the $2.08 billion consensus by 5.0%. Earnings grew 75.5% year over year and revenue rose 55.5%. More important than the size of the beat is its direction. Year-over-year revenue growth re-accelerated from 53% in Q2, although it remains below Q1's 59%. Sequential growth jumped to 14% from just 4% last quarter, and revenue landed roughly $100 million above the top of management's own $2.055-2.085 billion guide. That is the central development: the engine that faltered in Q2 is running hot again. The open question is whether a decelerating fourth-quarter guide and a battered share price leave investors trusting it.
The quality of the quarter is high, though not every dollar of EPS came from operations. Operating income rose 58% to $1.71 billion. Net income grew faster, up 72% to $1.44 billion, helped by an $86 million swing to other income from a $6.6 million expense a year ago. A shrinking share base, down to 331 million shares after $1.4 billion of third-quarter repurchases, added further support to per-share results. Costs are also climbing:
- Research and development more than doubled to $102 million.
- Stock-based compensation rose to $84 million from $34 million.
Adjusted EBITDA margin still expanded to 84% from 82%, and adjusted EBITDA of $1.84 billion beat the $1.71-1.74 billion guide after Q2 fell short of its range. Cash generation rebounded sharply. Free cash flow reached $1.42 billion, a 77% conversion of EBITDA versus 53% in Q2. Incremental flow-through improved to 87% from 70%.
The call explained what changed. Management partially rolled out a next-generation model architecture during the quarter and framed it as comparable in technical complexity to Axon 2.0, with significant optimization headroom remaining. Gaming, the legacy core, re-accelerated to nearly 50% growth on that rollout. Consumer and e-commerce spend grew double digits sequentially and triple digits year over year. Pixel adoption is accelerating through referral partners. Connected TV moved from something the company was not yet able to execute in Q2 to live pilot campaigns. Data center costs fell as a share of revenue even as training compute rose, which is a quiet but meaningful signal for margin durability. The tone was notably more confident, and management reiterated its long-term target of roughly 30% compounding.
Bears still have legitimate ammunition:
- **Slower Q4 guide.** The fourth-quarter revenue guide of $2.365-2.395 billion implies 8-10% sequential growth versus 14% in Q3, and year-over-year growth easing to 43-44%. Management says its guidance philosophy is unchanged. Still, this is a deceleration from a quarter that only just restored confidence.
- **Bigger seasonal swings.** Management warned that a rising consumer mix will create bigger fourth quarters followed by sharper first-quarter resets, a new seasonal pattern investors will have to model.
- **Lumpy model gains.** Improvements remain unpredictable, and management did not commit to a timeline for the full rollout.
- **Data needs.** Management said the models are "starved for data." That helps explain why MoPub-style data acquisitions were floated, but it also implies dependence on outside inputs.
- **Softer cash conversion target.** Full-year free cash flow conversion was trimmed to 70-75% of EBITDA from roughly 75%.
- **Advertiser behavior.** Channel checks citing auction-price inflation and some advertisers shifting budgets elsewhere were raised on the call. These were not resolved.
- **Stalled lead gen.** Lead generation, a Q1 priority, has not progressed beyond "still testing."
The market setup is more complicated than the surprise implies. Shares opened at $338.45 after the Q2 report and entered this release at $245.51, a 27.5% decline. The stock sat about 40% below its 200-day moving average of $411.61. It hit a 52-week low of $225.19 on October 30, just days before the report, and was only 9% above that level. Investor sentiment was essentially neutral heading into the quarter and slipped marginally negative. The shift was small, but it reflects lingering skepticism rather than renewed enthusiasm. The Earnings Whispers trend readings are mixed: sequential growth is positive while price and AVWAP trends remain negative. That split tracks the gap between improving fundamentals and a stock still being sold. Management is leaning into that gap with an expanded $3.6 billion repurchase authorization, signaling it views the discount as an opportunity.
The bottom line is that AppLovin delivered the kind of quarter turnaround skeptics were not positioned for. Revenue re-accelerated, margins expanded, cash conversion recovered, and a new model generation is still only partly deployed. The quality of the EPS beat is slightly flattered by other income and buybacks, and the Q4 guide resets sequential momentum lower. Even so, the operating story is clearly stronger than it was three months ago. With shares near their lows and far below long-term trend, the report rebuilds credibility. Converting that into price will depend on whether Q4 and a potentially weaker seasonal Q1 confirm that Q2 was the anomaly.
Read our earnings preview for AppLovin Corporation: https://www.earningswhispers.com/article/APP/21783
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 5 hours | |
| 5 hours |
AppLovin Stock Surges As Earnings Beat Provides Much-Needed Boost
APP +10.69% APP +22.83% AH
Investor's Business Daily
|
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| 17 hours | |
| 19 hours | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 |
