Wendy's Tops Lowered Bar As U.S. Comps Improve, But Margins, Leverage And Franchisee Stress Keep The Turnaround Unproven
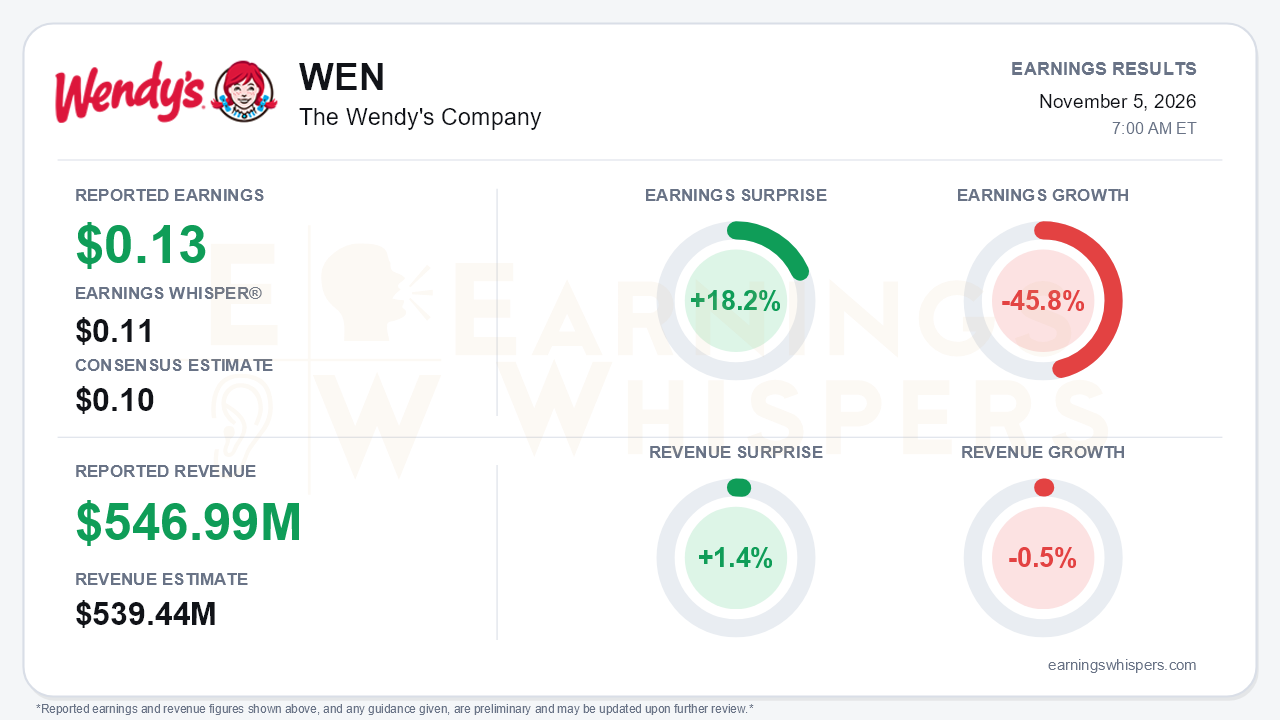
Wendy's (NASDAQ: WEN) cleared a deliberately low bar in the third quarter, posting adjusted earnings of $0.13 per share against a $0.10 consensus and a $0.11 Earnings Whisper. That is an 18.2% surprise. Revenue of $546.99 million topped the $539.44 million consensus by 1.4%. The beat was real, but earnings still fell 45.8% from a year ago, revenue slipped 0.5%, and adjusted EPS dropped sequentially from $0.18 in the second quarter. That is the central tension. The top-line trend is improving, but the profit trend is still getting worse, and investors are being asked to pay for a strategy rather than results.
The quality of the beat deserves scrutiny. GAAP diluted EPS was just $0.08, versus $0.23 a year earlier. The gap to the adjusted figure is largely $11.9 million of Dave's Way transformation costs, mostly consulting and professional fees, which management excluded as infrequent. Even after that exclusion, adjusted EBITDA fell 17.8% to $113.4 million. The underlying revenue mix is also weaker than the flat headline suggests. Franchise royalty revenue fell to $119.4 million from $127.8 million. Higher advertising-fund revenue, which is a pass-through, padded the total, and adjusted revenue fell 1.6%. Franchise support costs jumped to $26.9 million from $17.5 million, driven by a $9.1 million increase in doubtful-account provisions tied to royalty deferrals and past-due franchisee balances. That charge was not adjusted out, and it points to stress inside the franchise system. U.S. company-operated restaurant margin slid to 11.7%, from 13.1% a year ago and 13.8% in the second quarter. Lower traffic and labor and commodity inflation outweighed a higher average check.
The call preserved a credible improvement story on demand. U.S. same-restaurant sales declined 5.7%, an improvement from -7.0% in the second quarter, -7.8% in the first quarter and -11.3% in the fourth quarter of fiscal 2025. That result also beat the roughly -7% second-half run rate management had implied last quarter. Traffic remained deeply negative at -11.9% but improved from -12.5% and strengthened through each period of the quarter. Management called quarter-to-date fourth-quarter trends encouraging, crediting the $7.99 Dave's Single Combo and a revised media strategy. Several other indicators also moved in the right direction:
- U.S. net closures slowed to 13 after 289 in the first half.
- Commodity inflation eased to about 4% from about 9%.
- International systemwide sales grew 3.5%, although international comps were -2.2% on Canada weakness.
Management's tone shifted from last quarter's candid acknowledgment of underperformance to confident early-execution framing.
The catalyst list is long. Breakfast becomes optional for U.S. restaurants, a move management estimates could unlock up to $200 million in systemwide restaurant-level EBITDA. Delivery promotions now cover more than 90% of U.S. franchise units, and tests showed delivery sales lifts of roughly 10% to 20%. A full core-menu refresh is planned for 2027. The company also signed a letter of intent to acquire up to 163 restaurants from bankrupt franchisee Meritage. Separately, the independent committee unanimously rejected an unsolicited acquisition proposal from a Trian-led group received October 28, citing confidence in the plan.
Bears have legitimate ammunition, however.
- **Leverage:** Net leverage rose to 5.2x, from 5.0x in the second quarter and 4.8x at year-end, above the prior 3.5x to 5.0x target range.
- **Refinancing:** Roughly $430 million of debt matures in March 2028.
- **Cash flow:** Year-to-date free cash flow of $174.2 million is down $21.4 million, a reversal from the first-half gain.
- **Capital returns:** The dividend remains at the reduced $0.07, and no shares were repurchased.
- **Business model:** The Meritage deal would add operating and capital exposure to a historically asset-light model.
- **Breakfast exit:** Dropping breakfast could weigh on sales near term.
- **Guidance:** The withdrawn fiscal 2026 outlook was not reinstated.
Investor expectations had already started to thaw before the report. Earnings Whispers sentiment improved meaningfully, from -0.41 to -0.13, but it remains negative. Shares closed at $7.65 ahead of the release, up 8.1% from the post-second-quarter open of $7.08 and about 4% above the 200-day moving average of $7.35. The path was volatile. The stock spiked to $9.14 in late August, collapsed to a 52-week low of $5.94 on October 5, then rallied nearly 29% off that low into the report. Still, it sits about 16% below the quarter's high, and Earnings Whispers trend readings remain broadly negative, with sequential growth and momentum still deteriorating.
The bottom line is that Wendy's delivered a beat against depressed expectations and a genuine, if gradual, improvement in U.S. comps and traffic. Those gains have not yet reached the income statement. Margins, EBITDA, cash flow and leverage all moved the wrong way, and franchisee health is now an explicit risk. The rejected takeover bid and Dave's Way give management a narrative, and sentiment is warming. The next test is whether improving traffic translates into stabilizing profits before the balance sheet narrows the company's room to execute.
Read our earnings preview for The Wendy's Company: https://www.earningswhispers.com/article/WEN/22213
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 |
