Airbnb Posts Its Fastest Growth In Three Years, But A Peaking Booking Tailwind And A Softer Q4 Test The Durability Of The Acceleration
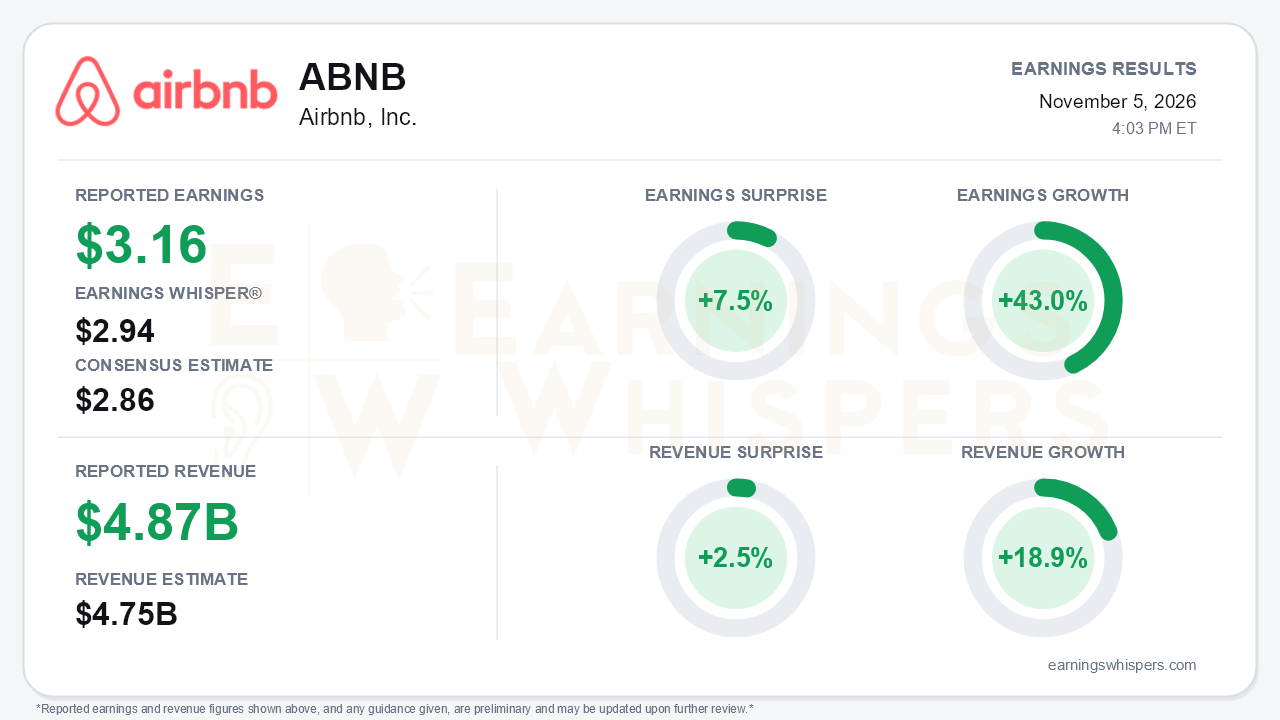
Airbnb delivered the kind of quarter growth investors had been waiting for. Third-quarter earnings of $3.16 per share beat the $2.86 consensus by 7.5% and cleared the $2.94 Earnings Whisper number. Earnings grew 43.0% year over year. Revenue of $4.869 billion topped the $4.75 billion consensus by 2.5% and grew 18.9%, which management called the fastest growth in more than three years. It also came in well above the company's own $4.69-$4.77 billion guide from the Q2 call. The central takeaway is that Airbnb is clearly accelerating. The harder question is how much of that acceleration is durable demand and how much is timing.
The top-line detail is genuinely strong. Gross booking value rose 21% to $27.7 billion, up from 16% in Q2. Nights and seats grew 16%, after running between 9% and 10% for the prior three quarters. All four regions accelerated, and North America nights hit a four-year high. First-time booker growth improved to 13% from 11% in Q2. Profitability scaled with the volume: adjusted EBITDA margin reached 52%, up from 50% a year ago. The quality of the beat still deserves scrutiny, however. About 3 points of nights growth came from Reserve Now Pay Later, and management says that lift peaked in Q3. Some marketing spend was also shifted out of Q3 and into Q4, which flatters the quarter's margin.
The call reinforced that the underlying trend is improving even after stripping out the noise. Excluding RNPL, nights grew roughly 13%, still a clear step up. The full-year outlook has now been raised four consecutive times:
- **Revenue growth:** moved from low double digits to low-to-mid teens, then at least mid-teens, and now high teens.
- **Adjusted EBITDA margin:** moved from roughly stable, to at least 35%, then 35.5%, and now about 36%.
Efficiency gains are compounding. AI support now resolves about 40% of all issues, and support cost per booking fell 17% year over year. App share of nights climbed to 66%. Management adopted a more emphatic "back in growth mode" framing, and the call largely supported it.
The forward pipeline is unusually crowded. The main catalysts include:
- an exclusive American Express Travel partnership, with about a quarter of those bookings coming from guests new to Airbnb and a higher luxury mix;
- completion of the single 15.5% service fee;
- a dynamic pricing tool that management describes as a lever many times bigger than RNPL;
- hotels in more than 60 destinations, with bookings accelerating;
- a proprietary AI trip agent due in the first half of 2027;
- a Booking.com veteran hired as Chief Business Officer;
- a new $12 billion buyback authorization on top of $2.7 billion remaining.
Bears still have legitimate ammunition. Cancellation rates rose to about 19% from about 16%. The implied take rate slipped to 17.6% on RNPL timing and incentives for new businesses. Free cash flow of $1.4 billion grew only modestly, held back by RNPL working capital and New York office capex, and trailing free cash flow margin fell to 35% from 37% in Q2. Q3 repurchases also dropped to $700 million from $1.1 billion in each of the first two quarters, even as the new authorization headline grew larger.
That sets up the main conflict in the outlook. Earnings Whispers characterizes the guidance as in line, even though the full-year range moved higher. The reconciliation is that the full-year raise largely reflects the Q3 outperformance, while the fourth quarter implies a clear slowdown:
- revenue growth of 16-18%, including about 2 points of foreign-exchange benefit;
- gross booking value growth in the mid-teens, down from 21%;
- adjusted EBITDA margin slightly lower year over year as the deferred marketing lands.
Unrest in Europe and the Middle East conflict are not assumed in that guide. The debate over whether general-purpose AI agents could disintermediate Airbnb also lingers, although management says bookings through those channels are immaterial today.
Investor sentiment eased slightly into the report, slipping to 0.343 from 0.366. That is a small move, and expectations remain moderately positive rather than euphoric. The stock's path has been more volatile than that steady reading suggests. Shares set a 52-week high of $193.45 in late August, then fell to $149.00 by late September. They entered the report at $176.37, up 7.1% from the open after the prior report, 19.6% above the 200-day moving average, and still 8.8% below the August peak. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative. That fits a stock that has recovered substantially without reclaiming its highs.
The bottom line is that Airbnb produced a quarter that turnaround skeptics were not positioned for: accelerating bookings, higher margins, a fourth straight full-year raise, and a deep catalyst slate. The market setup is more complicated than the surprise implies. Q3 benefited from a peaking RNPL tailwind and shifted marketing spend, and Q4 guidance points to slower growth, a dip in margin, and soft free cash flow conversion. The coming quarters will show whether pricing, Amex, and hotels can carry growth once those timing benefits fade.
Read our earnings preview for Airbnb, Inc.: https://www.earningswhispers.com/article/ABNB/22221
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 15 min | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 |
Airbnb Stock Jumps After Posting Earnings Beat, Strong Outlook
ABNB ABNB +10.19%
Investor's Business Daily
|
| Nov-05 |
Airbnb Raises Outlook as It Remains Insulated from Global Conflicts
ABNB ABNB +10.19%
The Wall Street Journal
|
| Nov-05 | |
| Nov-05 |
