Cloudflare Hits 39% Growth And Pulls GAAP Profit Target Into Q4, But Gross Margin And Cash Conversion Lag The Revenue Beat
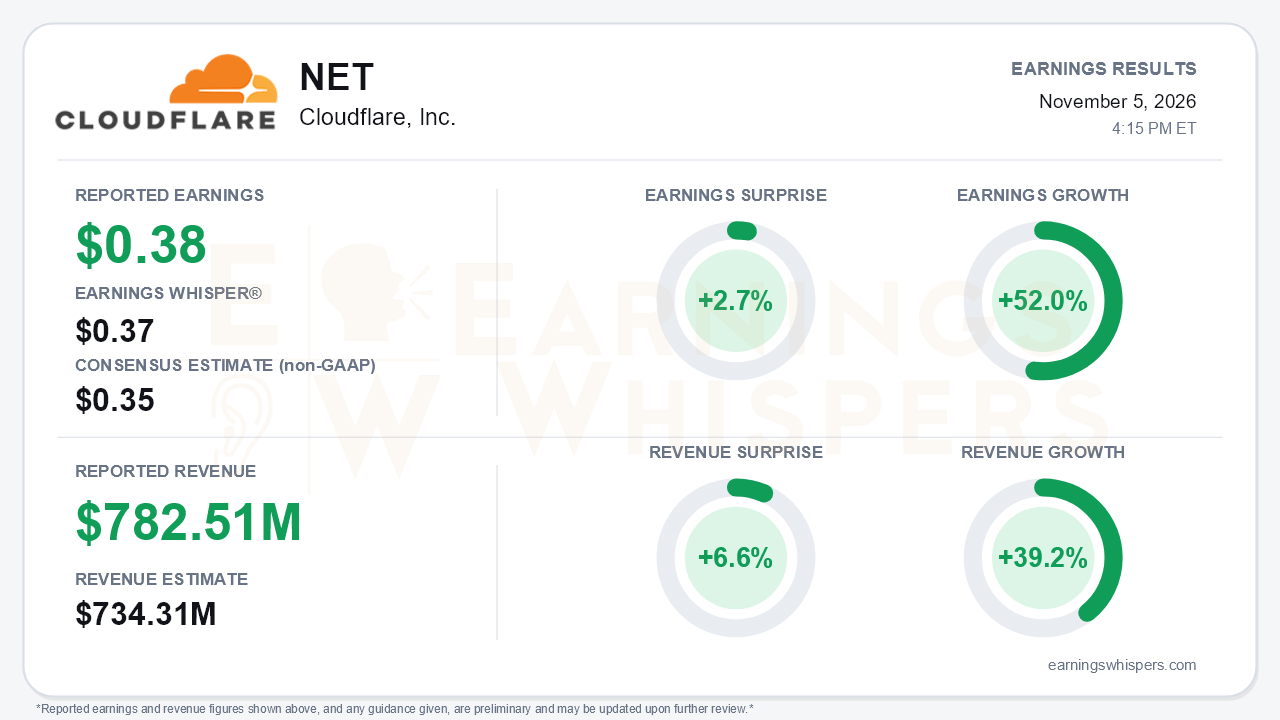
Cloudflare (NYSE: NET) delivered the kind of top-line acceleration that is rare at a $3 billion revenue run rate. Third-quarter revenue rose 39.2% year over year to $782.51 million, topping the $734.31 million consensus by 6.6%. That compares with 36% growth in the second quarter and 34% in each of the two quarters before it. Non-GAAP EPS of $0.38 beat the $0.35 consensus by 2.7% and edged past the $0.37 Earnings Whisper number, with earnings growing 52.0% year over year. Management raised full-year guidance for the fourth consecutive quarter and, according to the call, now expects GAAP profitability in the fourth quarter of 2026, years ahead of its prior 2028 target. The central tension is that the revenue beat was far larger than the earnings beat. The gap points to a business growing faster while generating less gross profit per dollar of revenue.
The quality of the quarter deserves scrutiny beneath that headline. Non-GAAP gross margin fell to 72.4% from 75.3% a year ago and 73.1% in the second quarter, below the company's old 75-77% target. The call attributed the decline to the scaling of its lower-margin Workers developer platform. Operating leverage more than offset that pressure. Non-GAAP operating margin reached a record 17.5%, up from 15.3% a year earlier and 13.8% last quarter. Operating expenses fell to 55% of revenue following the roughly 20% workforce restructuring earlier in the year. GAAP results moved the other way. The GAAP operating loss widened to $67.9 million from $37.5 million, and the GAAP net loss grew to $34.1 million from $1.3 million. The drivers were stock-based compensation and related payroll taxes, which rose to $174.1 million from $119.7 million, plus $11.0 million in restructuring charges and a $10.7 million legal reserve. That makes the Q4 GAAP-profit target a meaningful commitment rather than a formality.
Cash conversion was also softer than the income statement implies. Operating cash flow rose to $215.4 million, but free cash flow of $82.1 million was just 10% of revenue, down from 13% a year ago. Network capex jumped to 15% of revenue from 7% in the second quarter. Total RPO growth slowed to 34% from 38% last quarter and 48% at the end of 2025. Current RPO, however, accelerated to 37%, which suggests near-term bookings remain healthy even as longer-dated commitments grow more slowly. Large-customer count growth also eased to 25% from 27%. Management also flagged that variable, pool-of-funds revenue makes quarter-to-quarter forecasting more volatile.
The demand indicators otherwise argue that the acceleration is broad rather than driven by one large deal:
- Dollar-based net retention climbed to 122% from 120% in Q2 and 118% in Q1.
- Paying customer additions hit a record 158,000, roughly double the prior record of 80,000 set in Q2.
- Active developers passed 10 million, up from 7.4 million last quarter.
- Large wins included a $15.5 million Magic Transit deal with a Fortune 100 cloud provider and an $11 million AI-company commitment.
Management also pointed to its first revenue from "Act 4," its agent-monetization model, along with a paid crawl-efficiency partnership with OpenAI. It cited a wave of AI-discovered vulnerabilities as a driver of security demand. The tone escalated noticeably, with management describing the period as its "best quarter ever."
The forward setup carries real execution variables. Fourth-quarter guidance calls for revenue of $845-846 million, roughly 38% growth, and non-GAAP EPS of $0.43. Full-year revenue guidance has risen from an initial $2.785-2.795 billion to $2.963-2.964 billion, and full-year EPS guidance from $1.11-1.12 to $1.35. Against that, sales chief Mark Anderson retires at year-end, with Christian Smith succeeding him. The company also issued $2.5 billion in new convertible notes this year, partly to retire $1.29 billion of maturing notes, and now holds $5.13 billion in cash and securities.
The market had not been treating the stock like a company in the middle of an acceleration. Shares closed at $266.58 the day before the report, down 16.2% from the opening price after the August report. That close sits 28% below the 52-week high of $370.35 set on October 6 and just 3.4% above the inter-earnings low, which was set that same day. The stock remains about 6.9% above its 200-day moving average. Investor sentiment was essentially unchanged at a mildly positive 0.143. Most Earnings Whispers trend signals are positive, though AVWAP remains negative, consistent with the steep pullback from the October peak.
The bottom line is that Cloudflare produced a genuinely accelerating quarter, with faster revenue growth, record non-GAAP operating margin, rising net retention, and a fourth straight guidance raise. The pulled-forward GAAP-profit target adds a new proof point for the fourth quarter. Bears still have legitimate ammunition in eroding gross margin, a heavier capex burden, decelerating total RPO, and a sales leadership handoff. A stock that entered the report near its quarterly low suggests investors were already weighing those costs against the growth story.
Read our earnings preview for Cloudflare, Inc.: https://www.earningswhispers.com/article/NET/22344
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 |
Cloudflare Stock Surges on Lifted Full-Year Outlook, Third-Quarter Revenue Growth
NET -8.28% NET +11.00%
The Wall Street Journal
|
| Nov-05 | |
| Nov-05 |
Cloudflare Earnings Beat. Software Maker Rebounds From AI Stock Rout.
NET -8.28% NET +11.00%
Investor's Business Daily
|
| Nov-05 |
