IREN's AI Cloud Revenue Nearly Triples, But A Wider-Than-Expected Loss, A Slipped ARR Target And A Financing-Driven Capex Cut Set The Tone
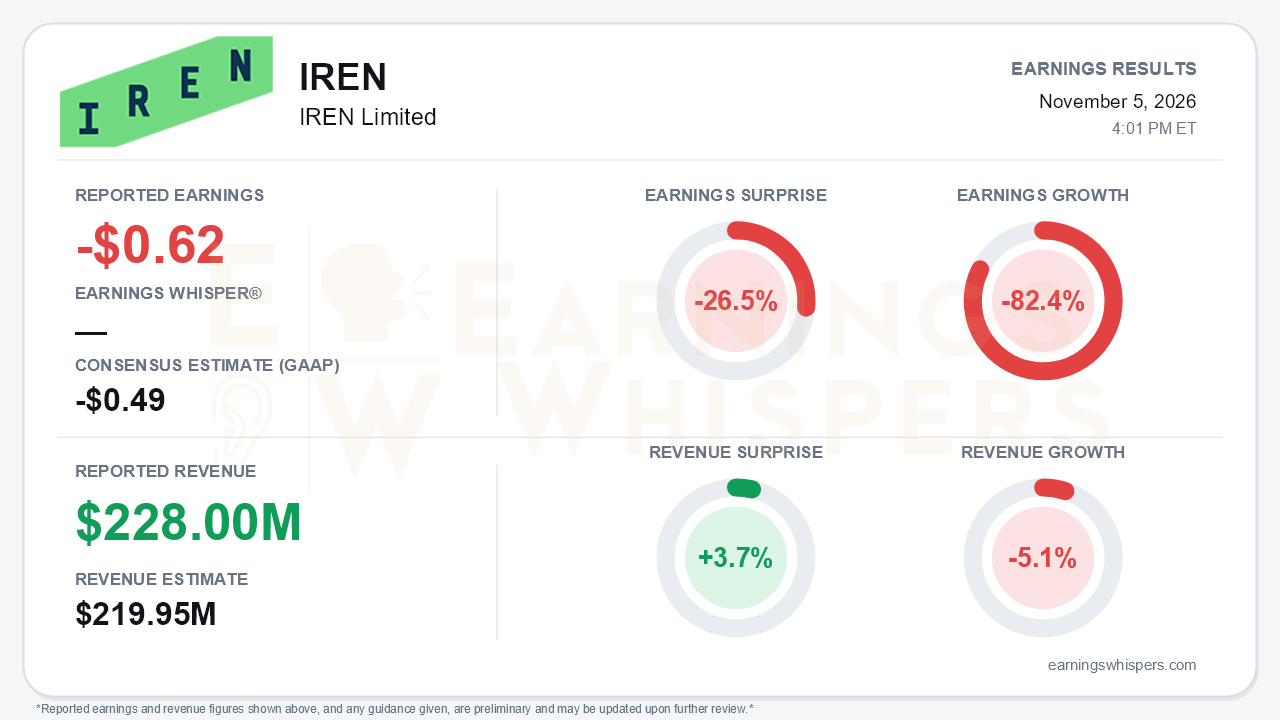
IREN Limited delivered the operational inflection its AI Cloud strategy promised, and still missed on the bottom line. The company reported a fiscal first-quarter loss of $0.62 per share, against a GAAP consensus of -$0.49, a 26.5% miss. Earnings fell 82.4% from a year ago. Revenue of $228.0 million beat the $219.95 million consensus by 3.7% and rose 66% sequentially. Yet it was down 5.1% year over year, a reminder that the company is still swapping out a shrinking Bitcoin mining business for a fast-growing but capital-hungry AI Cloud franchise. That is the central tension. The revenue engine is accelerating sharply, while the timeline, funding and cost structure behind it all moved in the wrong direction this quarter.
The top-line story beneath the headline is strong. AI Cloud revenue climbed to $200 million from $71 million in the June quarter, and from $33.6 million and $17.3 million in the two quarters before that. The mix now includes $65 million of lease revenue tied to Horizon 1's handover to Microsoft. AI Cloud segment gross margin held at 86%. Adjusted EBITDA more than tripled to $66 million, lifting the margin to 29% from 14%. Bitcoin mining revenue fell to $28 million from $67 million, which management described as planned.
The quality of the quarter deserves scrutiny below the EBITDA line. GAAP net loss narrowed to $263 million from $684 million, but that improvement mostly reflects the absence of last quarter's $450 million impairment. Cost pressure is building:
- SG&A rose to $217 million from $128 million.
- Stock-based compensation jumped to $106 million from $43 million.
- Depreciation climbed to $148 million.
- Finance expense tripled to $73 million.
- Cash operating expense is guided up another $50-60 million in the December quarter.
On the call, the demand picture was unambiguously firm. Operating ARR doubled to roughly $1 billion exiting September. Revenue backlog grew 22% sequentially to $20.3 billion, about two-thirds with investment-grade counterparties. Pricing kept rising: in-quarter three-year deals rose 11% and five-year deals 12%. After quarter-end, IREN signed:
- a five-year contract at about $22 million per megawatt, with the customer prepaying roughly 90% of the GPU capex, compared with the 45-55% prepayment levels cited last quarter;
- a short-term deal above $40 million per megawatt;
- a recontract of older H100s at double their original pricing.
GPU payback is now pegged at about 18 months, versus roughly two years. The frontier AI lab contract was expanded again, and Horizon 1 arrived with NVIDIA Exemplar status.
The forward-looking items are where bears have legitimate ammunition. The more than $4 billion ARR target has slipped from year-end 2026 to January 2027, and possibly the end of February. Management cited a Microsoft-requested network design change and supplier timing. That is a modest delay, but it is a delay on the company's flagship milestone. More consequential, FY27 capex was cut to about $20 billion from the $25-30 billion previously guided. Management explicitly tied the cut to more selective capital markets, and Childress air-cooled deployments are now spread across calendar 2027. Of the remaining $15 billion in planned capex, $6 billion is still unfunded, and data center financing for Horizons 1-4 has not closed. No calendar 2027 ARR target was offered. The funding strain shows on the balance sheet:
- Net debt jumped to $4.43 billion from $216 million.
- Unrestricted cash fell to $3.5 billion from $5.9 billion.
- Investing outflows reached $5.1 billion in the quarter.
The tone shifted accordingly, from expansive to defensive, with management stressing it would not grow at all costs.
The market had already priced in a great deal of this anxiety. Heading into the report, shares were at $21.71, down 42.3% since the open following the August report. They sat 50.4% below the 200-day moving average and 56% below the September 23 high of $49.37. The stock set a 52-week low of $21.05 just one day before results. Investor sentiment was essentially unchanged and mildly negative, near -0.22, suggesting expectations were already subdued rather than newly broken. The Earnings Whispers trend signals are split. Sequential growth and momentum read positive, while price and AVWAP remain negative, which mirrors the gap between improving operations and a deteriorating share price.
The bottom line is that IREN's quarter offered real evidence that its AI Cloud model works. Revenue is nearly tripling, segment margins are high, pricing is rising and customers are prepaying most of the GPU bill. The headline miss, the slipped ARR date, the capex reduction and the unfunded gap, however, show that capital access now governs the pace of growth. For a stock trading near its lows, the next test is execution: closing the data center financing and hitting the revised January-to-February ARR window.
Read our earnings preview for IREN Limited: https://www.earningswhispers.com/article/IREN/22315
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
