Brookfield Asset Management Beats On Record Fundraising And First Real Carry, But A Trimmed 2026 Outlook And Slowing Fee Growth Complicate The Story
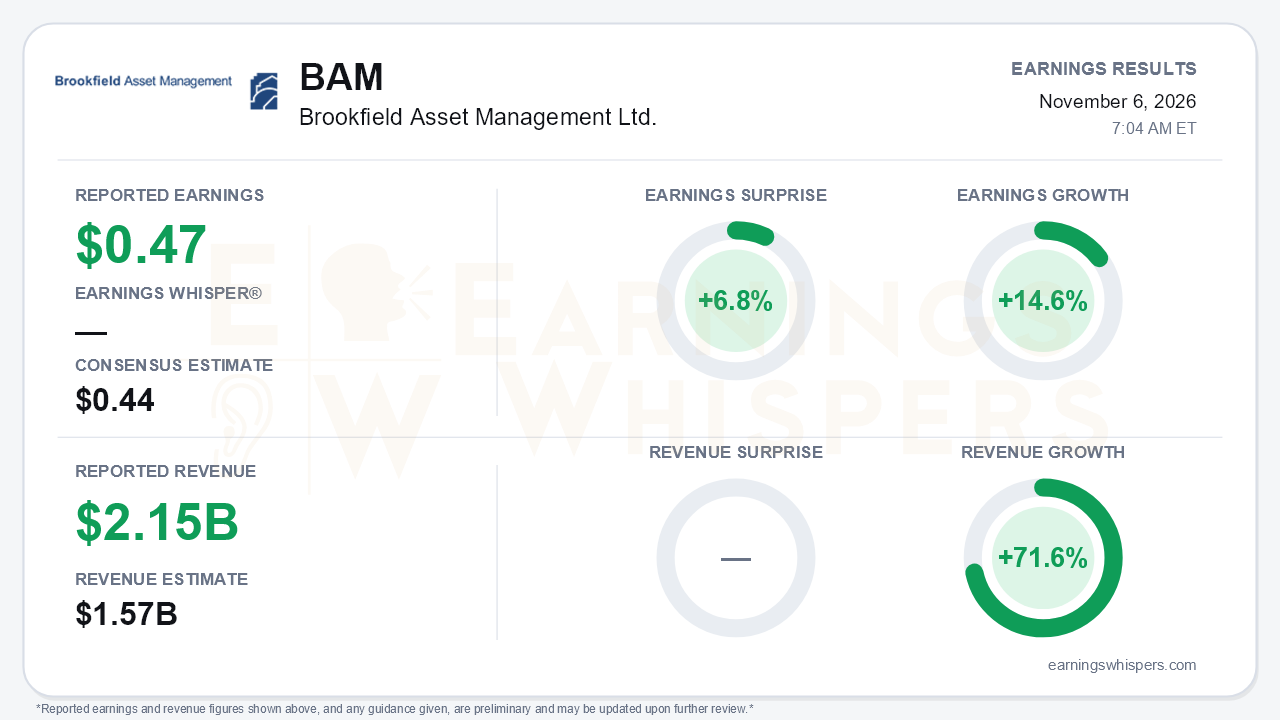
Brookfield Asset Management (NYSE: BAM) delivered a clean headline beat for the third quarter. Distributable earnings of $0.47 per share topped the $0.44 consensus by 6.8% and grew 14.6% year over year. Revenue of $2.149 billion beat the $1.57 billion consensus by 36.9% and grew 71.6%. Year-to-date fundraising reached $123 billion, already well past the $112 billion raised in all of 2025. Yet the most consequential statement of the quarter was not a number in the release. Management trimmed its 2026 earnings outlook to "in line with" its long-term targets, modestly below start-of-year expectations, after earlier framing it as exceeding them. That is the central tension: capital-formation momentum has rarely looked stronger, while the near-term earnings trajectory has softened.
The quality of the beat deserves scrutiny. The revenue surprise was driven largely by $764 million of GAAP carried interest income, versus $112 million a year ago, plus the consolidation of Oaktree. Most of that carry was unrealized. GAAP net income of $3.0 billion was inflated by a $2.0 billion non-cash gain on the Oaktree acquisition. The recurring engine was solid but less spectacular. Fee-related earnings rose 15% to $864 million, or $0.54 per share, up from $0.50 in Q2. Fee-bearing capital grew 13% to $682 billion. Both growth rates decelerated from Q2, when FRE grew 20% and fee-bearing capital grew 19%. FRE margin compressed to 54% from 57% in Q2 and 61% in Q4 2025, which management attributed to Oaktree consolidation and the new gross-up presentation for partner managers. Some of that compression is presentational, but investors used to steady margin expansion will notice the trend.
The call explained what knocked the 2026 outlook down. First, fees on the sixth infrastructure flagship now begin January 1, about two months later than planned. Second, the BBU performance fee will not be earned in 2026 because BBU's share price sits below its high watermark. Neither cause reflects weaker demand, and both look largely timing- or market-driven. Still, a guide that slid from "at or above" in Q4 to "exceed" in Q1 and now "in line with" gives bears legitimate ammunition on execution credibility. Q3 fundraising of $25 billion was also well below Q2's record $77 billion, though Q2 included the $40 billion Just Group mandate.
The forward catalysts are substantial and increasingly quantified:
- **Infrastructure flagship VI.** The fund stands at $26 billion, with $13 billion committed after quarter end, and is tracking above its $30 billion target. It could become the largest closed-end infrastructure fund ever, and its January 1 fee start should produce a visible step-up in 2027.
- **Uncalled commitments.** $68 billion of non-fee-earning commitments would add roughly $680 million of annual fees once deployed. Deployment jumped to $36 billion from $21 billion in Q2.
- **Carried interest.** BAM realized $48 million of net carry, its first meaningful amount since the spin-out. Management also laid out a long-term path: roughly $1.8 billion of unrealized net carry accrued, about $3 billion of net realizations expected in 2029-2031, and more than $2 billion per year in 2032-2037 if funds hit targets.
- **2027 fundraising.** Management now frames 2027 as at or slightly above a $100 billion-plus baseline. That is notably firmer than Q2's suggestion that 2027 would probably not match 2026.
The risks are real but mostly manageable. Near-term carry will be episodic. Corporate liquidity fell to $2.1 billion from $3.1 billion after the Oaktree closing. The AI infrastructure push, including the roughly $9 billion Korea compute venture with NAVER and NVIDIA and a potential 1GW U.K. AI factory with Drax, exposes BAM to AI-slowdown headlines. Management said its speculative exposure is de minimis. Its tone was steady rather than expansive, and it leaned on "built to perform across cycles" framing in response to more defensive questioning on AI and election volatility.
Investors entered the report skeptical. Earnings Whispers sentiment remained negative and weakened modestly, slipping to -0.24 from -0.18 at the prior report. The stock's path was volatile. Shares hit a 52-week high of $55.98 in mid-August, fell to $43.62 in late September, then rebounded more than 20% to $52.46. That leaves them roughly flat (-1.1%) since the open after the August report, 6.3% below the high, and about 9.7% above the 200-day moving average. The September sell-off and recovery suggest the market has already priced in, and partly forgiven, some deceleration. A softer guide, however, gives skeptics a reason to resist a retest of the highs.
The bottom line is that BAM's quarter pairs an exceptional fundraising and carry narrative with a modest but genuine near-term earnings disappointment. The beat itself was flattered by unrealized carry and Oaktree accounting. Meanwhile, FRE growth, fee-bearing capital growth, and margins all slowed, and the 2026 outlook was cut a notch. The causes of the guide-down look like timing rather than demand, and the 2027 setup, anchored by flagship VI fees, deployment of uncalled capital, and a firmer fundraising baseline, arguably improved. Whether investors focus on the trimmed 2026 guide or the 2027 pipeline will likely determine how the stock trades from here.
Read our earnings preview for Brookfield Asset Management Ltd.: https://www.earningswhispers.com/article/BAM/22469
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 |
Brookfield Sees AI Boom Creating Unexpected Winners Beyond Data Centers and Chipmakers
BAM +6.65%
Benzinga Private Markets
|
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-21 |
