Uniti Misses Badly On EPS As AI Fiber Upside Merely Offsets A Kinetic Guidance Cut
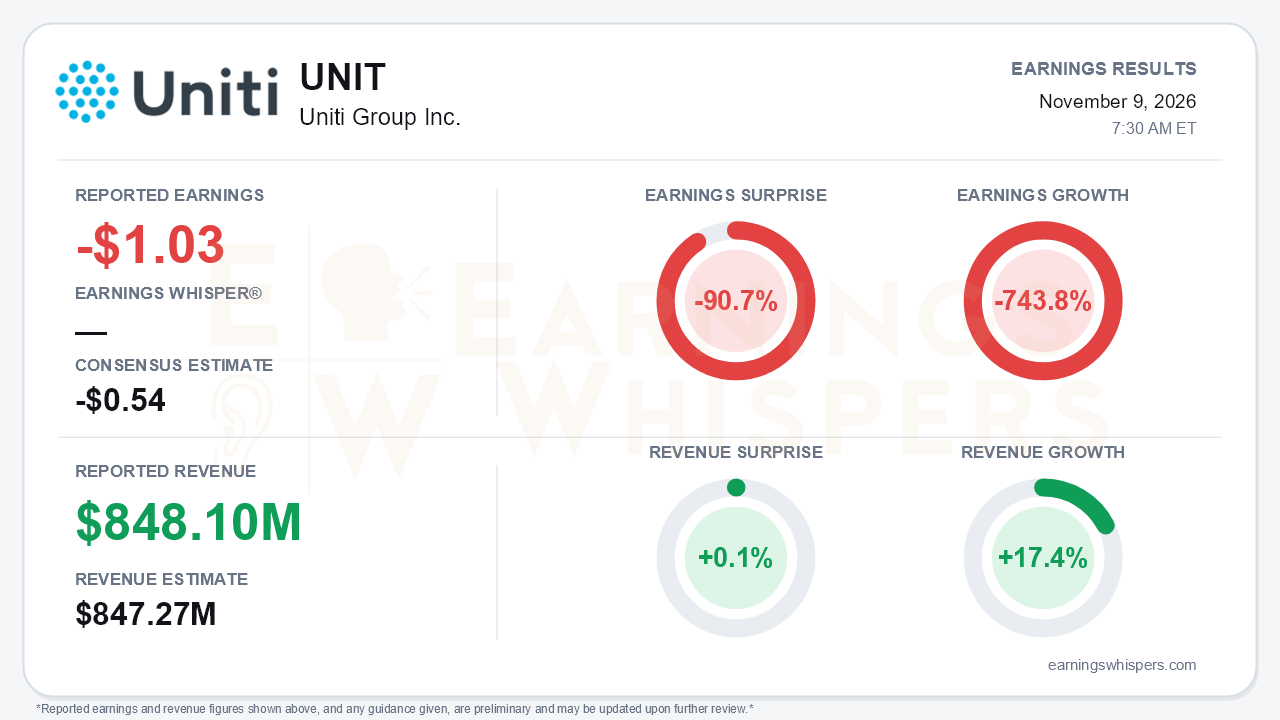
Uniti Group (NASDAQ: UNIT) reported a third-quarter loss of $1.03 per share, far worse than the -$0.54 consensus and a 90.7% miss. Revenue of $848.1 million essentially matched the $847.27 million estimate, beating by 0.1%, and grew 17.4% year over year. Both year-over-year comparisons are distorted by the Windstream merger. The 17.4% revenue increase reflects a larger combined company. The 743.8% earnings decline reflects a year-ago quarter that included a $1.69 billion gain on settlement of preexisting relationships, which produced net income of $1.61 billion versus this quarter's $244.5 million net loss. The cleaner read is the pro forma trend, and it is getting worse. Management's pro forma figures showed consolidated revenue down 10% and adjusted EBITDA down 22% year over year. That compares with declines of 5% and 10% in the second quarter and gains of 1% and 10% in the first. That deceleration is the central story beneath a headline that otherwise looks like an in-line revenue print.
The quality of the quarter deserves scrutiny. Adjusted EBITDA fell to $289.3 million from $327.8 million a year earlier. Fiber Infrastructure contribution margin dropped to $98.4 million from $156.7 million. Management attributed the weakness to three factors:
- a TDM-to-strategic wholesale conversion charge;
- a hyperscaler deal that slipped from Q3 into Q4;
- higher Kinetic retention spending.
The press release headline touts raised revenue guidance, and that is technically accurate: the consolidated midpoint moved to roughly $3.68 billion from $3.655 billion. Adjusted EBITDA guidance, however, was held at a $1.475 billion midpoint. Uniti did not raise its outlook so much as reshuffle it. The slipped deal also concentrates more of the full-year delivery into the fourth quarter.
The call laid bare a genuinely split business. Fiber Infrastructure guidance rose for a second straight quarter, to $1.045 billion of revenue and $600 million of contribution margin. Uniti Solutions guidance rose to $715 million and $345 million. The multi-year AI plan was lifted again, with the recurring annual cash revenue range raised to $450-550 million from $400-500 million. Management said 100% of AI-related revenue for the rest of 2026 and all of 2027 is booked. New-bookings MRR of about $1.9 million was the second highest on record and up 20% year over year, though it was below the second quarter's $2.2 million record.
Kinetic told the opposite story. Operationally it set records, with 162,000 homes passed and about 46,000 fiber net adds. Consumer fiber revenue growth accelerated to 22% from 19%. Financially, however, guidance was cut:
- Kinetic revenue midpoint fell to $2.11 billion from $2.145 billion.
- Kinetic contribution margin midpoint fell to $855 million from $905 million.
- Consumer fiber revenue guidance dropped to $610-630 million.
Fiber ARPU has swung from +5% growth early in the year to declines. Roughly 20% of the fiber base was re-rated, and the long-term ARPU outlook was softened to low-single-digit growth. Management conceded that fixed wireless and cable competition exceed the original plan and said DSL churn will not return below 2%. Fiber penetration is stuck near 29% even as the footprint expands. Uniti is building faster than it can monetize.
The balance sheet amplifies that problem, and bears have legitimate ammunition here:
- Net debt rose to $11.27 billion from $9.53 billion at year-end.
- Shareholders' equity has turned to a $79.5 million deficit.
- Interest expense is guided to $800 million for the year.
- Nine-month capex of $1.27 billion was nearly three times operating cash flow of $467 million.
- 2026 net capex guidance has climbed to $1.525 billion from $1.4 billion.
Management's description of capital markets shifted from buoyant last quarter to "challenging." It acknowledged convertible notes maturing at the end of 2027 and emphasized roughly $1 billion of liquidity and not being a forced seller. Mitigating catalysts include:
- a $500 million secured debt paydown funded through asset-backed securities;
- the CBRS spectrum sale, the first step in a $500 million to $1 billion non-core monetization program;
- growing strategic and joint-venture interest in Fiber Infrastructure.
The market had already priced in much of this skepticism. Shares fell 47.7% from the $9.98 open after the prior report to $5.22. That leaves the stock about 44.5% below its 200-day moving average and only about 10% above the 52-week low of $4.74 set on November 5, days before the release. Investor sentiment slid meaningfully, from a slightly positive 0.04 to -0.34. Price and AVWAP trend readings remain negative.
The bottom line is that Uniti's AI-driven fiber franchise keeps getting more valuable on paper, but this quarter it only offset a deteriorating consumer business rather than lifting the consolidated outlook. Pro forma EBITDA declines are steepening, Kinetic's unit economics are being reset lower, and leverage is rising into tougher credit markets. With the stock near its lows, sentiment has caught up to the risks. A durable rerating likely requires fourth-quarter delivery of the slipped hyperscaler revenue, visible ARPU stabilization, and asset sales that actually reduce debt.
Read our earnings preview for Uniti Group Inc.: https://www.earningswhispers.com/article/UNIT/22597
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 |
