Constellation Energy Beats By 30% And Raises Guidance Again, But Its Biggest Wins Arrive After 2027 And The Stock Remains Under Pressure
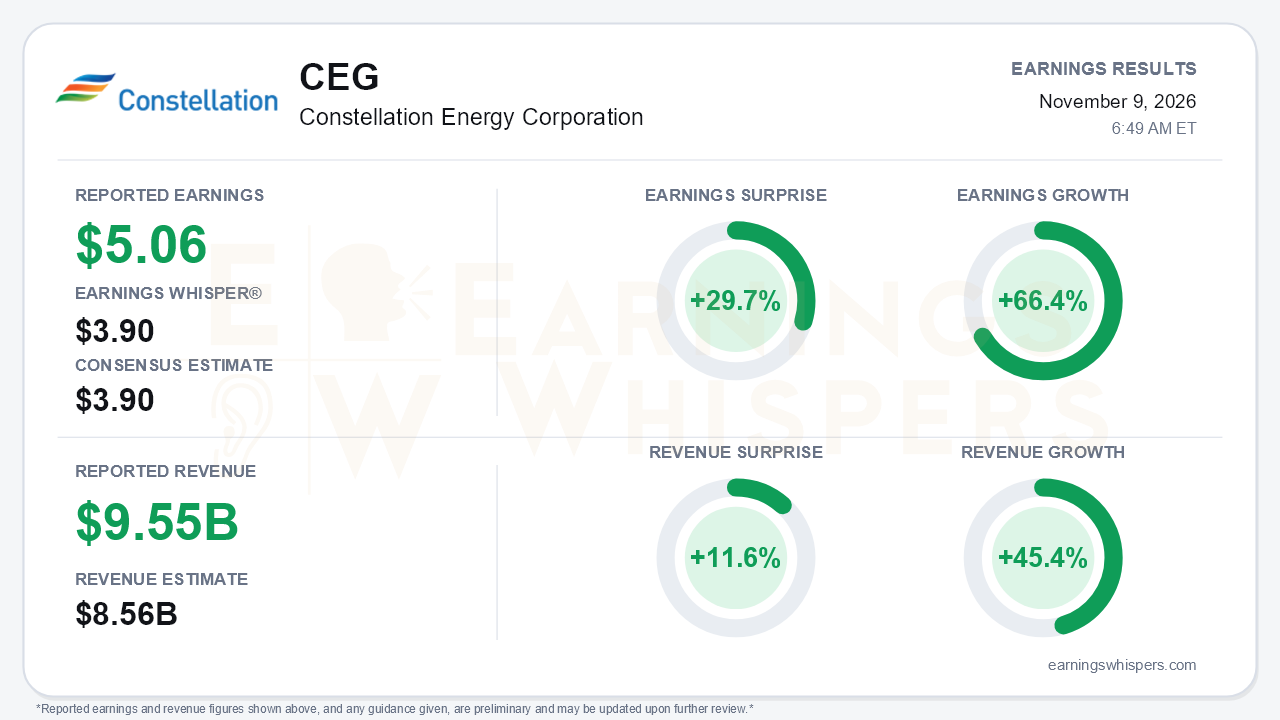
Constellation Energy delivered the most forceful quarter of its year. Adjusted operating earnings of $5.06 per share beat both the $3.90 consensus and the identical Earnings Whisper number by 29.7%. Revenue of $9.55 billion topped the $8.56 billion consensus by 11.6%. Earnings grew 66.4% year over year and revenue rose 45.4%, with Calpine in the base for the first full comparison period. Growth also accelerated sharply. Adjusted EPS rose $2.02 from a year ago, after gains of only $0.64 in the second quarter and $0.60 in the first. Management raised the midpoint of full-year guidance for the second time, to $12.50-$12.80. The new floor sits $0.50 above the top of the original $11.00-$12.00 range. The central tension is that much of what makes this report important, a wave of long-dated nuclear contracts and uprates, does not reach earnings until 2028 and later. Meanwhile, the market is discounting political and credit risk around the data-center trade today.
The quality of the beat holds up better than the GAAP figure suggests. GAAP net income was $5.19 per share, up from $2.97. That figure was flattered by a $0.36 unrealized fair-value gain and a $0.30 deferred-tax apportionment benefit, which pushed the GAAP effective tax rate down to 18.2% from 33.4%. The adjusted figure strips those out. It also excludes $0.20 of Calpine integration costs and $0.11 of acquired-contract amortization. Management attributed the adjusted improvement to favorable market and portfolio conditions and the Calpine addition. Those gains were partly offset by higher interest costs and lower nuclear production tax credit revenue. Net interest expense climbed to $217 million from $134 million. The per-share gain is notable because diluted shares rose to 354 million from 313 million after the Calpine deal. Operations also helped: nuclear capacity factor reached 97.2%, up from 96.8%, and management cited 99.2% over the summer, a clear rebound from 93% in the second quarter and 92.3% in the first.
The call marked a step-change in contract duration. Earlier in the year, management conceded it was behind on contracting because of uncertainty over PJM rules. Since the second quarter, Constellation has signed roughly 4,560 MW of long-term nuclear agreements, bringing the year-to-date total above 8,500 MW. Contracted clean output now reaches about 91 million MWh by 2032, roughly 45% of the clean fleet. That compares with about 30% at the second quarter and about 25% for 2030 earlier this year. The key deals were:
- **Google:** a 20-year PPA that funds more than $4.3 billion of investment to add about 890 MW of uprates across 11 units, plus a 15-year, 2,700 MW load-following agreement.
- **Amazon:** a 20-year, 690 MW agreement that underwrites more than $3 billion at Calvert Cliffs, including a 190 MW expansion.
- **Peak+:** the first deal under the new product, covering 270 MW over 20 years.
The tone shifted from defensive in March to emphatic.
The forward-looking developments also extend the runway. The Crane restart has been pulled forward to the second half of 2027, a year early and under budget. A conditional DOE loan commitment of up to $5 billion, priced at 37.5 basis points over Treasuries, could save roughly $40 million a year in pre-tax interest. The $715 million Rhode Island State Energy Center acquisition is expected to be immediately accretive and credit neutral. About $3 billion of buybacks have been executed since March, and a buyback update is signaled on or before the fourth-quarter call.
Bears still have legitimate ammunition:
- The uprates add roughly $3 billion of incremental growth capex from 2028 to 2032.
- A compensation-driven O&M headwind emerged, and PTC revenue is running lower.
- Management explicitly warned that 2026's enhanced-earnings outperformance is not necessarily repeatable. It said 2027 should be anchored to the March outlook because the new contracts ramp later.
- PJM's backstop auction has been delayed, and FERC co-location action is not expected until the first half of 2027.
The market has been focused on those risks. Shares sit at $249.95, down 10.1% since opening at $277.92 after the August report and about 10.3% below the 200-day moving average of $278.73. The stock reached $309.80 on October 6, then slid to an inter-earnings low of $231.30 on November 5 as post-election data-center policy uncertainty and AI-related debt concerns weighed on the group. Management called that reaction an overreaction. Shares entered the report 19.3% below the quarter high and only 8.1% above the low. Investor sentiment remained negative and edged slightly lower, from -0.20 to -0.22. Price and AVWAP trend readings remain negative, consistent with the stock's recent behavior.
The bottom line is that Constellation produced a decisive beat, accelerating per-share growth and a second guidance raise. More importantly, it converted a large share of its nuclear fleet into multi-decade contracted cash flow. What the report cannot do is close the timing gap: the new earnings power arrives mostly from 2028 onward, 2027 guidance is anchored to the March outlook, and policy and credit fears are hitting the stock now. Investors entered skeptical, with shares sitting closer to the quarter's low than its high. Whether these results reset that narrative depends on whether the regulatory overhang eases before the contracts start contributing.
Read our earnings preview for Constellation Energy Corporation: https://www.earningswhispers.com/article/CEG/22555
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 14 min | |
| 4 hours | |
| 5 hours |
Nuke Stock Constellation Fueled By Earnings; NRG Hits Gas On Buybacks
CEG +10.46%
Investor's Business Daily
|
| 5 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 10 hours | |
| 11 hours | |
| 12 hours | |
| Nov-08 | |
| Nov-05 |
