MARA Beats A Low EPS Bar, But Revenue Misses Badly And The HPC Lease Catalyst Slips Toward 2027
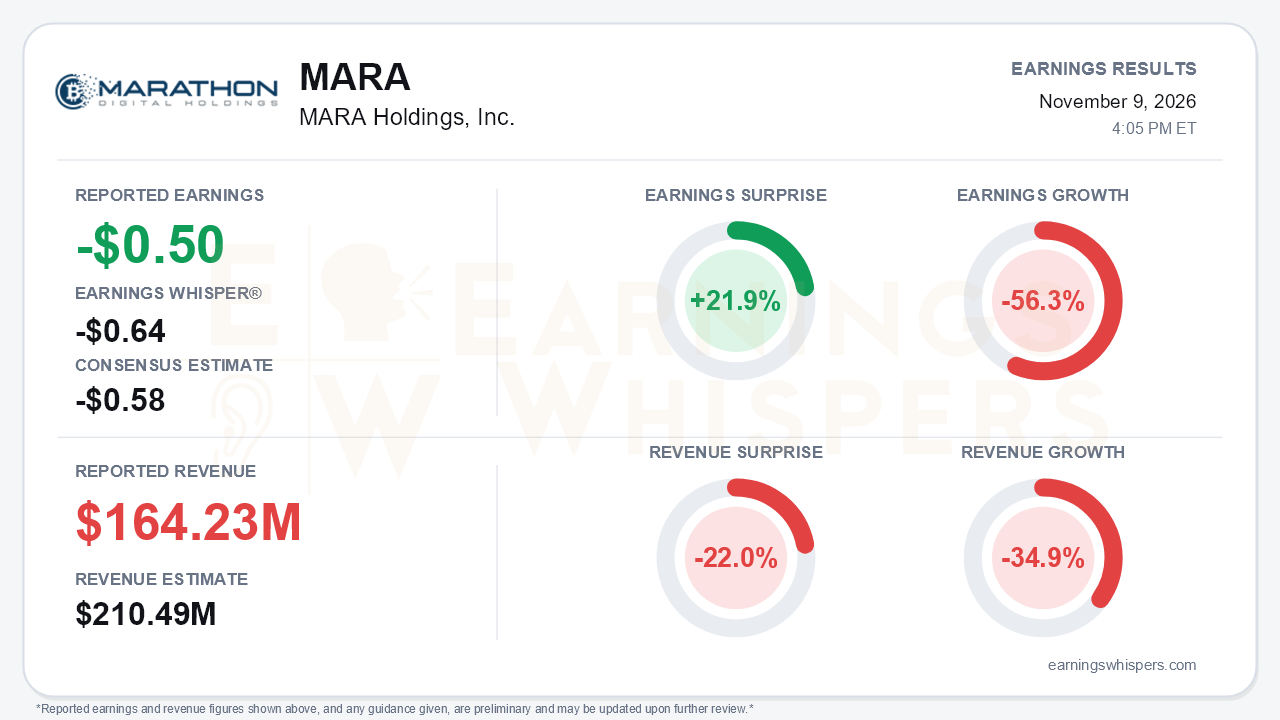
MARA Holdings delivered a quarter in which the balance sheet improved while the operating story weakened. The company reported a loss of $0.50 per share for the September quarter. That beat the -$0.58 consensus by 21.9% and cleared the more pessimistic -$0.64 Earnings Whisper number. Revenue was a different story. At $164.23 million, it missed the $210.49 million consensus by 22.0% and fell 34.9% year over year, while earnings fell 56.3%. A beat on a loss estimate paired with a revenue miss of that size is not a clean quarter. The more consequential news was that the HPC leasing milestone investors have been waiting for may not arrive this year. That is the central tension: the balance sheet is being repaired, but the transformation narrative lost time.
The quality of the reported numbers deserves scrutiny. Management cited GAAP net income of $632.1 million and adjusted EBITDA of $857.7 million. Both figures were driven by an $885 million Bitcoin fair-value gain, and the prior quarter showed a $611.3 million net loss. The normalized per-share loss sits far from the GAAP profit, which suggests it reflects results without that mark-to-market swing. On that basis, the core business lost money. Revenue has now declined from $202.3 million in Q4'25 to $174.6 million, $174.9 million and $164.2 million. That is a persistent deceleration, not a one-quarter dip, and it was tied largely to a 37% year-over-year drop in the average Bitcoin price.
The mining metrics softened across the board:
- Bitcoin mined fell to 2,247 (24.4 per day) from 2,422 (26.6 per day), even as energized hash rate edged up to 71.2 EH/s from 70.3.
- Share of network rewards slipped to 5.4% from 5.9%.
- Cost per PH/day rose to $30.8 from $27.7, with summer heat lowering effective hash rate.
- Purchased energy cost per Bitcoin rose to $39,674 from $38,690.
In short, MARA produced less and paid more per coin. Hosting contracts covering roughly 29% of energy capacity also roll off between Q3'27 and Q1'28, which will require the fleet to be reallocated.
The call's forward-looking language was more guarded:
- **Lease timing:** Management is "still targeting" two lease signings before year-end, but says timing "could move into next year," with delays attributed to tenants. That is a clear retreat from Q2's stated confidence in at least two leases by year-end, and from Q1's expectation of multiple leases.
- **Power portfolio:** The expected portfolio was framed as "over four gigawatts" on the call, versus roughly 4.8 GW in Q2. The release's boilerplate still cites a path to approximately 4.8 GW, an inconsistency investors should press on.
- **Financing conditions:** Management flagged a more selective AI financing market and higher financing costs.
- **Investor Day:** The event promised last quarter was not reiterated.
There is real progress to weigh against those setbacks:
- **Long Ridge:** The acquisition cleared FERC approval, its last material contingency, with closing expected within weeks. The plant brings more than $140 million of annualized EBITDA, about 70% contracted.
- **Exion:** The unit signed its first contract, a four-year, $79 million GPU-as-a-service deal on 100% take-or-pay terms, with service expected to begin before year-end. Its $3 billion pipeline remains uncommitted.
- **Deleveraging:** After the quarter, MARA sold 13,597 BTC at about $81,000 to repay $750 million of Bitcoin-backed debt, for an estimated $170 million net benefit. Pledged or loaned Bitcoin fell from 57% of holdings to under 5%, and year-to-date debt reduction reached $1.4 billion, or 37% of total debt.
- **Liquidity:** Cash rose to $946.5 million from $421.3 million.
- **Buyback:** The board authorized a new $500 million repurchase program.
- **Other developments:** Management cited a post-election surge in site demand and commercialized its Vertebrae flexible energy-compute platform.
These are bears' and bulls' arguments at once. A buyback and a debt paydown funded by Bitcoin sales strengthen the balance sheet, but they also shrink the Bitcoin position and shift capital toward repurchases while the lease pipeline stalls.
The market had already priced in considerable disappointment. Shares sat at $6.35 before the report, down 41.8% from the $10.91 open after the August release. That left them roughly 40.6% below the 200-day moving average and 54.6% below the September 21 inter-earnings high of $13.98. The stock set a 52-week low of $5.69 on November 5 and entered earnings only 11.6% above it. Investor sentiment was essentially unchanged and mildly negative, at -0.080 versus -0.079 after the prior report. Price and AVWAP trend readings remain negative, while sequential growth and momentum are neutral.
The bottom line is that MARA de-risked its balance sheet and moved Long Ridge and Exion forward, but the quarter's operating evidence pointed the wrong way. Revenue kept shrinking, unit mining economics worsened, and the lease catalyst at the heart of the infrastructure thesis may slip into 2027. The EPS beat matters less than whether management can convert site demand into signed leases. Until it does, a deeply discounted stock reflects skepticism the quarter did little to dispel.
Read our earnings preview for MARA Holdings, Inc.: https://www.earningswhispers.com/article/MARA/22649
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 5 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 |
