Disney Faces Parks And Streaming Test As Stock Nears Highs Ahead Of Fiscal 2027 Outlook
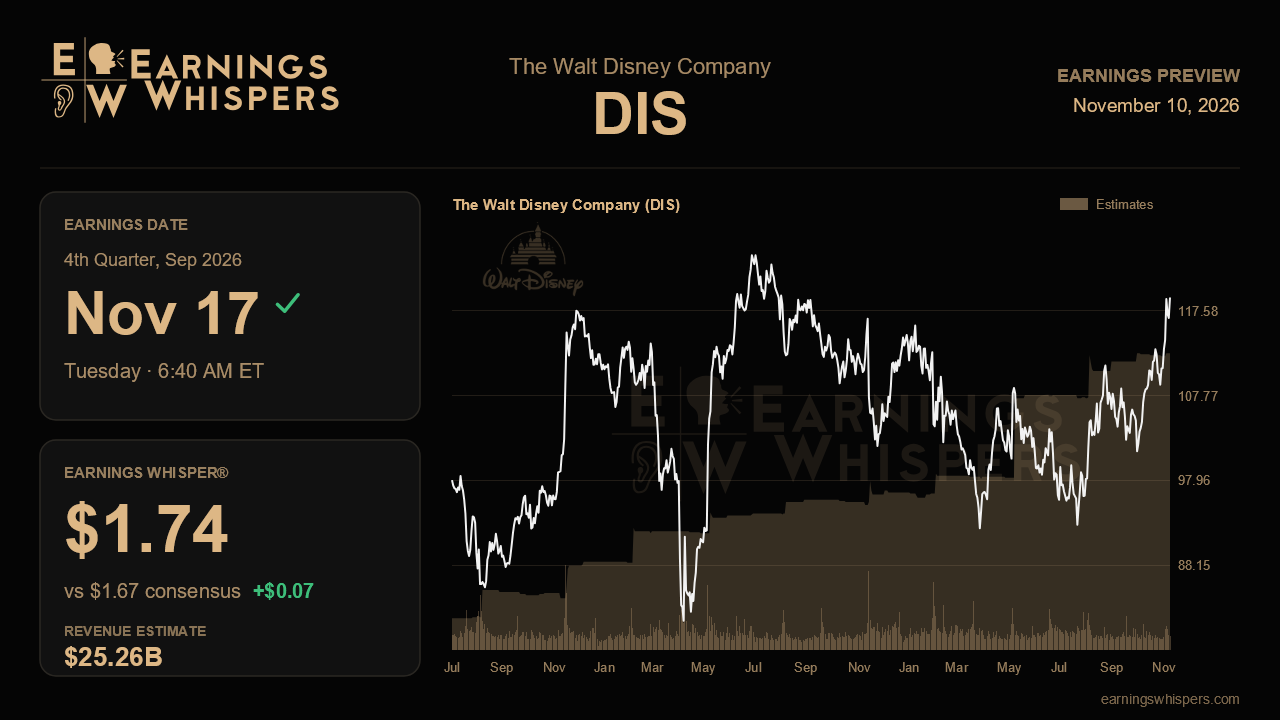
Disney heads into its fiscal fourth-quarter report with something it lacked a few quarters ago: momentum in both the business and the stock. The question now is whether the back-half acceleration that new CEO Josh D'Amaro's team delivered last quarter can carry into the fiscal year-end. Just as important is whether management can make the Street believe its fiscal 2027 targets, which analysts still treat with noticeable skepticism.
Wall Street expects earnings of $1.67 per share on revenue of about $25.26 billion. That would be a 50.5% jump in profit from the $1.11 earned a year ago, on sales growth of 12.5%. Those are strong growth rates, although revenue is projected to be essentially flat with last quarter's $25.25 billion. The year-over-year comparison is doing much of the heavy lifting, and the fiscal year also includes an extra week that management has carved out of its parks guidance. The Earnings Whisper sits at $1.74, modestly above consensus, which suggests the informal bar is a bit higher than the published one.
The guidance picture is where the setup gets interesting. Management reaffirmed fiscal 2026 earnings of roughly $6.88 per share, and consensus sits slightly below at $6.83. That gap is small enough that a solid quarter should close it. The bigger disconnect is fiscal 2027. The company is holding to about $7.91 per share, while analysts sit near $7.43, well below management's outlook. In effect, the Street is discounting the plan. This report and the commentary around it are Disney's best opportunity to narrow that credibility gap, or to have it widen if management softens the target.
The operating evidence starts with the parks. Last quarter marked a real inflection, with domestic attendance up 3% and per-capita spending up 4%. That followed a 1% attendance decline the quarter before, and global guest counts accelerated as well. Management lifted its Experiences profit outlook to the high end of its high-single-digit growth range. Delivering that number is now table stakes. Healthy forward bookings at Walt Disney World and in cruise would validate the turn. Continued softness in Shanghai and Hong Kong, which management said was carrying into this quarter, and lingering weakness in international visitation to U.S. parks are the main threats. Streaming is the second pillar. Subscription video margins reached 13%, putting the double-digit full-year target within reach. However, rising ad supply is pressuring streaming ad pricing, so investors should look for signs that strong upfront volume, sold-out Super Bowl inventory and double-digit sports commitments are offsetting softer rates.
The studio is the wild card. Toy Story 5 crossed $1 billion, but The Mandalorian and Grogu and the live-action Moana both disappointed. Management leaned on its portfolio argument to defend double-digit earnings growth. A quarter in which parks and streaming absorb theatrical volatility would strengthen that case. Commentary on the TikTok content deal, a possible free ad-supported tier, and the expanded Disney+ ecosystem slated for spring 2027 will matter mostly as support for the 2027 trajectory. So will the pace of the buyback, now set at a minimum of $8 billion for the year.
Sentiment has swung from mildly bearish before the last report to clearly bullish now, and the stock has followed. Shares are up nearly 17% since the last report while the S&P 500 fell 3%. At $119.12, the stock trades well above its 200-day average near $104 and sits within about 1.5% of its post-earnings high of $120.80, effectively testing a breakout. That leaves less room for a merely adequate print. Ultimately, the report will be judged on whether parks strength and streaming profitability look durable enough to make $7.91 in fiscal 2027 credible. If they do, the Street's discount could start to close. If they don't, a rally built on that confidence becomes vulnerable.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 4 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 |
