JD.com Must Prove Its Profit Turnaround Can Coexist With A Promised Return To Growth
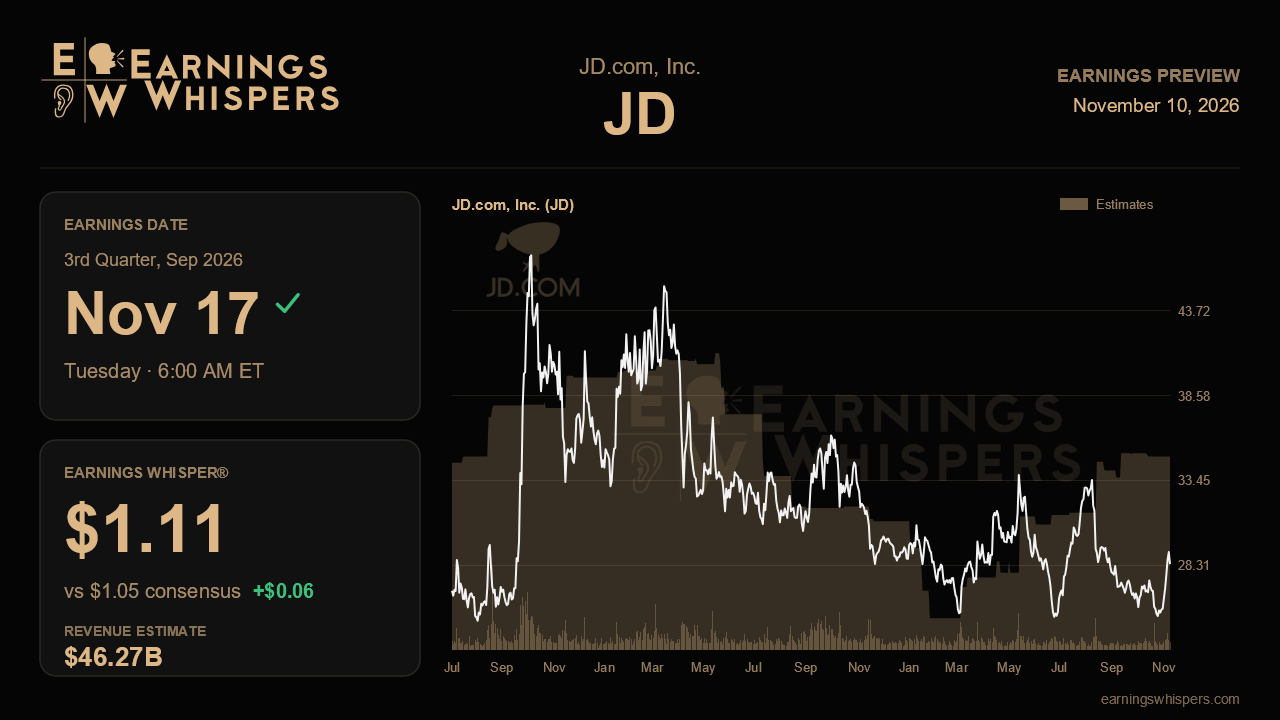
JD.com heads into its November 17 report with a credibility test that cuts in two directions. Last quarter management described results as a decisive turning point for profitability, and the numbers backed that up: margins, profits and free cash flow all improved sharply even as revenue slipped into outright decline. The company also promised that JD Retail would return to positive revenue growth this quarter. The upcoming release has to show both halves of that story at once. Investors need fatter margins and a top line that is growing again.
The Street is leaning hard on the growth half. Consensus calls for non-GAAP earnings of $1.05 per share on revenue of about $46.27 billion. That implies roughly 10.1% year-over-year revenue growth, a sharp swing from the 2.9% decline reported last quarter. On earnings, the estimate is well over double the $0.44 posted in the same quarter a year ago, when heavy spending on new businesses, especially food delivery, crushed profitability. The Earnings Whisper sits at $1.11, about 6% above consensus. That is not a dramatic gap, but it suggests the informal bar is set above the published number. A merely in-line print may not satisfy everyone. Management offered no formal numeric guidance, so the main yardstick is its qualitative promise of second-half reacceleration.
The biggest operating question is whether electronics and home appliances have turned the corner. Last quarter that category was weighed down by a tough comparison against the government trade-in subsidy boom and by upstream memory and component price hikes that pushed device prices higher. Management argued the trade-in base normalizes in the second half. If electronics growth improves meaningfully, the reacceleration thesis looks earned. If component inflation is still dampening demand, the 10% revenue forecast could prove ambitious. General merchandise, once the steady engine, also cooled last quarter, so a rebound in supermarket and everyday categories would broaden the recovery.
The advertising engine deserves equal scrutiny. Marketplace and marketing revenue growth slowed to 8.3% from 18.8% the quarter before, against a high traffic base. This is JD's highest-margin revenue stream, so a further slowdown would raise doubts about how long the margin gains can last. Those gains were striking. JD Retail gross margin reached 18.5%, its 17th straight quarter of year-over-year expansion, and group non-GAAP net margin climbed to 2.6% from just 0.3% two quarters earlier. Food delivery losses narrowed by more than half. Investors should check that losses there keep shrinking while spending on JoyBuy in Europe and Jingxi, which management said was stepping up, does not eat the improvement elsewhere. Free cash flow, which rose to about RMB31 billion on a trailing basis, is another checkpoint. Management attributed part of that gain to receivables collections that may not repeat.
The market has not given management the benefit of the doubt. Shares are down 8% since the last report, trailing the S&P 500 by about five percentage points. The stock sits at $28.38, just under its 200-day moving average and roughly mid-range between its post-earnings low of $25.06 and high of $31.37. Sentiment has edged up to slightly bullish from essentially neutral, a modest shift that falls short of enthusiasm. A $1 billion remainder on the buyback authorization offers some support. Still, the setup looks like a skeptical market waiting for proof rather than one already pricing in success.
Ultimately, this report hinges on whether JD can deliver the promised revenue rebound without giving back the margin gains that made last quarter so encouraging. Positive retail growth with stable or rising margins would validate the turning-point narrative and could pull the stock out of its trading range. Strong margins alongside a stalled top line would suggest last quarter's profits came more from retreating than from reigniting the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 11 hours | |
| Nov-07 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-10 | |
| Oct-05 | |
| Oct-02 | |
| Oct-02 | |
| Sep-29 |
