Home Depot Must Prove Its Summer Comp Acceleration Was A Trend, Not A Blip
Home Depot exited its second quarter with the best demand story it has told in more than a year. Comparable sales climbed 1.7%, U.S. comps strengthened every month and reached 2.2% in July, and 13 of 16 merchandising departments posted gains. Management still declined to raise its full-year outlook, citing a wide range of possible back-half outcomes and fresh cost pressures. The third-quarter report on November 17 is the first real test of which reading was right: the confident one from the quarter's results, or the cautious one from the guidance.
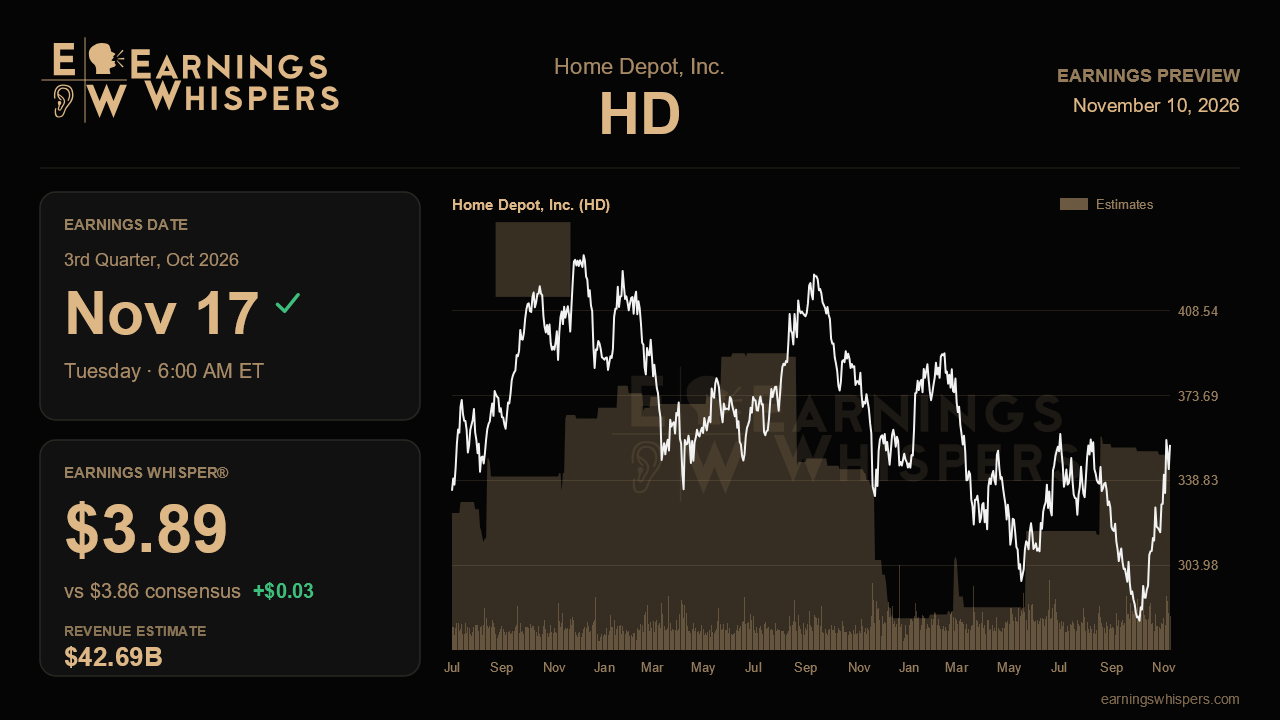
The Street is looking for earnings of $3.86 per share on revenue of $42.69 billion, both up about 3.2% from $3.74 and $41.35 billion a year ago. That is modest growth, roughly consistent with a business comping in the low single digits rather than one breaking into a new upcycle. The Earnings Whisper of $3.89 sits only slightly above consensus, which suggests some appetite for a small beat but not a dramatic one. For the full year ending January 2027, consensus of $14.99 per share falls almost exactly at the midpoint of management's reaffirmed $14.69 to $15.28 range. Revenue expectations of $171.65 billion, however, lean toward the upper end of the $168.80 billion to $172.09 billion outlook. Analysts are effectively betting on better sales without much margin help, a reasonable read given what management said about costs.
The most important question is whether July's momentum carried through the fall. Growth last quarter was driven entirely by ticket, up 2.8%, while transactions fell 1%. A quarter in which traffic stabilizes or turns positive would make the recovery look far more durable than one powered by price and mix. Big-ticket transactions over $1,000, which jumped 2.4%, are another key signal. Sustained strength there would hint that customers are again willing to take on larger projects despite housing turnover stuck near 40-year lows. SRS also deserves attention after it finally comped above the company average and turned positive across all verticals. Continued strength, along with progress toward the roughly $400 million cross-sell run rate, would show the pro strategy is gaining traction rather than enjoying a single good quarter. Newer initiatives, including nationwide Express delivery and the exclusive USG gypsum launch, are early, but any evidence they are lifting share would support the narrative.
Margins are where the setup gets murkier. The second quarter benefited from a $685 million tariff refund worth roughly 145 basis points of gross margin. That boost does not repeat, and management flagged about 60 basis points of unplanned pressure from fuel, energy, resin and metals, plus incremental tariff changes. Its full-year gross margin target of about 33.1% leaves little room for slippage. A third-quarter margin that holds near plan despite those headwinds would be reassuring. A visible squeeze would challenge the idea that sales gains can translate into earnings growth. Return on invested capital, which has slipped for four straight quarters, and an update on CEO Ted Decker's medical leave round out the secondary concerns.
The market has already moved toward the optimistic view. Shares are up 4.9% since the last report while the S&P 500 fell 2.1%, and sentiment has improved from 13.7% bearish to just 4.8% bearish. At $353.42, the stock trades comfortably above its 200-day average of $333.52 and within about 2.5% of its post-earnings high of $362.44, putting a breakout attempt within reach. That positioning raises the bar somewhat, since a merely in-line print may not be enough to push through resistance.
Ultimately, the report hinges on whether Home Depot can show that demand kept broadening while it absorbed the loss of the tariff windfall. Steady comps near or above 2%, improving traffic and margins held near plan would give management grounds to finally narrow or lift its outlook. Fading comps or margin erosion would suggest last quarter's acceleration was more fleeting than it looked.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| Nov-08 | |
| Nov-07 | |
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 |
