TJX Needs A Marmaxx Rebound To Back Its Raised Outlook As Street Lags Guidance
TJX heads into its third-quarter report with an odd mismatch. Management keeps raising its targets, but the stock keeps losing ground. The off-price giant has lifted its full-year profit outlook repeatedly. Even so, shares have fallen since the last report and sentiment has turned negative. The reason is Marmaxx, the company's largest division. Its comparable sales slowed to just 1% last quarter after running at 6% for three straight quarters. This report is the first real test of whether that slowdown was a temporary stumble or the start of something more stubborn.
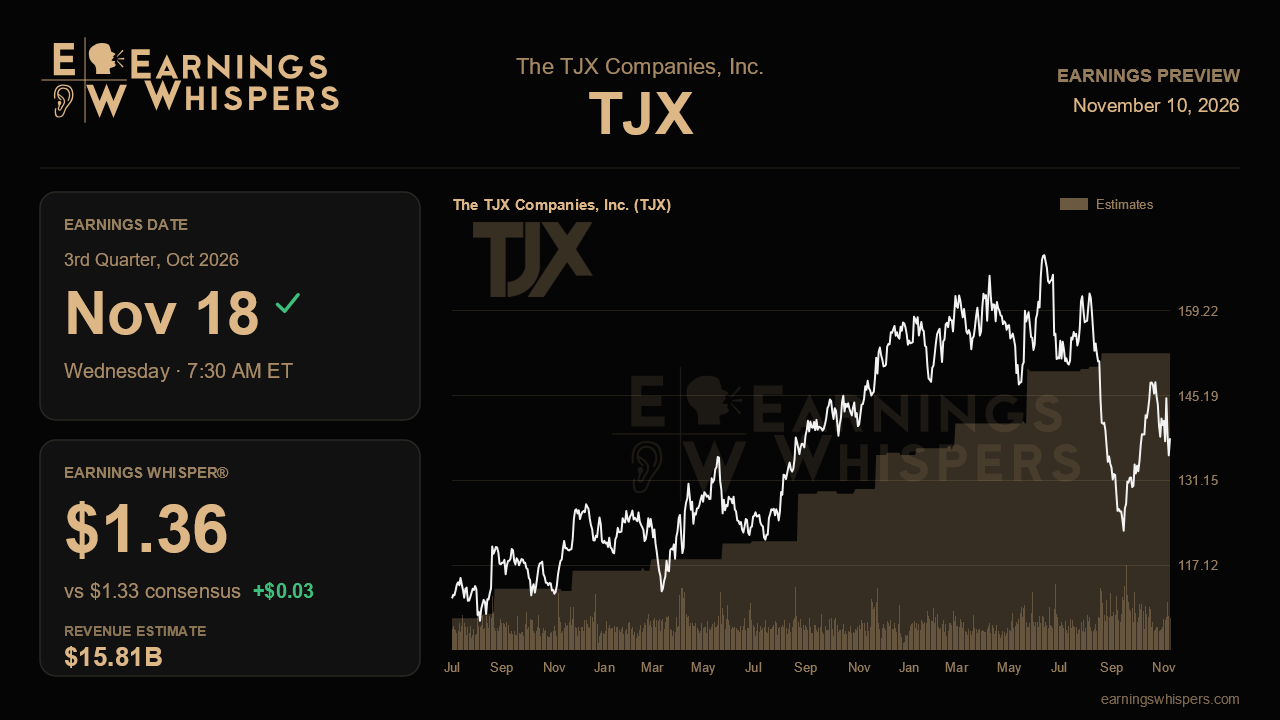
Wall Street expects earnings of $1.33 per share on revenue of about $15.81 billion. That would be EPS growth of roughly 3.9% and sales growth of 4.6%, which is solid but unspectacular. The more telling comparison is with management's own numbers. TJX's most recent outlook calls for third-quarter EPS of $1.36 to $1.38, so consensus sits below the bottom of the range. The full-year gap is wider still. The company now guides to $5.31 to $5.36 per share, while the Street sits around $5.19. That outlook marks a steady climb from an initial $4.93 to $5.02. The Earnings Whisper of $1.36 lands right at the low end of quarterly guidance, which suggests the more informed bar is management's range rather than published consensus. In other words, clearing $1.33 is not much of a victory. Investors will want results at or above guidance.
The margin setup makes that harder than it sounds. Management told investors to expect a third-quarter pretax margin of 12.3% to 12.4%, down 30 to 40 basis points from a year ago. It cited three pressures: higher fuel costs, freight inflation tied to truck driver shortages, and the reversal of tariff-related merchandise margin benefits that helped the first half. The company also guided to comparable sales growth of 2% to 3%, a clear step down from 4% last quarter and 6% in the first quarter. Results that beat those modest targets while holding the margin decline near the shallow end would suggest the conservatism was deliberate. A margin decline closer to the deep end would suggest freight and tariff costs are biting harder than planned.
Marmaxx is where the narrative will be won or lost. Management blamed last quarter's slowdown on its own execution, specifically sending the wrong merchandise to the wrong stores, rather than on competition or weaker shoppers. It also said improvement would build into the fourth quarter. That framing is reassuring only if the numbers start to back it up. A Marmaxx comp moving back toward the mid-single digits, along with a segment margin above last quarter's flat 14.2%, would support the self-inflicted explanation. Another quarter near 1% would make that excuse harder to accept and would raise questions about whether the core U.S. apparel business is losing traction.
The rest of the portfolio gives TJX some cushion. HomeGoods, Canada and International all posted comps of 6% to 7% last quarter. HomeGoods and International also expanded margins by more than 200 basis points each. Management raised its long-term store target to 7,500 from 7,000 and plans to accelerate annual unit growth to 4%. It has also grown more enthusiastic about TK Maxx in Spain, which it considers upside not yet reflected in its forecasts. If those divisions hold their pace, a soft Marmaxx quarter may not sink the consolidated numbers.
The market is not giving TJX much benefit of the doubt. The stock has fallen 4.2% since the last report, trailing the S&P 500 by nearly 2 percentage points. At $138, it sits well below its 200-day moving average near $151. It trades in a post-earnings range of roughly $123 to $151, entirely below the prior quarter's $148 to $170 band. Sentiment has swung from mildly bullish to mildly bearish. That cautious positioning lowers the emotional bar, even though the earnings bar set by guidance remains high. The verdict hinges on Marmaxx: evidence of a turn would make the guidance raises look credible, while continued weakness would suggest the raised outlook rests on a narrower base than investors assumed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Oct-29 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-12 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-18 | |
| Sep-18 |
